Saurashtra Cement (SAURASHCEM) Q2 FY27 Swings to Loss as Revenue Plunges 18%
Saurashtra Cement's Q2 FY27 saw a sharp revenue decline and a return to losses, highlighting intense pricing pressure and a volatile market for regional players.
Saurashtra Cement posted a net loss of ₹8.6 crore in Q2 FY27 as revenue fell 18% sequentially. The quarter marks a severe reversal from the prior quarter's profit, driven by a challenging pricing environment in Gujarat.
For regional cement players like Saurashtra Cement, the September quarter is a test of pricing power against rising costs and monsoon-softened demand. The company's Q2 FY27 results show it failed that test, with revenue plunging and margins collapsing into negative territory.
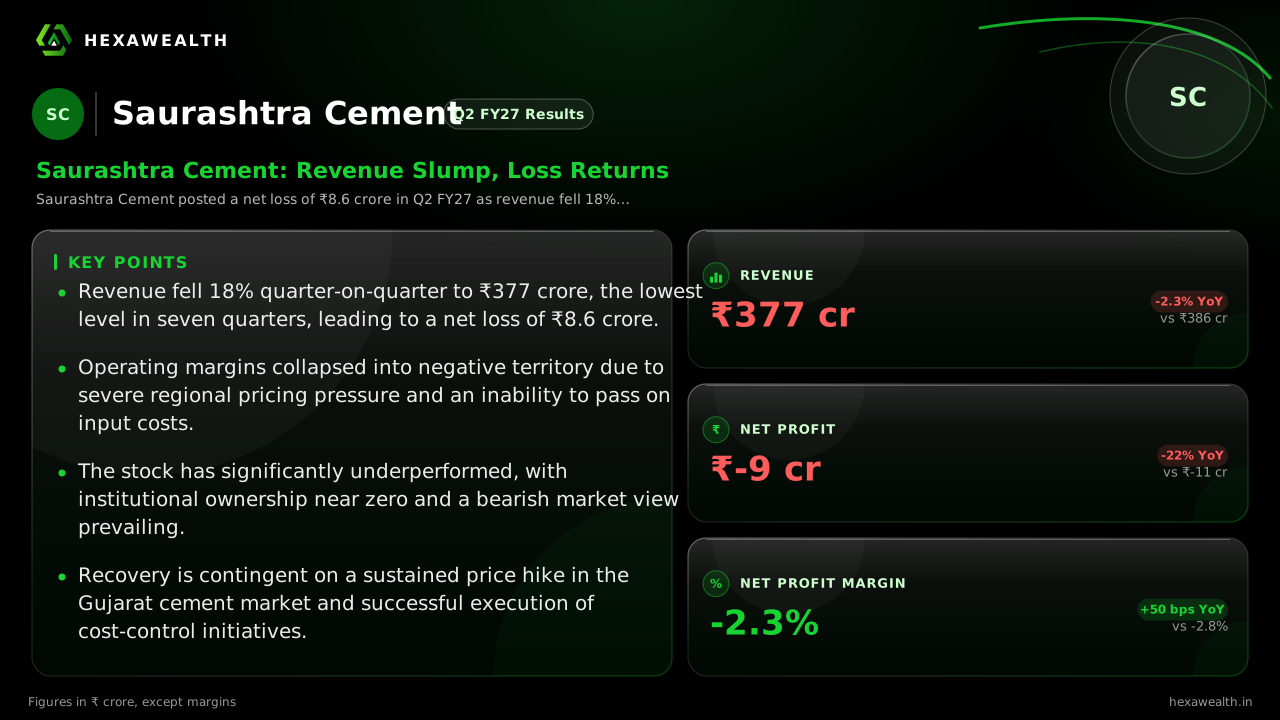
The numbers tell a story of sharp reversal. Revenue fell 18% from the previous quarter to ₹377 crore, the lowest in seven quarters. This pushed the company from a ₹9.1 crore profit in Q1 to a ₹8.6 crore loss. While the year-on-year loss narrowed slightly, the sequential deterioration is stark.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 376.73 | 456.75 |
| Net Profit (₹ Cr) | -8.61 | 9.13 |
| Net Profit Margin | -2.3% | 2.0% |
Why the bottom fell out
The revenue drop was severe, but expenses did not fall in step. MarketsMojo reports the operating margin plunged 754 basis points into negative territory at -2.94%. This points to severe pricing pressure in the Gujarat cement market, where the company operates, coupled with the company's inability to pass on rising input costs.
A sharp 62% quarter-on-quarter drop in other income, a non-operational revenue stream, removed a cushion that had supported profits in better times. While employee and depreciation costs fell slightly, it was not enough to offset the top-line weakness.
The market's unforgiving read
The stock has halved over the past year, reflecting deep investor skepticism. MarketsMojo categorises the stock as a 'Strong Sell' with a score of 3 out of 100, citing negative margins and bearish technicals. Institutional investors show virtually no interest, with FII holdings at a negligible 0.01%.
This sentiment aligns with a tough industry backdrop. A Financial Express report notes that while pan-India cement prices firmed in September, Gujarat remained flat. For a regional player, missing a broad price recovery is a direct hit to profitability.
A narrow path forward
The immediate outlook hinges on a sustained price recovery in its home market. The company is taking steps to control energy costs, having signed an agreement for 14 MW of wind-solar hybrid power. However, with operating cash flow negative for the first half of FY27, the pressure on the balance sheet is mounting.
The quarter reveals the vulnerability of a small-scale operator in a cyclical, cost-intensive industry. Without a meaningful and lasting improvement in cement realisations, the path back to consistent profitability looks steep.
Key Points
- Revenue fell 18% quarter-on-quarter to ₹377 crore, the lowest level in seven quarters, leading to a net loss of ₹8.6 crore.
- Operating margins collapsed into negative territory due to severe regional pricing pressure and an inability to pass on input costs.
- The stock has significantly underperformed, with institutional ownership near zero and a bearish market view prevailing.
- Recovery is contingent on a sustained price hike in the Gujarat cement market and successful execution of cost-control initiatives.
Hexa Perspective
This quarter underscores the operational fragility that comes with limited scale in the cement sector. While the year-on-year comparison shows a marginally smaller loss, the violent quarter-on-quarter swing from profit to loss is the more telling signal.
The investment case now rests on two fragile assumptions: that industry-wide price hikes announced for October will hold in Gujarat, and that the company's renewable power move will materially lower its cost base before further earnings erosion. Both are uncertain, making the stock a high-risk proposition until operating margins return firmly to positive ground.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.