Bedmutha Industries (BEDMUTHA) Q2 FY27 Profit Evaporates Despite 64% Revenue Surge
The wire and copper products maker saw sales soar on strong demand, but surging interest and employee costs wiped out nearly all profitability.
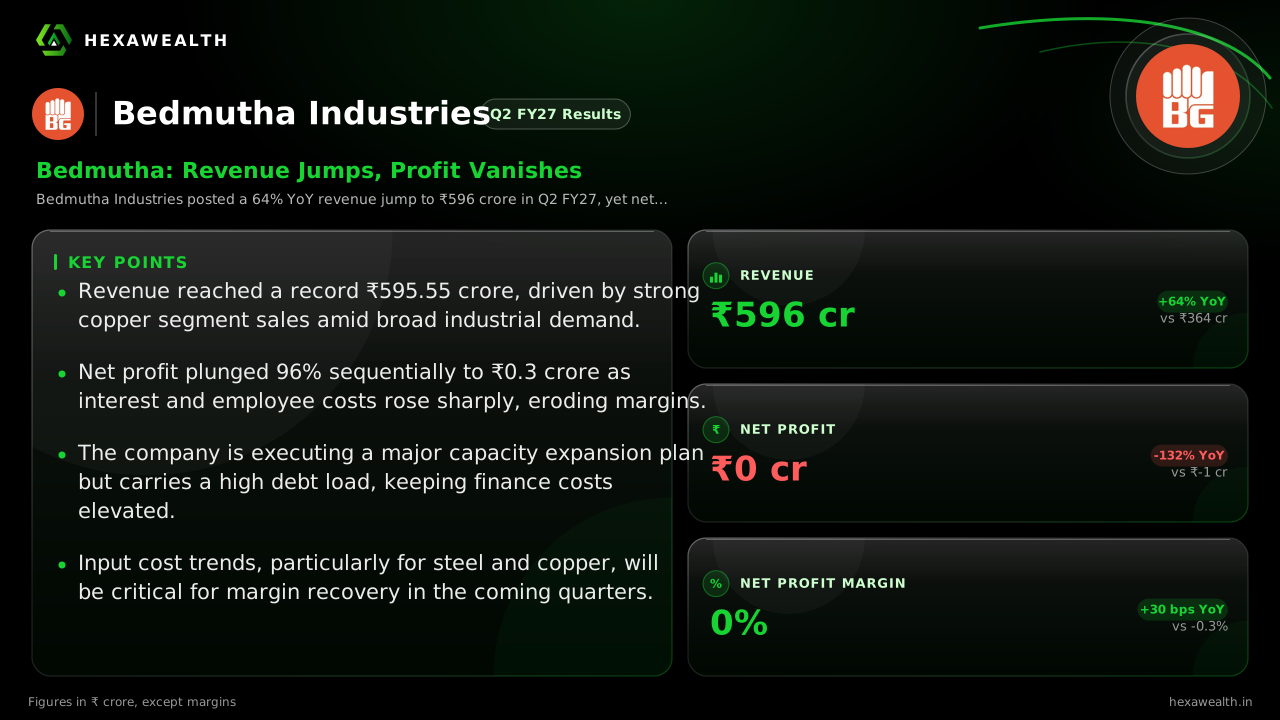
Bedmutha Industries posted a 64% YoY revenue jump to ₹596 crore in Q2 FY27, yet net profit collapsed to just ₹0.3 crore. The quarter reveals a business scaling rapidly but struggling to convert top-line growth into earnings.
For Bedmutha Industries, the September quarter was a story of impressive scale failing to deliver earnings. The company's revenue surged to a new high, riding a wave of infrastructure and industrial demand for its copper and steel wire products. Yet, the bottom line tells a different tale, as a sharp rise in costs consumed nearly all profitability.
Revenue climbed 10% sequentially to ₹595.55 crore, marking a 64% jump from a year ago. However, net profit collapsed to just ₹0.3 crore, down 96% from the previous quarter. The net profit margin was essentially flat at 0.0%, a steep drop from 1.3% in Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 595.55YoY +64% | 541.43 | 363.67 |
| Profit (₹ Cr) | 0.3YoY +132% | 6.92 | -0.93 |
| Net Profit Margin (%) | 0.0YoY +100% | 1.3 | -0.3 |
Where the growth came from
The revenue engine was the copper segment, which contributed ₹452.5 crore, according to a report by Multibagg.ai. This aligns with national data showing India's copper demand rose 12% in FY26, driven by infrastructure and electric vehicles. The steel segment also grew, supported by robust domestic consumption and firming prices for products like TMT bars.
Why profits didn't follow
While sales expanded, costs rose faster. Total expenses grew 11.3% quarter-on-quarter. Two items stood out: interest expense surged 35% to ₹11.6 crore, and employee costs jumped 22% to ₹7.03 crore. The interest charge alone exceeded the aggregate segment profit before finance costs of ₹11.11 crore, as noted by Multibagg.ai.
This pressure is structural. The company's debt-to-equity ratio is high at 1.37, and its interest cover is a thin 1.15. Funding a sanctioned ₹460 crore mega project is likely keeping debt levels elevated, even as working capital efficiency has improved.
The path ahead
Management is betting on capacity expansion to secure future growth. Plans are underway to triple wire rope and value-added copper product capacity by 2027-28, targeting the EV battery supply chain. A new solar plant is also projected to save ₹2.61 crore annually on energy costs.
The immediate challenge is navigating input cost inflation. Steel prices for key products were up 21-29% year-on-year in September, per government data. For profitability to return, Bedmutha must either pass these costs on or find greater operational efficiencies. The market's read is cautious; Univest notes a 'Hold' rating has been in place since February.
Key Points
- Revenue reached a record ₹595.55 crore, driven by strong copper segment sales amid broad industrial demand.
- Net profit plunged 96% sequentially to ₹0.3 crore as interest and employee costs rose sharply, eroding margins.
- The company is executing a major capacity expansion plan but carries a high debt load, keeping finance costs elevated.
- Input cost trends, particularly for steel and copper, will be critical for margin recovery in the coming quarters.
Hexa Perspective
Bedmutha's quarter illustrates the tension between top-line momentum and financial structure. The business is clearly riding a favorable demand cycle, yet its earnings are being neutralized by the cost of funding its own growth. The valuation, at a 442% premium to the industry PE, prices in significant future improvement. That improvement hinges on two factors: the successful ramp-up of higher-margin copper products for EVs, and the company's ability to manage its debt burden as interest rates remain a headwind. Until operating leverage visibly outweighs finance costs, earnings volatility is likely to persist.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.