All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 6 November 20263 min read

Kakatiya Cement (KAKATCEM) Q2 FY27 Loss Narrows on Cement Segment Recovery

The company's net loss reduced sequentially to ₹3.11 crore as cement operations improved, though revenue remained below last year's level.

By Vinayak Gandhi, CFA · Created 6 November 2026

Kakatiya Cement Sugar & Industries narrowed its quarterly net loss to ₹3.11 crore in Q2 FY27, a sequential improvement driven by a smaller loss in its cement division. Revenue rose 27.5% from the June quarter but was still 9.9% lower than a year ago.

For Kakatiya Cement, the September quarter was about stemming the bleed. The multi-business company, running cement, sugar and power operations from Telangana, has been loss-making for over a year. The latest numbers show a step toward operational control, even if a return to profit remains distant.

Revenue for the quarter ended September 2026 came in at ₹22.89 crore. That is a 27.5% sequential jump from the June quarter but still 9.9% below the ₹25.41 crore reported in the same period last year. The net loss narrowed sharply to ₹3.11 crore from ₹6.37 crore in Q1 and ₹11.49 crore a year ago.

Revenue & profit

Revenue (₹ Cr)

Net Profit (₹ Cr)

Net Profit Margin (%)

MetricCurrentQ2 FY27 (Sep 2026)PreviousQ1 FY27 (Jun 2026)
Revenue (₹ Cr)
22.89
17.95
Net Profit (₹ Cr)
-3.11
-6.37
Net Profit Margin (%)
-13.6
-35.5

Cement Leads a Sequential Turn

The improvement was led by the cement division. According to a Multibagg.ai report, the segment’s loss before tax and interest narrowed to ₹0.98 crore from ₹3.90 crore in the June quarter. Cement sales inched up to ₹16.50 crore from ₹16.00 crore. While still below the year-ago level, this operational tightening was the quarter's main driver.

A cleaner year-ago comparison also helped. The reported loss of ₹11.49 crore in Q2 FY26 included an exceptional wheeling charge of ₹7.37 crore. Excluding that, the prior-year loss was ₹4.03 crore, making the latest ₹3.22 crore loss before tax a more modest improvement on an underlying basis.

The Costs That Won't Retreat

Beneath the top line, cost pressures persisted. Power and fuel expense surged to ₹11.43 crore from ₹4.88 crore sequentially, reflecting broader industry inflation. Finance costs, though small, jumped nearly 695% year-on-year to ₹0.33 crore.

The sugar business offered little relief. For the first half, sugar sales were just ₹6.34 crore, less than half the ₹13.21 crore from a year earlier. The power segment reported no revenue for the half-year period.

Management has not provided forward guidance, focusing instead on governance, notes StockFin.ai. The absence of a clear turnaround plan or capex strategy leaves investors with little insight into how the company plans to escape its cycle of losses.

Key Points

  • The net loss narrowed sequentially to ₹3.11 crore, primarily due to a reduced loss in the cement segment.
  • Revenue recovered 27.5% from the June quarter but remained below the year-ago level, reflecting persistent demand challenges.
  • High power and fuel costs and a steep year-on-year rise in finance expenses continued to pressure margins.
  • The sugar division's weak performance and lack of management guidance cloud the near-term outlook.

Hexa Perspective

Kakatiya Cement's quarter shows the fragile nature of a recovery built on cost containment in one segment. The cement division's smaller loss is a positive, but it comes from a low base and against a backdrop of rising industry-wide fuel costs. For the improvement to last, cement sales need to climb sustainably above ₹17 crore per quarter, and the sugar business must find a floor. Without that, the company remains reliant on drawing down reserves, as operating cash flows stay negative. The path to profitability is not yet visible.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
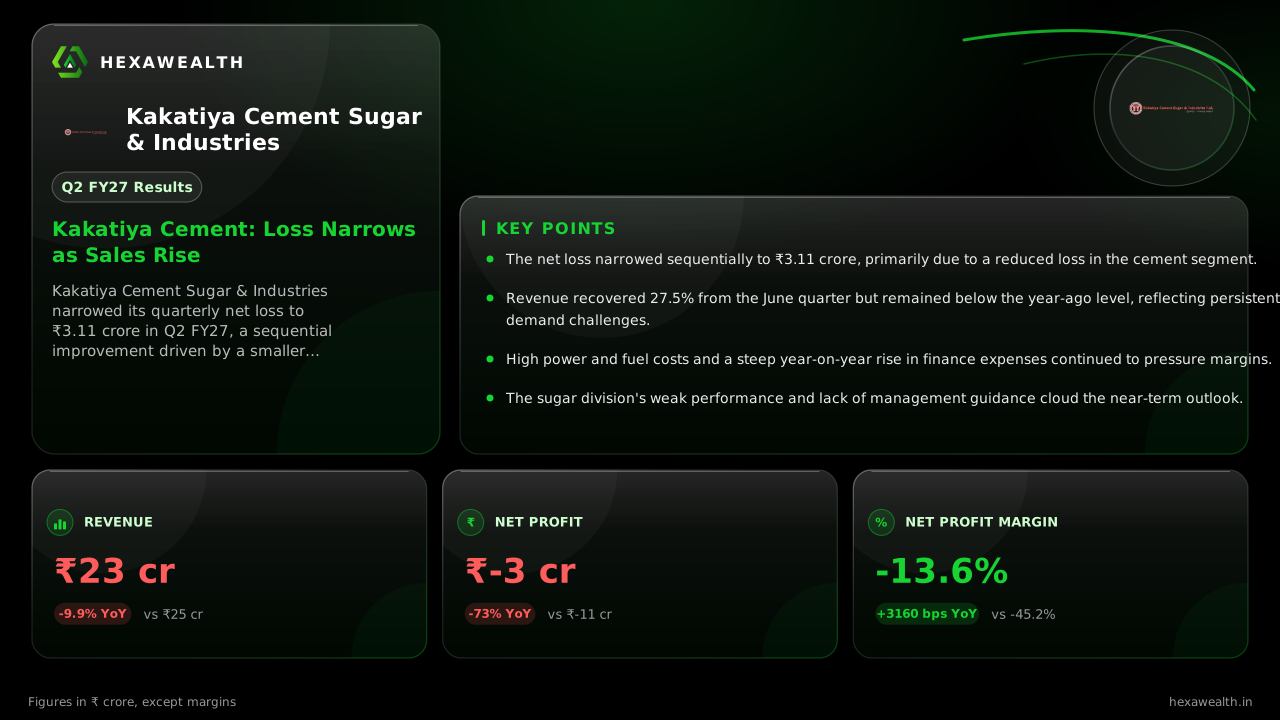
Kakatiya Cement Sugar & Industries (KAKATCEM) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Kakatiya Cement's Q2 FY27 results?
Kakatiya Cement Sugar & Industries reported a net loss of ₹3.11 crore on revenue of ₹22.89 crore for the quarter ended September 2026. This was an improvement from a ₹6.37 crore loss in the prior quarter, but revenue was 9.9% lower than the ₹25.41 crore reported in the same quarter last year.
Why did Kakatiya Cement's net loss narrow in Q2 FY27?
The net loss narrowed primarily due to a significant improvement in the cement segment. According to Multibagg.ai, the cement division's loss before tax and interest reduced to ₹0.98 crore from ₹3.90 crore in the June 2026 quarter, driving the overall sequential improvement.
What was Kakatiya Cement's revenue in Q2 FY27?
Kakatiya Cement's revenue from operations was ₹22.89 crore for the September 2026 quarter. This represents a 27.5% increase from the previous quarter but a 9.9% decrease compared to the ₹25.41 crore earned in the September 2025 quarter.
How did Kakatiya Cement's cement division perform in Q2 FY27?
The cement division showed marked improvement. A Multibagg.ai report states its loss before tax and interest narrowed to ₹0.98 crore from ₹3.90 crore in the prior quarter. Sales rose slightly to ₹16.50 crore but remained below the ₹17.90 crore from a year ago.
Why did Kakatiya Cement's interest expense surge nearly 695% year-on-year?
Finance costs rose to ₹0.33 crore in Q2 FY27 from just ₹0.04 crore in Q2 FY26, a increase of nearly 695%. The base was unusually low a year ago, and the company's reported half-year finance costs also increased significantly, indicating higher borrowing costs or changed financial arrangements.
What was the performance of Kakatiya Cement's sugar and power divisions?
The sugar business remained weak. For the first half of FY27, sugar sales were ₹6.34 crore, down sharply from ₹13.21 crore a year earlier. The power segment reported no revenue for the half-year period, continuing its non-operational status.
What guidance did Kakatiya Cement management provide for FY27?
Management has not provided forward-looking operational guidance. An analysis by StockFin.ai notes the recent commentary focuses on governance and dividend decisions rather than future business expectations or a turnaround strategy.
What is Kakatiya Cement's current debt profile?
The company maintains a conservative leverage position. StockFin.ai reports a debt-to-equity ratio of 0.11. However, operating cash flow was negative ₹21 crore as of March 2026, indicating the company is funding operations by drawing down reserves.
Did Kakatiya Cement's Q2 FY27 results beat analyst estimates?
No verified analyst estimates for Kakatiya Cement's Q2 FY27 were publicly available, as noted in previews from Univest and Multibagg.ai. Therefore, the results cannot be judged against a consensus forecast.
How did Kakatiya Cement's stock price react to the Q2 results?
Specific intraday reaction data is not available in the research. However, the stock has been under pressure, with a one-year return of -30.5% as of November 5, 2026, reflecting the company's prolonged period of losses.
Kakatiya Cement Q2 profit?
Kakatiya Cement reported a net loss of ₹3.11 crore for the quarter ended September 2026 (Q2 FY27). This was an improvement from a loss of ₹6.37 crore in the previous quarter and a loss of ₹11.49 crore in the same quarter last year.
Kakatiya Cement Q2 FY27 results?
Kakatiya Cement's Q2 FY27 results, for the period ending September 2026, showed revenue of ₹22.89 crore and a net loss of ₹3.11 crore. The loss narrowed sequentially due to improvement in the cement segment, though revenue was below the year-ago level.