Vinsys IT Services (VINSYS) Q2 FY27 Revenue Collapses 81% as Business Model Shifts
Vinsys IT Services reported an 81% plunge in Q2 FY27 revenue and a net loss, a dramatic reversal from its recent growth trajectory.
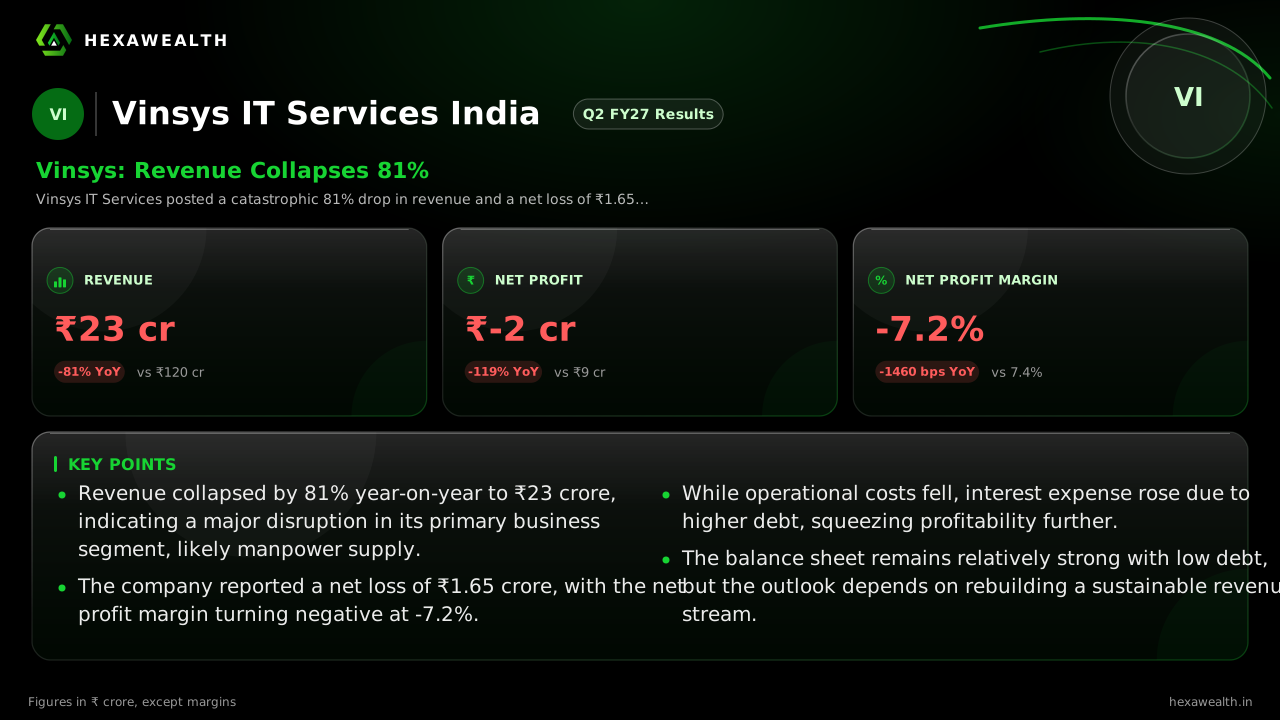
Vinsys IT Services posted a catastrophic 81% drop in revenue and a net loss of ₹1.65 crore for Q2 FY27. The collapse follows a major shift in its business segments and a challenging IT services environment.
For Vinsys IT Services, a company that had delivered consistent revenue growth, the September quarter brought a sudden stop. The IT training and services provider saw its core business evaporate, leading to a catastrophic 81% year-on-year revenue drop and a slide into loss.
The numbers tell a story of near-total business disruption. Revenue fell to just ₹23 crore from ₹120 crore a year ago, while net profit swung to a loss of ₹1.65 crore from a profit of ₹8.84 crore. This pushed the net profit margin to -7.2%, a staggering 1,460 basis point decline.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 23.01YoY -81% | 120.01 |
| Profit (₹ Cr) | -1.65YoY -119% | 8.84 |
| Net Profit Margin (%) | -7.2YoY -197% | 7.4 |
The cause of the collapse
Research from Clartha and Morningstar indicates the company operates two main segments: IT Services and Manpower Supply. The catastrophic revenue decline suggests a major client contract in the manpower supply segment may have ended or been drastically scaled back. This segment previously contributed the majority of revenue.
While employee and depreciation costs fell in line with lower activity, interest expense rose 15% year-on-year. Data from Sharpely.in shows long-term debt increased significantly in FY26, creating a fixed financial burden that now weighs heavily on a shrunken revenue base.
A strained but stable balance sheet
Despite the operational shock, the company's balance sheet provides some buffer. The debt-to-equity ratio stands at 0.32, which is manageable, and the current ratio is a strong 5.87. This financial stability may give management time to execute a turnaround, but it does not offset the core business challenge.
The broader IT services sector, as noted by Ventura Securities, faces weak growth and pricing pressure as clients restructure contracts around AI automation. This environment makes a rapid recovery in Vinsys's traditional service lines unlikely.
Key Points
- Revenue collapsed by 81% year-on-year to ₹23 crore, indicating a major disruption in its primary business segment, likely manpower supply.
- The company reported a net loss of ₹1.65 crore, with the net profit margin turning negative at -7.2%.
- While operational costs fell, interest expense rose due to higher debt, squeezing profitability further.
- The balance sheet remains relatively strong with low debt, but the outlook depends on rebuilding a sustainable revenue stream.
Hexa Perspective
The quarter represents a fundamental reset, not a cyclical dip. Vinsys's business appears to have shifted from a high-revenue, lower-margin manpower model to a much smaller core. The path forward hinges on whether its IT training and certification services can scale to fill the void, leveraging a corporate training market Ken Research projects to grow at 13% annually. With the stock still trading at a 120% premium to the industry PE, investors are pricing in a recovery that is far from certain. The next few quarters will test if this is a temporary dislocation or a permanent downsizing.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.