Spinaroo Commercial (SPINAROO) Q2 FY27 Profit Recovers from a Low Base as Sales Slip
The textile trader's net profit more than doubled sequentially but remains sharply lower than a year ago, with revenue contracting amid a tough market.
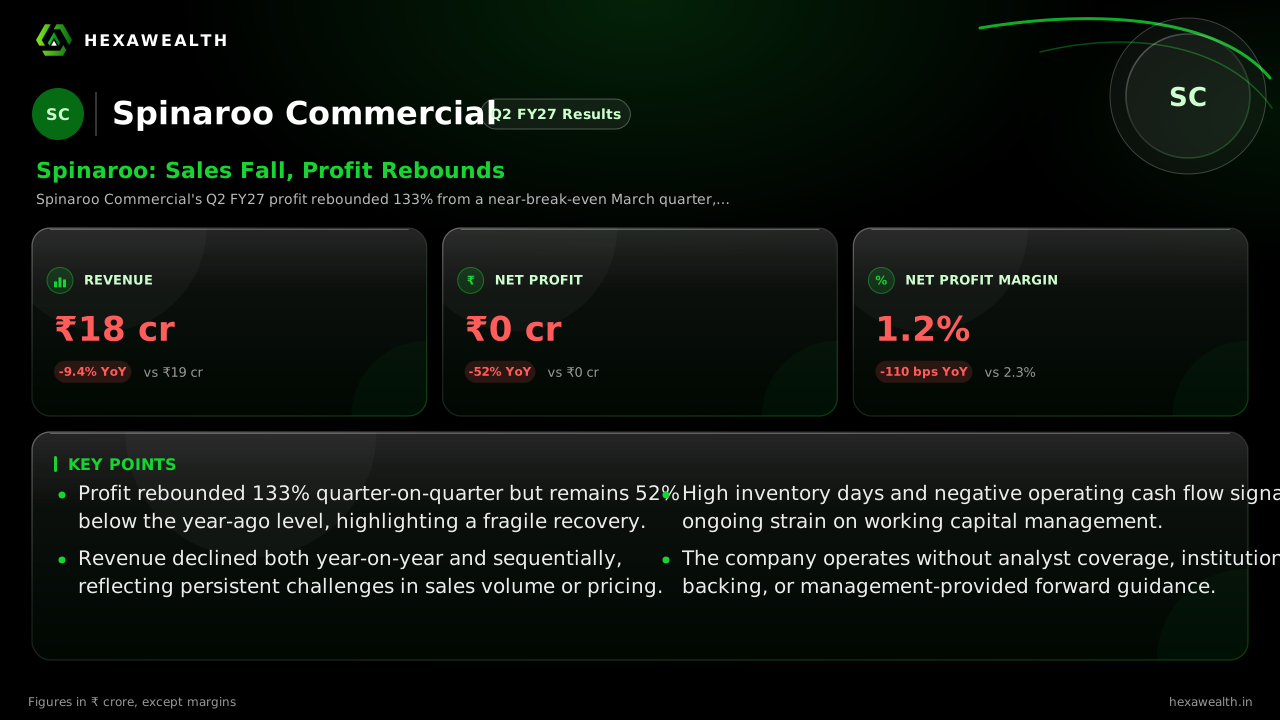
Spinaroo Commercial's Q2 FY27 profit rebounded 133% from a near-break-even March quarter, but revenue fell nearly 10% year-on-year. The recovery is fragile, built on a low base and overshadowed by a steep decline in sales.
For a textile trader like Spinaroo Commercial, volume and pricing are everything. The September quarter saw both retreat, leaving a profit recovery that speaks more to how bad things were than how good they are now.
Revenue fell 9.4% from a year ago to ₹17.55 crore, extending a slide from the prior quarter. Net profit, however, jumped 133% sequentially to ₹0.21 crore. This rebound comes off an exceptionally weak base of just ₹0.09 crore in Q4 FY26, a quarter described by HexaWealth as a "near-break-even" period due to a severe margin squeeze.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 21.02
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 18.30
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 19.37
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 19.90
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 17.55
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 0.61
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 0.82
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.44
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 0.09
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.21
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 21.02
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 18.30
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 19.37
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 19.90
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 17.55
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 0.61
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 0.82
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.44
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 0.09
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.21
Net Profit Margin
- Net Profit Margin, Q2 FY25 (Sep 2024): 2.9%
- Net Profit Margin, Q4 FY25 (Mar 2025): 4.5%
- Net Profit Margin, Q2 FY26 (Sep 2025): 2.3%
- Net Profit Margin, Q4 FY26 (Mar 2026): 0.5%
- Net Profit Margin, Q2 FY27 (Sep 2026): 1.2%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 17.55 | 19.90 |
| Profit (₹ Cr) | 0.21 | 0.09 |
| Net Profit Margin | 1.2% | 0.5% |
A Recovery Built on Expense Control
The sequential profit jump was driven by cost-cutting, not sales growth. Total expenses fell 12.7% from the March quarter. Yet, this control is being offset by other pressures. Interest costs are up 56% year-on-year, and depreciation nearly doubled from the prior quarter.
A report from StockFin.ai notes the company has provided no forward guidance, increasing uncertainty. The broader textile trading environment offers little relief. While yarn production is strong, apparel demand is weak, and input costs are volatile.
The Cash Flow Conundrum
Even when profit ticks up, cash remains a concern. Data from mywealthgrid.com shows operating cash flow was deeply negative at ₹-6.77 crore for the full year ended March 2026. This is tied to a working capital cycle that has stretched to 193 days, with inventory sitting for nearly half a year.
Live Chart
· SPINAROO
(BSE)
ISIN: INE10XX01012
The company carries little analyst coverage and no institutional investor interest, according to StockFin.ai. Its valuation, at a P/E of 61.3, trades at a 366% premium to its industry, a stark disconnect from its stagnant financial profile.
Key Points
- Profit rebounded 133% quarter-on-quarter but remains 52% below the year-ago level, highlighting a fragile recovery.
- Revenue declined both year-on-year and sequentially, reflecting persistent challenges in sales volume or pricing.
- High inventory days and negative operating cash flow signal ongoing strain on working capital management.
- The company operates without analyst coverage, institutional backing, or management-provided forward guidance.
Hexa Perspective
This quarter's profit bounce is a correction from an unsustainably low point, not a sign of operational turnaround. The core issue is a top line that has been stagnant or declining for years, now compounded by a severe working capital drag. For the recovery to have legs, Spinaroo needs to demonstrate it can grow sales in a tough market and convert those sales into cash. Until then, the premium valuation appears anchored more to its small float than to its business fundamentals.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.