SoftTech Engineers (SOFTTECH) Q2 FY27 Profit Crashes 82% as Costs Outpace Revenue
The AEC software firm's Q2 net profit fell sharply despite higher sales, squeezed by a jump in depreciation and other expenses.
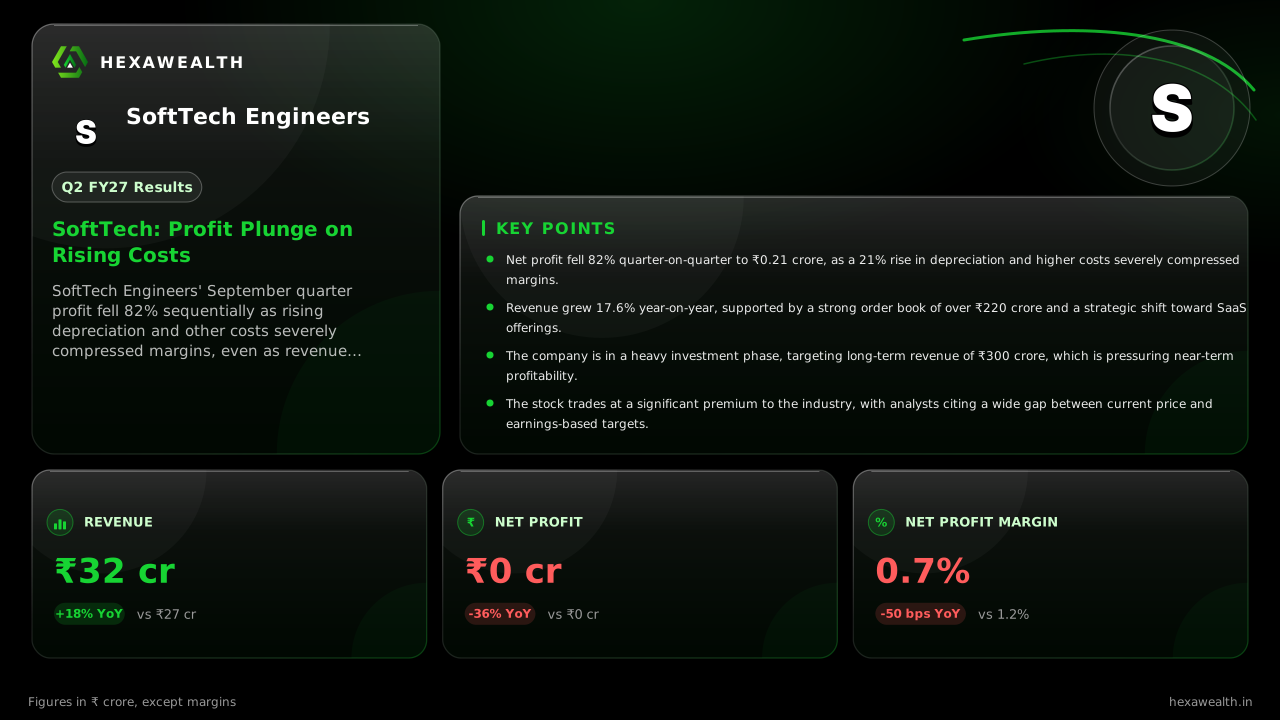
SoftTech Engineers' September quarter profit fell 82% sequentially as rising depreciation and other costs severely compressed margins, even as revenue grew 18% year-on-year.
For a company building its future on digital platforms, SoftTech Engineers' latest quarter shows the heavy cost of that transition. Revenue grew, but profit collapsed as the company absorbed the expense of new capacity and investments.
Consolidated revenue for the September quarter was ₹31.53 crore, up 17.6% from a year earlier. Net profit, however, fell to just ₹0.21 crore, down 81.9% from the June quarter. The net profit margin shrank to 0.7%, down 280 basis points sequentially.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 31.53YoY +18% | 33.28 | 26.81 |
| Profit (₹ Cr) | 0.21YoY -36% | 1.16 | 0.33 |
| Net Profit Margin (%) | 0.7YoY -42% | 3.5 | 1.2 |
Why the bottom line vanished
A 21% year-on-year jump in depreciation, to ₹6.85 crore, was a primary driver. According to SectorAlpha, this reflects a multi-year capital spending program where investment has run at twice the depreciation rate. Total expenses grew faster than revenue, rising 18.1% year-on-year.
Management commentary, reported by SectorAlpha, points to a strategic build-out. The company is targeting ₹300 crore revenue within three years at a 25-30% operating margin. For now, spending to reach that goal is pressuring near-term profits.
The growth engine remains intact
Despite the profit squeeze, the business pipeline is robust. FlashFinance reported a confirmed order book of ₹220.41 crore, about 166% of trailing twelve-month revenue. A recent ₹92.95 crore win from JNPA for an AI Digital Twin project, noted by SAHI, marks a strategic entry into the port sector.
The shift to higher-margin SaaS revenue continues. StockFin.ai reported that SaaS revenue grew 55.6% year-on-year in the prior quarter, contributing 31% of total revenue. This supports the long-term margin story even as current profitability is muted.
A valuation waiting for earnings
Analyst sentiment remains cautious on the stock's rich valuation. Univest.in notes a consensus price target of ₹129 for 2027, well below recent trading levels, reflecting concerns that earnings need time to catch up with the price. The stock's P/E of 63.5 trades at a 230% premium to the industry.
Key Points
- Net profit fell 82% quarter-on-quarter to ₹0.21 crore, as a 21% rise in depreciation and higher costs severely compressed margins.
- Revenue grew 17.6% year-on-year, supported by a strong order book of over ₹220 crore and a strategic shift toward SaaS offerings.
- The company is in a heavy investment phase, targeting long-term revenue of ₹300 crore, which is pressuring near-term profitability.
- The stock trades at a significant premium to the industry, with analysts citing a wide gap between current price and earnings-based targets.
Hexa Perspective
This quarter lays bare the tension in SoftTech's story. The top-line growth and order book confirm demand for its digital transformation tools in construction and governance. Yet, the near-complete evaporation of profit shows how costly it is to build the platform and capacity for that future.
The next few quarters will test whether rising SaaS revenue can start to offset the depreciation drag and lift margins toward management's 25-30% goal. Until then, the stock's premium valuation relies entirely on the promise of that future profitability, not the current earnings delivery.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.