Sampark (SILL) Q2 FY27 Logistics Profit Dips Despite Strong Revenue Growth
The logistics firm posted a 36.5% jump in Q2 FY27 revenue but saw profits contract sequentially as a key business model shift absorbed costs.
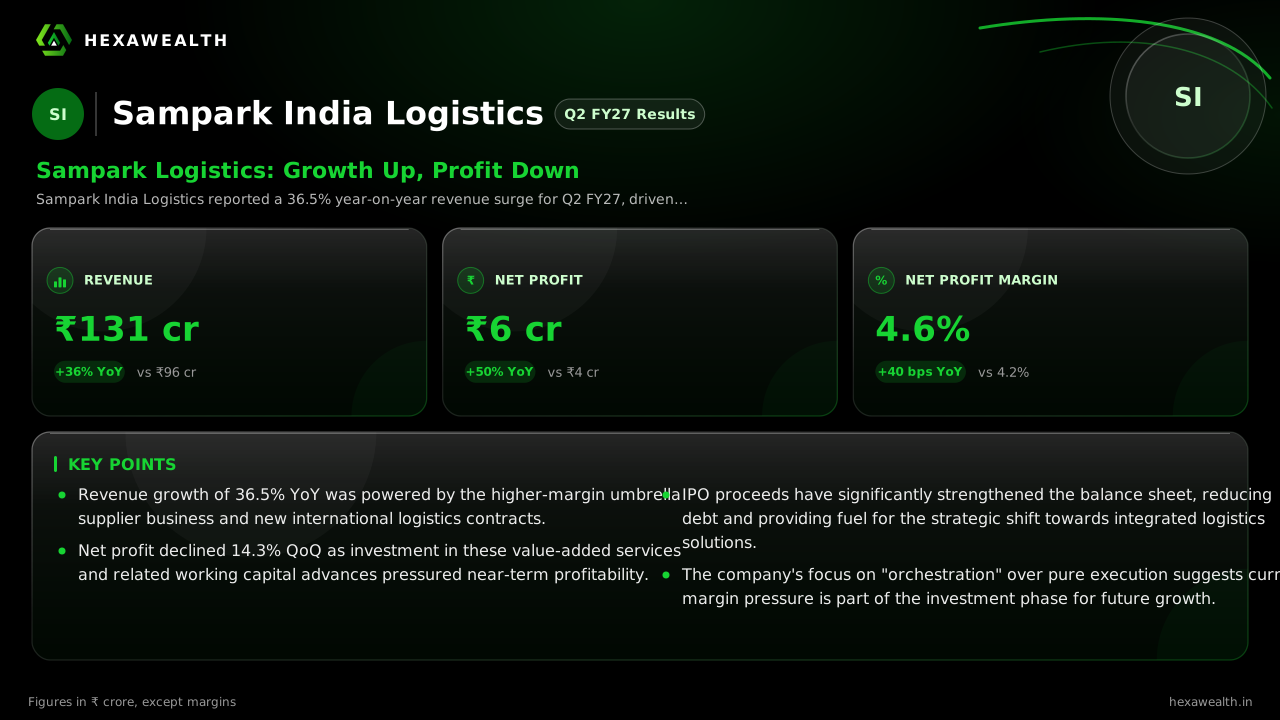
Sampark India Logistics reported a 36.5% year-on-year revenue surge for Q2 FY27, driven by its umbrella supplier and international business. However, net profit fell 14.3% from the previous quarter as investment in higher-value services squeezed near-term margins.
For Sampark India Logistics, the first half as a listed company is about proving it can move beyond freight. The September quarter shows it is succeeding, with revenue surging 36.5% from a year ago. Yet the path to higher-value services is not free, as a sequential profit dip reveals the cost of that transition.
The numbers tell a story of strong annual growth but near-term pressure. Revenue reached ₹131 crore, while net profit stood at ₹6 crore. Compared to last quarter, sales grew 3.1% but profit fell 14.3%. The net profit margin contracted by 90 basis points sequentially to 4.6%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 94.0
- Revenue (₹ Cr), Q2 FY26: 96.0
- Revenue (₹ Cr), Q4 FY26: 127.0
- Revenue (₹ Cr), Q2 FY27: 131.0
- Profit (₹ Cr), Q4 FY25: 4.0
- Profit (₹ Cr), Q2 FY26: 4.0
- Profit (₹ Cr), Q4 FY26: 7.0
- Profit (₹ Cr), Q2 FY27: 6.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 94.0
- Revenue (₹ Cr), Q2 FY26: 96.0
- Revenue (₹ Cr), Q4 FY26: 127.0
- Revenue (₹ Cr), Q2 FY27: 131.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY25: 4.0
- Profit (₹ Cr), Q2 FY26: 4.0
- Profit (₹ Cr), Q4 FY26: 7.0
- Profit (₹ Cr), Q2 FY27: 6.0
Net Profit Margin
- Net Profit Margin, Q4 FY25: 4.3%
- Net Profit Margin, Q2 FY26: 4.2%
- Net Profit Margin, Q4 FY26: 5.5%
- Net Profit Margin, Q2 FY27: 4.6%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 131.0YoY +36% | 96.0 |
| Profit (₹ Cr) | 6.0YoY +50% | 4.0 |
| Net Profit Margin | 4.6%YoY +9.5% | 4.2% |
Why Profit Slipped as Sales Rose
The driver was a strategic shift, not just more freight. According to The Machine Maker, growth came from the umbrella supplier business and deeper OEM engagement. A major win was onboarding a US semiconductor equipment maker for international supply chain services.
These integrated solutions offer higher realisations than standalone freight. But they also require upfront investment and working capital advances. This contributed to the sequential margin squeeze, even as operational efficiencies offset external cost pressures like fuel surcharges.
The Balance Sheet Reset
A key subplot is the deployment of IPO proceeds. The ₹27.22 crore raise has been fully utilized, with ₹19.73 crore earmarked for working capital, reports MCapital. This cut short-term borrowings sharply and lifted net worth to ₹77.69 crore.
Live Chart
· SILL
(BSE)
ISIN: INE147701010
The stronger balance sheet funds the shift to value-added services. It also explains why returns like RoE, at 16%, are currently moderated by the expanded capital base, as noted in the company's commentary.
How Long Does the Squeeze Last?
Management, cited by The Machine Maker, is focused on moving up the value chain to "umbrella supply chain orchestration." The payoff is in higher margins over time, but the costs are incurred now.
The setup of a clean-room warehouse in Noida for the semiconductor vertical is a case in point. These investments are necessary to secure long-term contracts and higher wallet share from existing clients. The margin pressure is likely a feature of this scaling phase, not a bug.
Key Points
- Revenue growth of 36.5% YoY was powered by the higher-margin umbrella supplier business and new international logistics contracts.
- Net profit declined 14.3% QoQ as investment in these value-added services and related working capital advances pressured near-term profitability.
- IPO proceeds have significantly strengthened the balance sheet, reducing debt and providing fuel for the strategic shift towards integrated logistics solutions.
- The company's focus on "orchestration" over pure execution suggests current margin pressure is part of the investment phase for future growth.
Hexa Perspective
The quarter frames Sampark's challenge: it is successfully pivoting its business model, but the rewards are lagging the costs. The 90 bps QoQ margin contraction is the price of funding growth in higher-value segments like international umbrella supply.
With a de-levered balance sheet post-IPO, the company has the capital to endure this squeeze. The key is whether the new contracts and facilities, like the Noida clean-room, can scale quickly enough to lift overall margins back towards the TTM average of 4.7%. For now, growth is clear, but profitability is in transition.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.