Sampark India Logistics (SILL) Q4 FY26 Profit Surges 75% on Strong Volume Growth
Sampark India Logistics posted a 75% jump in quarterly net profit as revenue grew 35%, with operating leverage and IPO proceeds driving margin expansion.
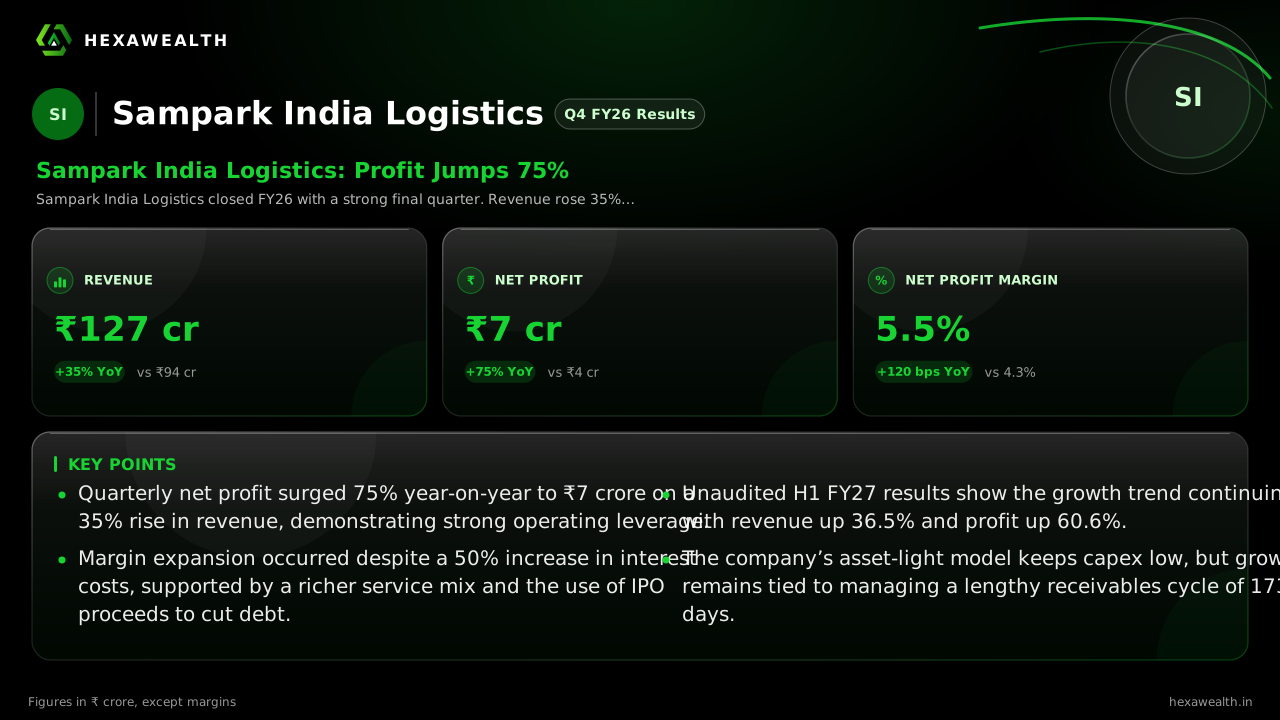
Sampark India Logistics closed FY26 with a strong final quarter. Revenue rose 35% year-on-year to ₹127 crore, while net profit surged 75% to ₹7 crore, lifting the net profit margin to 5.5%.
For asset-light logistics operators, growth is a double-edged sword. It brings more business but also ties up cash in receivables, often faster than profits can follow. Sampark India Logistics’s strong final quarter of FY26, however, showed the upside when volume growth meets improved financial footing.
Revenue for the March quarter reached ₹127 crore, up 35% from a year ago and 32% from the September quarter. Net profit jumped 75% year-on-year to ₹7 crore, with the net profit margin expanding 130 basis points sequentially to 5.5%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 94.0
- Revenue (₹ Cr), Q2 FY26: 96.0
- Revenue (₹ Cr), Q4 FY26: 127.0
- Net Profit (₹ Cr), Q4 FY25: 4.0
- Net Profit (₹ Cr), Q2 FY26: 4.0
- Net Profit (₹ Cr), Q4 FY26: 7.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 94.0
- Revenue (₹ Cr), Q2 FY26: 96.0
- Revenue (₹ Cr), Q4 FY26: 127.0
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Q4 FY25: 4.0
- Net Profit (₹ Cr), Q2 FY26: 4.0
- Net Profit (₹ Cr), Q4 FY26: 7.0
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY25: 4.3
- Net Profit Margin (%), Q2 FY26: 4.2
- Net Profit Margin (%), Q4 FY26: 5.5
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 127.0YoY +35% | 94.0 |
| Net Profit (₹ Cr) | 7.0YoY +75% | 4.0 |
| Net Profit Margin (%) | 5.5YoY +28% | 4.3 |
Why margins expanded despite higher costs
The profit surge was driven by operating leverage, not one-offs. Operating profit grew faster than revenue, lifting the margin. According to data from MarketsMojo, the company reported no exceptional items in FY26, unlike the prior year.
Higher interest costs, which rose 50%, were more than offset by this operating efficiency. The gains were supported by a shift towards higher-margin services like its umbrella supplier business and international logistics, as noted in its annual report.
The IPO effect on the balance sheet
A key change arrived with the company’s 2026 IPO. The ₹27 crore raised was primarily earmarked for working capital. A report from mcapital.in notes the proceeds were fully utilized, cutting short-term borrowings and lifting net worth sharply by the half-year ended September 2026.
Live Chart
· SILL
(BSE)
ISIN: INE147701010
This deleveraging reduces the drag from interest costs going forward. It also provides the fuel to fund the receivables cycle, which at 173 days remains the business's primary cash constraint.
The outlook embedded in H1 FY27
Management’s guidance is implicit in the unaudited results for the first half of the new fiscal year. The company reported H1 FY27 revenue of ₹131 crore, up 36.5% year-on-year, and net profit of ₹6.35 crore, up 60.6%, according to a BSE filing cited by MarketsMojo.
This suggests the growth momentum is sustaining. The company is also investing in capacity, setting up specialized warehouses in Noida and Ambala to support its umbrella supplier vertical, as per a business update from The Machine Maker.
Key Points
- Quarterly net profit surged 75% year-on-year to ₹7 crore on a 35% rise in revenue, demonstrating strong operating leverage.
- Margin expansion occurred despite a 50% increase in interest costs, supported by a richer service mix and the use of IPO proceeds to cut debt.
- Unaudited H1 FY27 results show the growth trend continuing, with revenue up 36.5% and profit up 60.6%.
- The company’s asset-light model keeps capex low, but growth remains tied to managing a lengthy receivables cycle of 173 days.
Hexa Perspective
Sampark’s quarter shows what happens when an asset-light logistics player gains financial flexibility. The IPO proceeds have temporarily eased the working capital bind, allowing operating leverage to shine through in the profit numbers.
The sustainability of this performance hinges on two factors: maintaining the discipline in receivables management as sales grow, and successfully scaling the newer, higher-margin service lines like umbrella supply. The H1 FY27 numbers suggest the trajectory is intact, but the long collection cycle remains an inherent risk to cash flow in any downturn.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.