Sical Logistics (SICALLOG) Q2 FY27 Profit Plunges Despite 17% Revenue Growth
The logistics firm's Q2 FY27 profit swung to a loss of ₹11.2 crore as high interest and employee costs overwhelmed revenue growth.
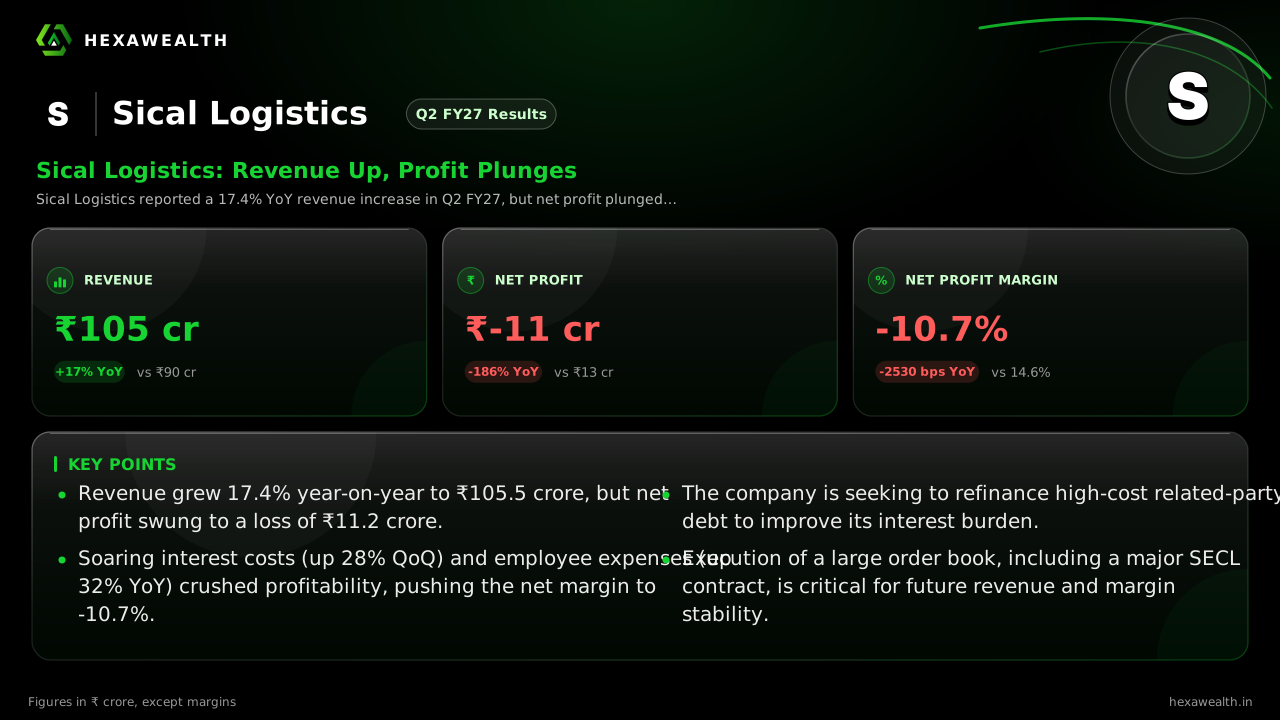
Sical Logistics reported a 17.4% YoY revenue increase in Q2 FY27, but net profit plunged to a loss of ₹11.2 crore. The sharp decline was driven by a steep rise in interest and employee costs, overshadowing operational gains.
For Sical Logistics, the September quarter was a story of growth that never reached the bottom line. Revenue climbed 17% from a year earlier, but a steep rise in interest and employee costs pushed the company into a loss, highlighting the fragile nature of its turnaround.
The numbers show a clear disconnect. Revenue for Q2 FY27 stood at ₹105.5 crore, up from ₹89.8 crore a year ago. Yet, net profit swung to a loss of ₹11.2 crore from a profit of ₹13.1 crore. The net profit margin collapsed to -10.7%, down sharply from 14.6% a year earlier.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 89.81
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 93.16
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 105.17
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 132.58
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 105.46
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 13.11
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 47.94
- Profit (₹ Cr), Q4 FY26 (Mar 2026): -8.78
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 21.24
- Profit (₹ Cr), Q2 FY27 (Sep 2026): -11.24
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 89.81
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 93.16
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 105.17
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 132.58
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 105.46
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 13.11
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 47.94
- Profit (₹ Cr), Q4 FY26 (Mar 2026): -8.78
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 21.24
- Profit (₹ Cr), Q2 FY27 (Sep 2026): -11.24
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26 (Sep 2025): 14.6
- Net Profit Margin (%), Q3 FY26 (Dec 2025): 51.5
- Net Profit Margin (%), Q4 FY26 (Mar 2026): -8.3
- Net Profit Margin (%), Q1 FY27 (Jun 2026): 16.0
- Net Profit Margin (%), Q2 FY27 (Sep 2026): -10.7
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 105.46 | 132.58 |
| Profit (₹ Cr) | -11.24 | 21.24 |
| Net Profit Margin (%) | -10.7 | 16.0 |
The Costs That Overwhelmed Growth
Two line items explain the profit plunge. Interest expense jumped 28% sequentially to ₹16.3 crore. According to a report by Zennivesh, this is tied to ₹184 crore of group loans at 12.5%, which cost about ₹23 crore annually.
Employee costs also surged 32% year-on-year to ₹8 crore. This reflects the operational ramp-up for new mining contracts, but it squeezed margins before revenue could fully materialize.
A High Base and a Low Quarter
The profit collapse looks starker against last year's numbers. In Q2 FY26, other income was an unusually high ₹29.6 crore, flattering the bottom line. This quarter, it fell to just ₹7 crore.
Live Chart
· SICALLOG
(BSE)
ISIN: INE075B01020
Sequentially, revenue also dropped 20.5% from a strong Q1. This suggests some volatility in contract execution or seasonality as new projects like the South Eastern Coalfields (SECL) contract begin mobilisation.
The Execution Hurdle Ahead
The company's future hinges on executing its large order book, which scanx.trade reports stands at ₹534.7 crore. However, profitability depends on controlling the financial overhead.
Management is seeking shareholder approval to modify loan terms with a group entity, Kanpur Logistics Park, aiming to cut the interest rate from 12.5% to 10%, as per a filing highlighted by News.tulsian.ai. This could provide some relief, but the debt burden remains substantial with a debt-to-equity ratio of 3.3.
Key Points
- Revenue grew 17.4% year-on-year to ₹105.5 crore, but net profit swung to a loss of ₹11.2 crore.
- Soaring interest costs (up 28% QoQ) and employee expenses (up 32% YoY) crushed profitability, pushing the net margin to -10.7%.
- The company is seeking to refinance high-cost related-party debt to improve its interest burden.
- Execution of a large order book, including a major SECL contract, is critical for future revenue and margin stability.
Hexa Perspective
This quarter underscores that Sical's operational recovery is still vulnerable to its capital structure. Revenue growth is evident, but it is being consumed by legacy financial costs. The path to sustainable profit requires two concurrent wins: flawless execution of new contracts to boost operating cash flow, and successful deleveraging to reduce the interest drag.
The market is pricing in the execution story, with the stock trading at a significant discount to the industry PE. For that discount to narrow, the company must demonstrate that core profits can consistently cover its finance costs, moving beyond a balance-sheet repair narrative to a genuine earnings story.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.