Shri Bajrang Alliance (SHBAJRG) Q2 FY27 Profit Lags Behind 57% Revenue Surge
The steel and frozen foods company posted a 57% jump in quarterly revenue, but profit growth was muted as costs rose faster than sales.
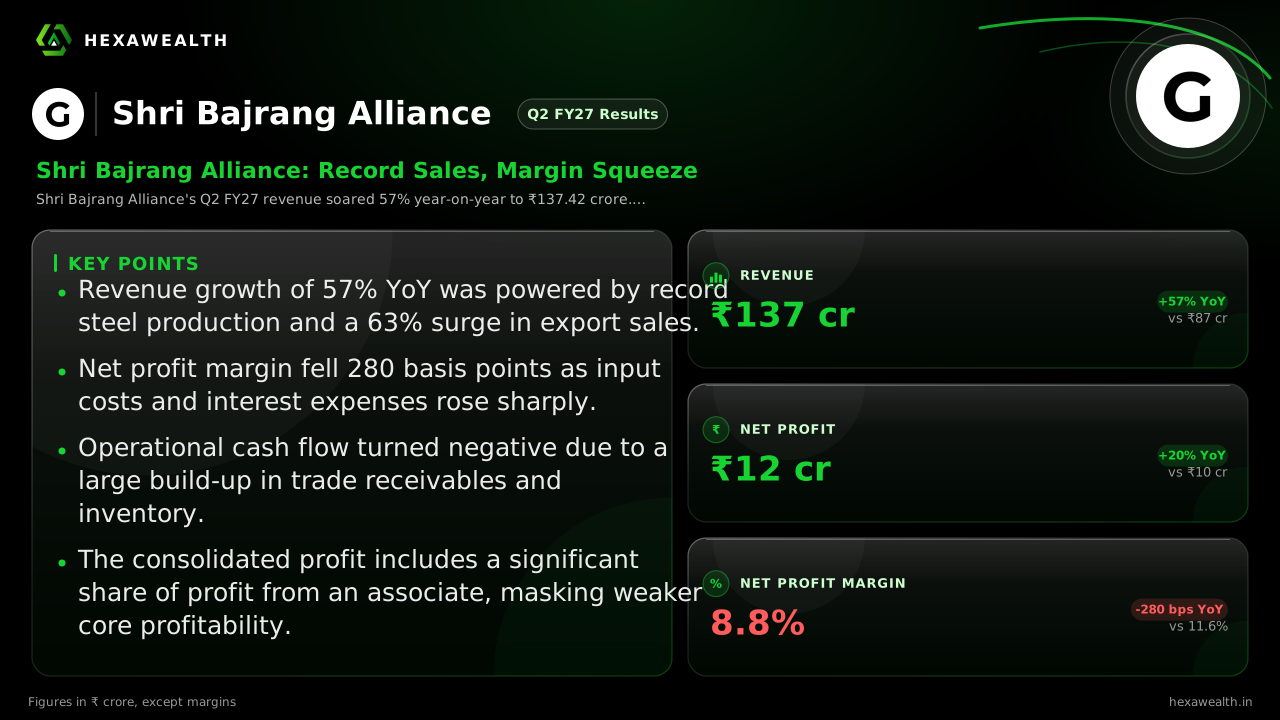
Shri Bajrang Alliance's Q2 FY27 revenue soared 57% year-on-year to ₹137.42 crore. However, net profit grew only 20%, as higher material costs and interest expenses compressed margins, revealing a cash flow strain beneath the headline growth.
For Shri Bajrang Alliance, a quarter of record steel production and surging exports delivered a top-line boom. Yet the profit story was more muted, as the costs of that rapid growth bit into margins and cash flow.
Revenue for the September quarter leapt 57% year-on-year to ₹137.42 crore, continuing a strong sequential climb. Net profit grew 20% to ₹12.14 crore, but the net profit margin contracted by 280 basis points to 8.8%. The gap between revenue and profit growth points to significant cost pressures.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 137.42YoY +57% | 104.98 | 87.40 |
| Profit (₹ Cr) | 12.14YoY +20% | 9.65 | 10.11 |
| Net Profit Margin (%) | 8.8YoY -24% | 9.2 | 11.6 |
The costs that grew faster than sales
The margin squeeze was driven by two main factors. First, the cost of materials consumed and purchases of stock-in-trade rose sharply, as reported by ScanX.trade. This suggests the revenue surge was partly fueled by higher-cost trading activity alongside manufacturing.
Second, interest expense jumped 138% year-on-year. This reflects the working capital needed to fund the sales boom, as receivables and inventory swelled. A report from ScanX.trade noted cash from operations turned negative for the half-year, a critical divergence from the reported profit.
A two-speed business
The steel division, producing a record 17,882 tons, drove the quarter with a 63% jump in export revenue. The frozen food brand GOELD is also expanding, with a BRC-accredited plant and a growing product range for domestic and export markets, according to StockScans.in.
The consolidated profit figure of ₹12.14 crore includes a ₹7.19 crore share of profit from an associate. This accounting gain, highlighted by ScanX.trade, flatters the bottom line but is separate from core operational performance.
The outlook hinges on collections
The immediate challenge is converting sales into cash. With receivables climbing, the company's ability to tighten its collection cycle will determine if the growth is sustainable. The broader steel demand outlook is supportive, with India's consumption expected to grow 7% this fiscal year.
Key Points
- Revenue growth of 57% YoY was powered by record steel production and a 63% surge in export sales.
- Net profit margin fell 280 basis points as input costs and interest expenses rose sharply.
- Operational cash flow turned negative due to a large build-up in trade receivables and inventory.
- The consolidated profit includes a significant share of profit from an associate, masking weaker core profitability.
Hexa Perspective
This quarter reveals the classic tension of a capital-intensive business in a growth spurt. The revenue engine is firing, but it is running on expensive fuel—higher working capital debt and stretched receivables. The 8.8% net margin is well below the trailing twelve-month average of 14.1%, indicating the current cost structure cannot support the sales pace.
The path forward requires either pricing power to recover margins or much tighter working capital management to ease the cash burn. Until one of those shifts, the impressive top-line numbers will continue to tell only half the story.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.