Sakthi Sugars (SAKHTISUG) Q2 FY27 Swings to Profit on Surging Revenue, But High Debt Caps Gains
The sugar maker posted a ₹31 crore profit in Q2 FY27, a sharp turnaround from last year's loss, but a heavy debt burden and rising input costs cloud the outlook.
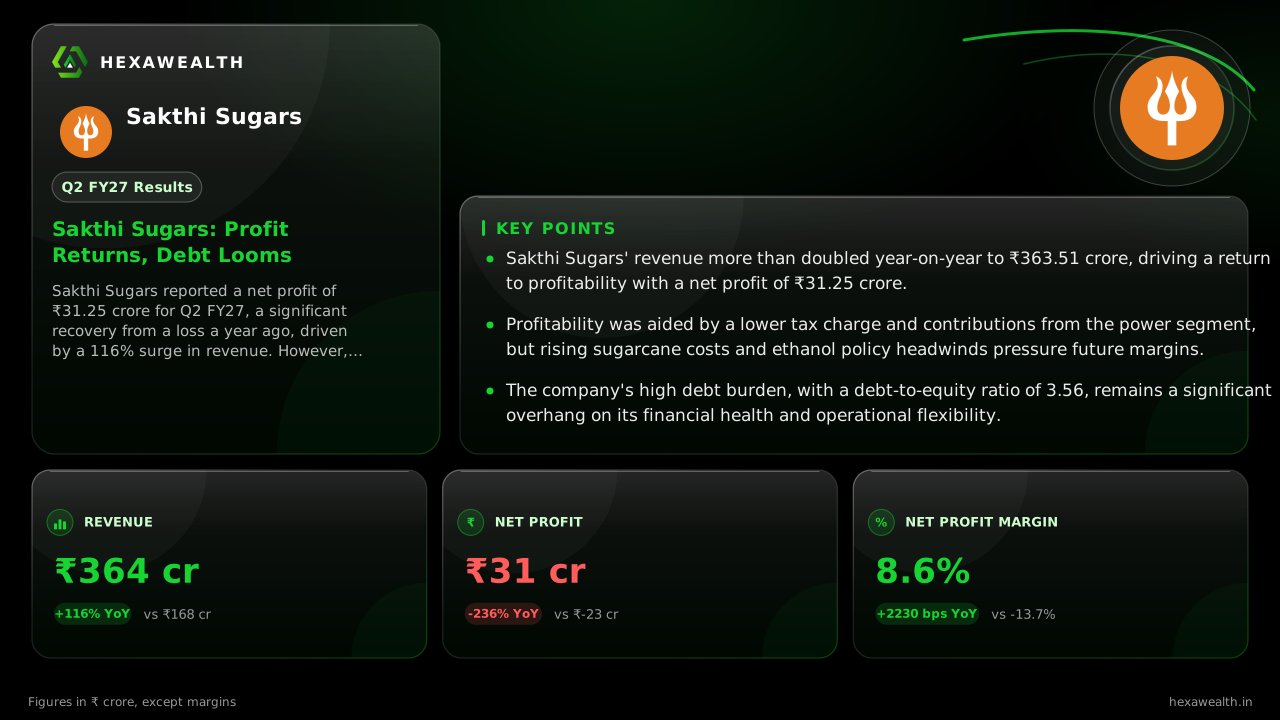
Sakthi Sugars reported a net profit of ₹31.25 crore for Q2 FY27, a significant recovery from a loss a year ago, driven by a 116% surge in revenue. However, the company's high debt and a challenging policy environment for ethanol pose risks to sustained profitability.
For Sakthi Sugars, the September quarter is a story of powerful top-line momentum finally reaching the bottom line, but a towering debt load ensures the celebration is muted. Revenue more than doubled year-on-year, swinging the company to a quarterly profit after a loss in Q1.
The numbers show a business in recovery, yet one still under pressure. Revenue for Q2 FY27 stood at ₹363.51 crore, up 116% from a weak base last year. Net profit was ₹31.25 crore, a stark improvement from a ₹23.06 crore loss in Q2 FY26 and a ₹1.83 crore loss last quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 168.27
- Revenue (₹ Cr), Q3 FY26: 126.35
- Revenue (₹ Cr), Q4 FY26: 301.92
- Revenue (₹ Cr), Q1 FY27: 376.91
- Revenue (₹ Cr), Q2 FY27: 363.51
- Profit (₹ Cr), Q2 FY26: -23.06
- Profit (₹ Cr), Q3 FY26: -34.20
- Profit (₹ Cr), Q4 FY26: 86.50
- Profit (₹ Cr), Q1 FY27: -1.83
- Profit (₹ Cr), Q2 FY27: 31.25
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 168.27
- Revenue (₹ Cr), Q3 FY26: 126.35
- Revenue (₹ Cr), Q4 FY26: 301.92
- Revenue (₹ Cr), Q1 FY27: 376.91
- Revenue (₹ Cr), Q2 FY27: 363.51
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: -23.06
- Profit (₹ Cr), Q3 FY26: -34.20
- Profit (₹ Cr), Q4 FY26: 86.50
- Profit (₹ Cr), Q1 FY27: -1.83
- Profit (₹ Cr), Q2 FY27: 31.25
Net Profit Margin %
- Net Profit Margin %, Q2 FY26: -13.7
- Net Profit Margin %, Q3 FY26: -27.1
- Net Profit Margin %, Q4 FY26: 28.6
- Net Profit Margin %, Q1 FY27: -0.5
- Net Profit Margin %, Q2 FY27: 8.6
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 363.51YoY +116% | 376.91 | 168.27 |
| Profit (₹ Cr) | 31.25YoY +236% | -1.83 | -23.06 |
| Net Profit Margin % | 8.6YoY +163% | -0.5 | -13.7 |
The profit recovery was supported by a sharp drop in tax outgo, as noted by StockFin.ai. More critically, the power segment was a key driver, having delivered a positive result before finance costs in the prior quarter while the sugar segment was in deficit, according to a Multibagg.ai report.
Why Margins Remain Under Siege
Despite the revenue surge, total expenses rose 62.4% year-on-year, reflecting the intense cost pressures in the sugar industry. The government has set a higher Fair and Remunerative Price (FRP) for sugarcane this season, raising input costs. At the same time, policy restrictions are curbing a lucrative revenue stream.
Crisil Ratings notes that restrictions on ethanol production from sugar-based feedstocks will erode a key source of higher-margin earnings for mills. This structural shift, alongside rising cane costs, is expected to squeeze sector-wide operating margins to around 6% this fiscal.
Live Chart
· SAKHTISUG
(BSE)
ISIN: INE623A01011
The Debt That Won't Disappear
The company's financial stability is overshadowed by its balance sheet. Sakthi Sugars carries a debt-to-equity ratio of 3.56, indicating heavy reliance on borrowed funds. Interest coverage remains negative, meaning operating profits are insufficient to service its interest costs.
This high leverage, highlighted in a StockFin.ai analysis, limits financial flexibility and amplifies vulnerability in a capital-intensive, cyclical industry. Management's recent focus has been on cost-conscious governance, including reappointing top executives without remuneration, rather than outlining major growth capex.
Key Points
- Sakthi Sugars' revenue more than doubled year-on-year to ₹363.51 crore, driving a return to profitability with a net profit of ₹31.25 crore.
- Profitability was aided by a lower tax charge and contributions from the power segment, but rising sugarcane costs and ethanol policy headwinds pressure future margins.
- The company's high debt burden, with a debt-to-equity ratio of 3.56, remains a significant overhang on its financial health and operational flexibility.
Hexa Perspective
The quarter demonstrates Sakthi Sugars can capitalize on strong sugar realizations to generate profit, a positive step from the losses of the past year. However, the sustainability of this earnings bounce is questionable.
The twin pressures of mandated higher cane prices and restricted ethanol diversion create a margin squeeze that even firm sugar prices may not fully offset. With its substantial debt load, the company has little room for error. The path forward depends less on sugar prices and more on navigating this tighter policy landscape while managing its balance sheet.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.