Complete Sports and Management India (CSML) Q2 FY27 Posts Strong Growth Amid Margin Pressure
Complete Sports and Management India reported a 37% jump in revenue and 25% profit growth in Q2 FY27, but a tax surge and new costs squeezed net margins.
CSML's Q2 FY27 saw robust top-line growth driven by large project wins, yet net profit margins contracted due to a significant tax charge and rising interest and depreciation expenses post-IPO.
For Complete Sports and Management India, a distributor and installer of bowling alleys and arcade games, growth is measured in large-format project wins. Its first results since a September IPO show the top line delivering, with revenue surging 37% year-on-year to ₹63 crore. Yet a sharp tax increase and new operating costs kept a lid on bottom-line expansion, revealing the financial shape of a newly public company.
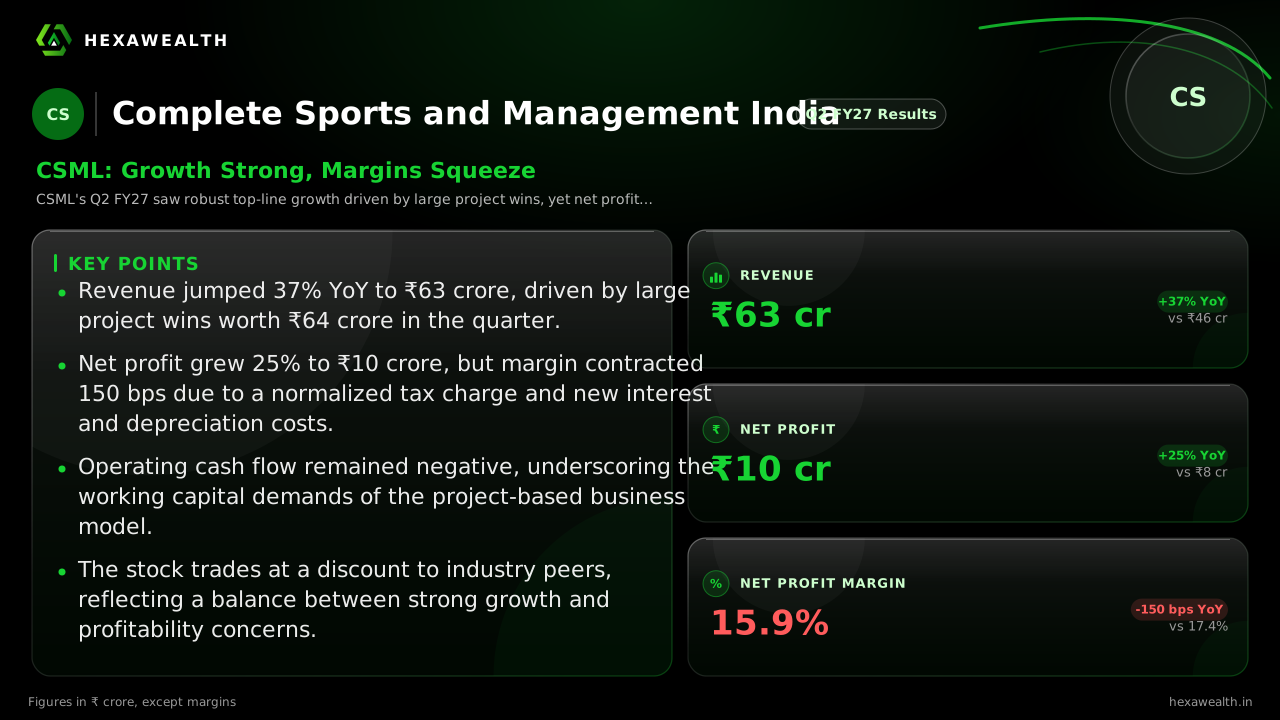
The quarter's scorecard shows profit grew 25% to ₹10 crore. However, net profit margin contracted by 150 basis points to 15.9%, as expenses grew in lockstep with sales. The table below captures the year-on-year shift.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 46.0
- Revenue (₹ Cr), Q2 FY27: 63.0
- Profit (₹ Cr), Q2 FY26: 8.0
- Profit (₹ Cr), Q2 FY27: 10.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 46.0
- Revenue (₹ Cr), Q2 FY27: 63.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 8.0
- Profit (₹ Cr), Q2 FY27: 10.0
Net Profit Margin
- Net Profit Margin, Q2 FY26: 17.4%
- Net Profit Margin, Q2 FY27: 15.9%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 63.0YoY +37% | 46.0 |
| Profit (₹ Cr) | 10.0YoY +25% | 8.0 |
| Net Profit Margin | 15.9%YoY -8.6% | 17.4% |
Why Margins Narrowed Despite the Surge
Revenue growth was powered by the scale of projects, with the company securing ₹64 crore of new orders in the quarter alone, according to a Konexio Network report. This included a ₹40 crore contract for a large family entertainment centre. Yet profit growth lagged behind the top line.
The primary drag was a tax charge of ₹3.15 crore, up from just ₹0.03 crore a year ago, as noted by Reports Radar. This normalized the effective tax rate following the IPO. Furthermore, the payload shows interest and depreciation expenses emerged at ₹1 crore each this quarter, absent in the year-ago period, reflecting the costs of a larger balance sheet.
The Cash-Flow Conundrum and Execution Focus
Strong sales have not yet translated into operating cash. For the first half of FY27, operating cash flow was a negative ₹11.92 crore, as per MarketPing. This highlights the working capital intensity of the project business, where suppliers are paid before customers settle their bills.
Live Chart
· CSML
(BSE)
ISIN: INE2K6801014
Management's priority, stated in the Konexio release, is disciplined execution of these large-format projects to build its track record. With an order book providing visibility, the focus is on converting these wins into timely revenue without further straining working capital.
A Valuation Gap Amidst Growth
Despite the growth, the stock fell 3.4% on the results reaction day, MarketPing reported. The company trades at a P/E of 20.2, a 25% discount to its industry peer average of 27.1. This discount may reflect investor caution over the margin pressure and cash flow profile, even as the top-line story remains compelling.
Key Points
- Revenue jumped 37% YoY to ₹63 crore, driven by large project wins worth ₹64 crore in the quarter.
- Net profit grew 25% to ₹10 crore, but margin contracted 150 bps due to a normalized tax charge and new interest and depreciation costs.
- Operating cash flow remained negative, underscoring the working capital demands of the project-based business model.
- The stock trades at a discount to industry peers, reflecting a balance between strong growth and profitability concerns.
Hexa Perspective
The quarter confirms CSML's ability to win large contracts in a growing entertainment infrastructure market. The margin squeeze, however, is structural for now—a combination of post-IPO tax normalization and the capital costs of scaling. The path to sustained shareholder returns hinges on two factors: converting its robust order book into cash efficiently and managing the concentration risks around its key supplier, Brunswick. The current valuation gap prices in these execution risks against the clear growth runway.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.