Dove Soft (DSL) Q2 FY27 Revenue Soars 60% But Profit Margins Barely Budge
The communications platform's Q2 FY27 sales jumped over 60%, yet net profit margin improved only slightly as expenses kept pace with the top line.
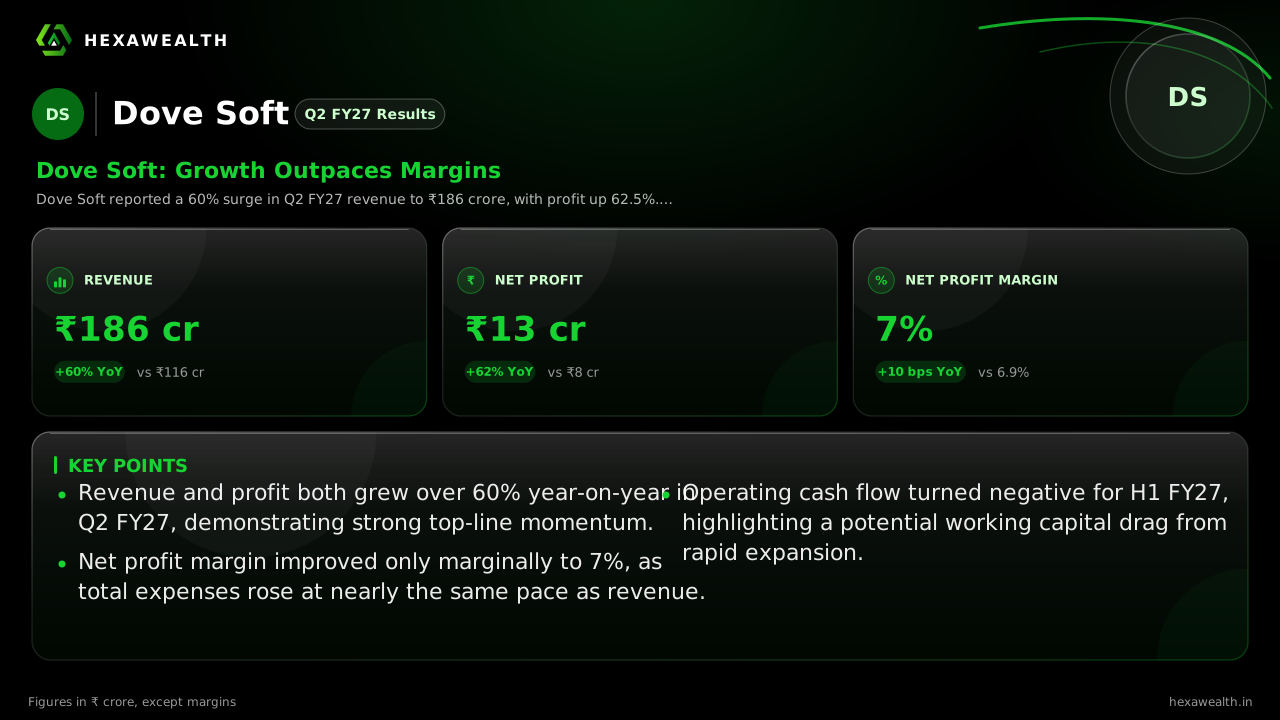
Dove Soft reported a 60% surge in Q2 FY27 revenue to ₹186 crore, with profit up 62.5%. However, net profit margin inched up just 10 basis points as total expenses rose in lockstep, highlighting the cost of rapid growth.
For a company fresh from its IPO and betting on an AI-led transition, growth is the immediate test. Dove Soft's second quarter delivered that in spades, with revenue surging over 60%. Yet the story underneath is one of costs rising just as fast, leaving profitability barely changed.
The numbers show a business scaling rapidly. Consolidated revenue hit ₹186 crore in the September 2026 quarter, up 60.3% from a year ago. Profit followed closely, rising 62.5% to ₹13 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 116.0
- Revenue (₹ Cr), Q2 FY27: 186.0
- Profit (₹ Cr), Q2 FY26: 8.0
- Profit (₹ Cr), Q2 FY27: 13.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 116.0
- Revenue (₹ Cr), Q2 FY27: 186.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 8.0
- Profit (₹ Cr), Q2 FY27: 13.0
Net Profit Margin
- Net Profit Margin, Q2 FY26: 6.9%
- Net Profit Margin, Q2 FY27: 7.0%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 186.0YoY +60% | 116.0 |
| Profit (₹ Cr) | 13.0YoY +63% | 8.0 |
| Net Profit Margin | 7.0%YoY +1.4% | 6.9% |
Why Margins Failed to Lift Off
The near-identical growth rates for revenue and profit point to a lack of operating leverage. Total expenses climbed 62.9% year-on-year, essentially matching the revenue jump. This kept the net profit margin flat, improving a mere 10 basis points to 7%.
MarketPing data shows an EBITDA margin of 9.4% for the quarter. The modest overall margin suggests that while the core messaging business is scaling, the promised shift to higher-value AI and omnichannel services is yet to materially boost profitability.
The Cash Flow Conundrum
A more pressing concern emerged in the cash flow statement. For the first half of FY27, net operating cash flow was negative ₹3.91 crore, according to the company's filing. This is despite reported profits, indicating potential working capital strain as the business grows.
Live Chart
· DSL
(BSE)
ISIN: INE0NXJ01016
The market reaction was muted, with the stock closing flat on the results day. This suggests investors are weighing the strong growth against the margin and cash flow dynamics.
Key Points
- Revenue and profit both grew over 60% year-on-year in Q2 FY27, demonstrating strong top-line momentum.
- Net profit margin improved only marginally to 7%, as total expenses rose at nearly the same pace as revenue.
- Operating cash flow turned negative for H1 FY27, highlighting a potential working capital drag from rapid expansion.
Hexa Perspective
The quarter confirms Dove Soft's ability to win business and grow revenue significantly in a challenging IT services environment. However, the path to becoming a more profitable, AI-driven platform is not yet visible in the margins.
The negative operating cash flow is a watchpoint. It suggests the economics of growth—potentially longer payment cycles with enterprise clients—are pressuring liquidity even as profits are booked. For the transition narrative to hold, the coming quarters need to show either margin expansion or a normalization of cash conversion.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.