Rajshree Polypack (RPPL) Q2 FY27 Profit Drops 31% as One-Off Income Vanishes
The packaging firm's revenue held steady year-on-year, but a sharp fall in other income led to a steep sequential profit decline.
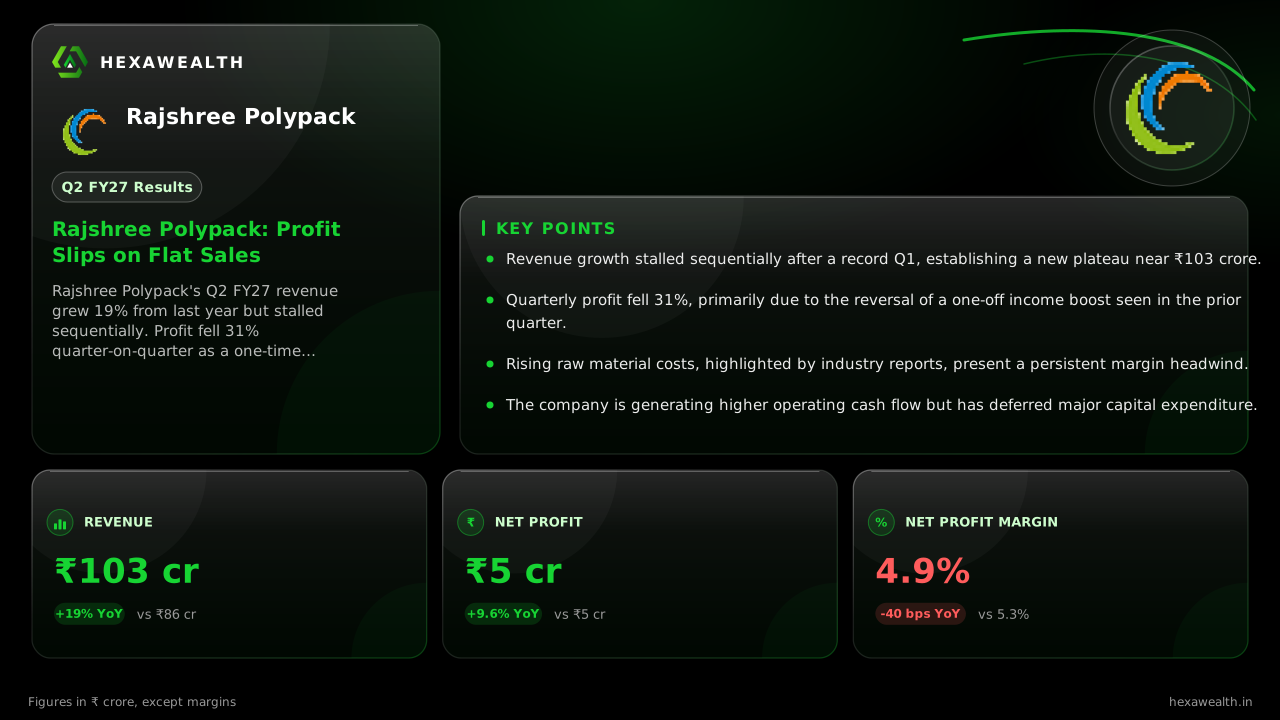
Rajshree Polypack's Q2 FY27 revenue grew 19% from last year but stalled sequentially. Profit fell 31% quarter-on-quarter as a one-time income boost from Q1 disappeared, squeezing margins.
For Rajshree Polypack, the September quarter was about holding a new revenue plateau while a temporary profit cushion vanished. The rigid plastic packaging maker reported sales just shy of ₹103 crore, matching its record June quarter but leaving profit exposed to higher costs.
The numbers show a business in transition. Revenue of ₹102.9 crore marks a solid 19% gain from a year ago, yet it is virtually flat from the prior quarter. Profit fell sharply by 31% sequentially to ₹5.03 crore, pulling the net margin down to 4.9%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 102.9 | 102.91 |
| Profit (₹ Cr) | 5.03 | 7.26 |
| Net Margin (%) | 4.9 | 7.1 |
The One-Off That Disappeared
The steep quarterly profit drop stems largely from a collapse in other income. According to data from Flash Finance, this line item fell 74% sequentially to just ₹0.54 crore from ₹2.1 crore in Q1. That prior-quarter boost, which Multibagg.ai notes was not from core operations, has now reversed.
Without that support, higher expenses bit deeper. Total costs rose 1.3% quarter-on-quarter even as revenue stayed flat. The result was a net profit margin contraction of 220 basis points from June to September.
A Costly Waiting Game
The broader industry context adds pressure. A report from TradingView notes plastic raw material prices have jumped 15-20% in recent weeks and now stand about 60% above pre-war levels. This fresh packaging cost shock is squeezing converters like Rajshree Polypack.
Management, cited by Inve.money in its Q1 concall summary, had flagged raw material volatility compressing gross margins earlier this year. With prices rising again, the cost relief they hoped for has not arrived.
Funding Growth Amid the Squeeze
The company is navigating this with a focus on operational cash flow and modest borrowing. For the first half of FY27, net cash from operations was ₹17.7 crore, up from ₹13.6 crore a year earlier, per Multibagg.ai. Long-term borrowings saw a net increase of about ₹0.5 crore.
Capacity expansion plans are on hold. As per an Alphastreet.com transcript of the Q1 call, a new facility in Eastern India remains pending until current capacities are better utilized. For now, the focus is on sweating existing assets.
Key Points
- Revenue growth stalled sequentially after a record Q1, establishing a new plateau near ₹103 crore.
- Quarterly profit fell 31%, primarily due to the reversal of a one-off income boost seen in the prior quarter.
- Rising raw material costs, highlighted by industry reports, present a persistent margin headwind.
- The company is generating higher operating cash flow but has deferred major capital expenditure.
Hexa Perspective
The quarter reveals a firm hitting a revenue ceiling just as input costs are rising. The annual growth figure is healthy, but the flat sequential sales and vanished other income show how fragile the bottom line can be.
Investors are weighing a valuation that looks inexpensive—a P/E of 6.7 against an industry average of 20.7—against these margin pressures and volatile quarterly profits. The path to its stated FY27 revenue target of ₹370-380 crore now requires a sales pickup in the second half, all while managing a cost environment that offers little respite.
Also read
IRCON: Revenue Up, Profit Down
Market Pulse, 5 Nov 2026: Earnings Upgrades Meet Unwinding Leverage
Gold ETF inflows choked as AMCs suspend fund-of-funds route
Market News Today, 5 Nov 2026: Corporate bond rush hits ₹17,000 crore as yields ease, but NBFCs see funding costs rise
Balrampur Chini: Profit Doubles on Sugar Spike
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.