IRCON Q2 FY27 Profit Falls 27% as Finance Costs and JV Losses Bite
IRCON International's Q2 FY27 revenue grew nearly 15%, but net profit fell sharply due to surging interest expenses and losses from joint ventures.
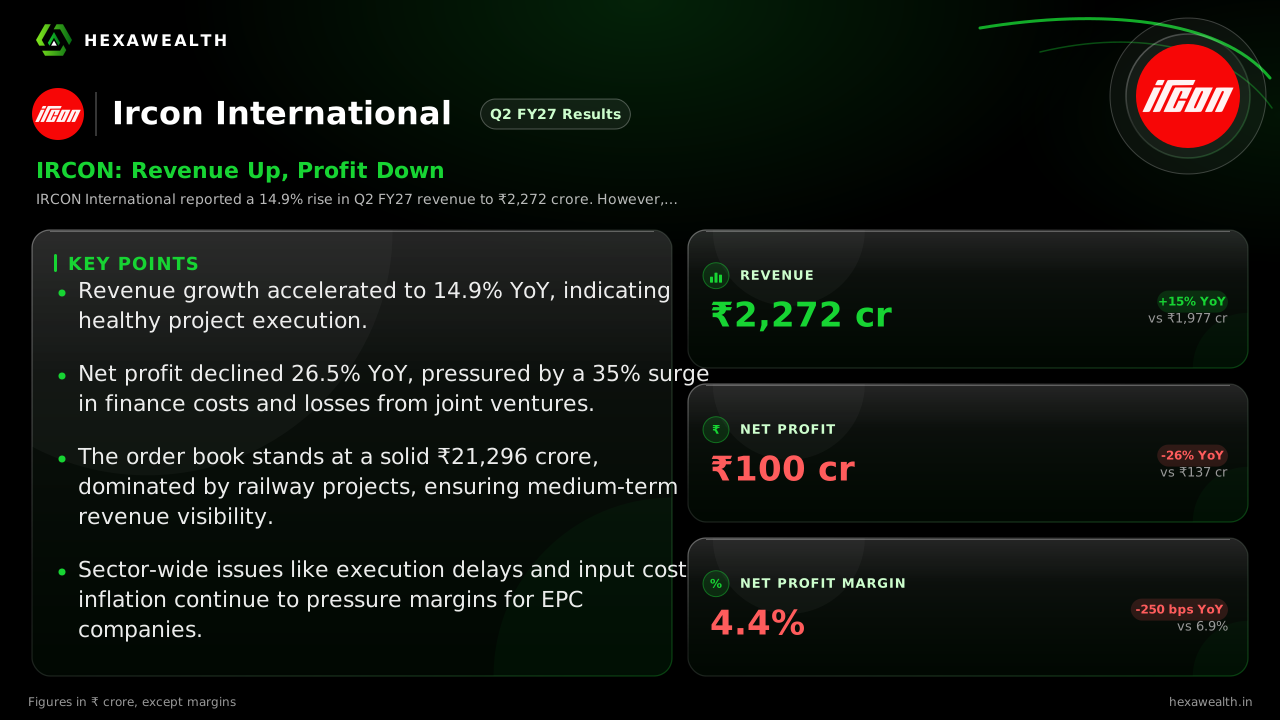
IRCON International reported a 14.9% rise in Q2 FY27 revenue to ₹2,272 crore. However, net profit fell 26.5% to ₹100 crore, pressured by a 35% jump in finance costs and a swing to losses in joint ventures.
For infrastructure EPC companies like IRCON International, strong order books promise future revenue, but current profitability hinges on managing the costs of executing them. The September quarter saw that tension play out clearly, as higher project volumes lifted the top line but a sharp rise in interest expenses and losses from joint ventures dragged the bottom line down.
The numbers show a business accelerating on one front and stalling on another. Consolidated revenue rose 14.9% year-on-year to ₹2,272 crore and grew 16.1% sequentially. Yet, net profit fell 26.5% from the year-ago quarter to ₹100 crore, though it improved 9% from the June quarter. The net profit margin contracted 250 basis points to 4.4%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 2,271.7YoY +15% | 1,955.8 | 1,976.8 |
| Profit (₹ Cr) | 100.3YoY -27% | 92.0 | 136.5 |
| Net Profit Margin (%) | 4.4YoY -36% | 4.7 | 6.9 |
Why the profit fell behind
Two primary forces eroded profitability. First, finance costs surged 35% year-on-year to ₹114 crore, as reported by scanx.trade. This reflects the higher debt required to fund a growing project portfolio.
Second, the contribution from joint ventures swung from a profit of ₹20 crore in Q2 FY26 to a loss of ₹11 crore this quarter, according to the same outlet. This shift alone explains a significant portion of the consolidated profit decline.
A strong backlog meets a tough environment
The company's order book remains robust at ₹21,296 crore, providing visibility. Zeebiz reported that railways account for 76% of this backlog. Recent wins include an ₹862 crore EPC contract from East Central Railway in October.
However, the broader EPC sector faces headwinds. A report by India Ratings cited by nbmcw.com notes the sector saw its ninth consecutive quarter of single-digit revenue growth in Q1 FY27, with margins at a multi-quarter low. Execution bottlenecks and cost pressures are industry-wide challenges.
Key Points
- Revenue growth accelerated to 14.9% YoY, indicating healthy project execution.
- Net profit declined 26.5% YoY, pressured by a 35% surge in finance costs and losses from joint ventures.
- The order book stands at a solid ₹21,296 crore, dominated by railway projects, ensuring medium-term revenue visibility.
- Sector-wide issues like execution delays and input cost inflation continue to pressure margins for EPC companies.
Hexa Perspective
The quarter underscores the operational reality for capital-intensive contractors: revenue recognition is a lagging indicator of order wins, while interest costs are a real-time drag. The strong order book is a clear positive, but its conversion into profit depends on IRCON's ability to manage its capital structure and turn around its joint ventures. Investors are left weighing the security of a ₹21,000 crore backlog against the persistence of elevated finance costs in a higher-rate environment. The stock's 37% decline over the past year and its P/E of 18.2, a 19% discount to the industry, already price in significant margin pressure. The question is whether execution can improve fast enough to stop the profit squeeze.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.