Omnitech Engineering (OMNI) Q2 FY27 Profit Growth Lags Revenue as Expansion Costs Mount
Revenue jumped 40% year-on-year, but higher interest and operating expenses squeezed net profit margins lower for the second straight quarter.
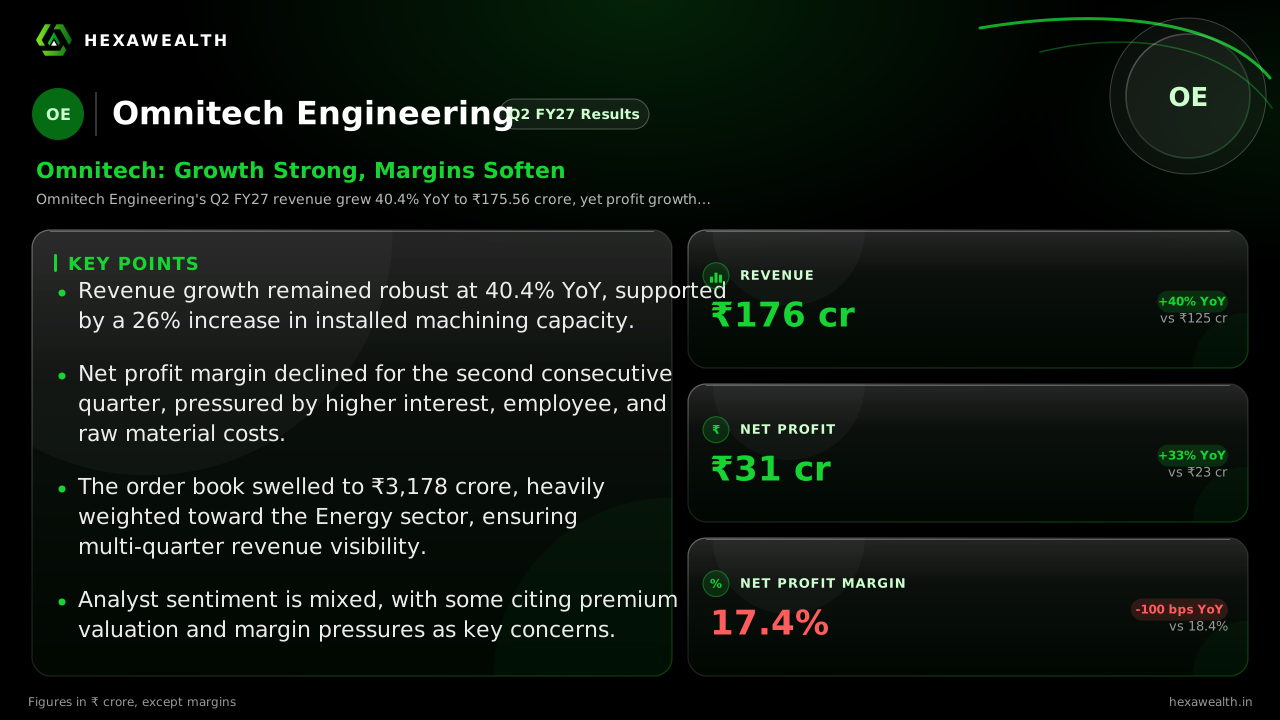
Omnitech Engineering's Q2 FY27 revenue grew 40.4% YoY to ₹175.56 crore, yet profit growth lagged at 32.9%. Margins contracted as the company spent more to fund its expansion and service a record order book.
For Omnitech Engineering, the September quarter was about converting a massive order backlog into revenue while managing the costs of rapid scaling. The precision component maker delivered strong top-line growth but saw profitability soften as it invested heavily to meet demand.
The numbers show a clear trajectory. Revenue reached ₹175.56 crore, up 40.4% from a year ago and 5.3% from the June quarter. Profit followed, rising 32.9% year-on-year to ₹30.57 crore. Yet the net profit margin slipped to 17.4%, down 100 basis points from Q2 FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 125.00
- Revenue (₹ Cr), Q3 FY26: 134.41
- Revenue (₹ Cr), Q4 FY26: 148.72
- Revenue (₹ Cr), Q1 FY27: 166.66
- Revenue (₹ Cr), Q2 FY27: 175.56
- Profit (₹ Cr), Q2 FY26: 23.00
- Profit (₹ Cr), Q3 FY26: 22.23
- Profit (₹ Cr), Q4 FY26: 29.33
- Profit (₹ Cr), Q1 FY27: 29.73
- Profit (₹ Cr), Q2 FY27: 30.57
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 125.00
- Revenue (₹ Cr), Q3 FY26: 134.41
- Revenue (₹ Cr), Q4 FY26: 148.72
- Revenue (₹ Cr), Q1 FY27: 166.66
- Revenue (₹ Cr), Q2 FY27: 175.56
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 23.00
- Profit (₹ Cr), Q3 FY26: 22.23
- Profit (₹ Cr), Q4 FY26: 29.33
- Profit (₹ Cr), Q1 FY27: 29.73
- Profit (₹ Cr), Q2 FY27: 30.57
Net Profit Margin
- Net Profit Margin, Q2 FY26: 18.4%
- Net Profit Margin, Q3 FY26: 16.5%
- Net Profit Margin, Q4 FY26: 19.7%
- Net Profit Margin, Q1 FY27: 17.8%
- Net Profit Margin, Q2 FY27: 17.4%
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 175.56YoY +40% | 166.66 | 125.00 |
| Profit (₹ Cr) | 30.57YoY +33% | 29.73 | 23.00 |
| Net Profit Margin | 17.4%YoY -5.4% | 17.8% | 18.4% |
The cost of funding growth
Profit growth lagged revenue because costs rose faster. Interest expense hit a record ₹11.73 crore, up 17.3% year-on-year, as the company took on more debt to fund expansion. MarketsMojo noted this signals increased leverage for growth initiatives.
Operating costs also climbed. Employee benefits rose to ₹26.63 crore from ₹20.11 crore a year ago. Other expenses and raw material consumption jumped significantly, pressuring the EBITDA margin down to 29.2% from 34.9% in Q2 FY26.
An energy-heavy order pipeline
The growth engine is clear. The Energy segment drove 53.5% of Q2’s classified revenue, according to a Multibagg.ai analysis. Its dominance is even greater in the future pipeline, making up 76.15% of the colossal ₹3,178 crore order book as of October 31.
Live Chart
· OMNI
(BSE)
ISIN: INE0UH301010
This backlog, which includes a multi-year order from Weatherford valued over $100 million, provides strong revenue visibility. Management expects IPO proceeds and new capacity to help expand it further.
The market’s reality check
Despite the growth, some analysts express caution. MarketsMoji's report highlighted concerns over margin compression, negative operating cash flows, and capital efficiency. It assigned the stock a "Sell" rating, arguing the 70x P/E multiple is unsustainable without improved returns.
The stock had retreated about 12.5% from its 52-week high ahead of the results. This suggests the market is weighing the impressive growth story against the rising cost of achieving it.
Key Points
- Revenue growth remained robust at 40.4% YoY, supported by a 26% increase in installed machining capacity.
- Net profit margin declined for the second consecutive quarter, pressured by higher interest, employee, and raw material costs.
- The order book swelled to ₹3,178 crore, heavily weighted toward the Energy sector, ensuring multi-quarter revenue visibility.
- Analyst sentiment is mixed, with some citing premium valuation and margin pressures as key concerns.
Hexa Perspective
Omnitech is in a classic growth-investment phase. The top-line momentum is undeniable, backed by a formidable order book. Yet the margin squeeze shows the price of that expansion—higher leverage and operating costs.
The next few quarters will test whether this spending translates into operating leverage and better cash generation. Investors are betting on the order book conversion, but remain watchful for any slippage in execution or further margin pressure that could challenge the current valuation.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.