Accord Transformer (ACCORDTS) Profit Triples as Revenue Doubles in Q2 FY27
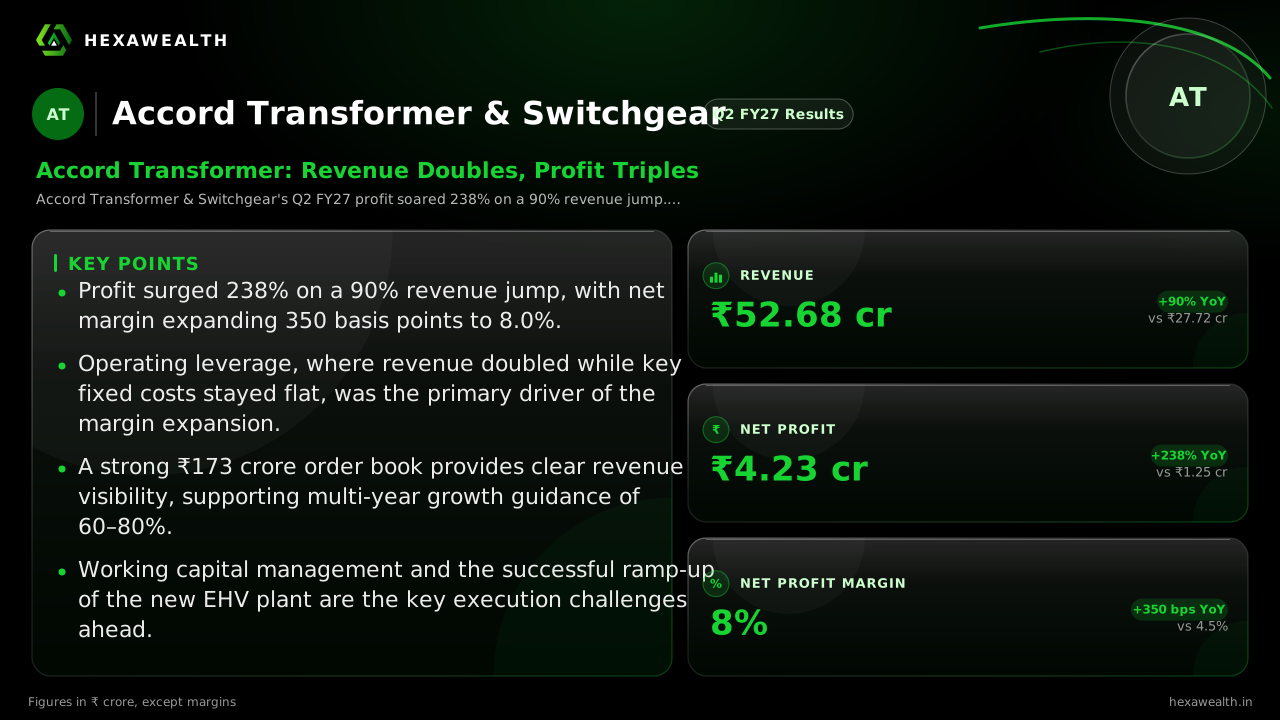
Accord Transformer's Q2 FY27 profit surged 238% as revenue nearly doubled, driven by operating leverage and a strong order book.
Accord Transformer & Switchgear's Q2 FY27 profit soared 238% on a 90% revenue jump. Operating leverage from a robust order book fueled a 350-bp margin expansion, even as the company prepares for a major EHV plant expansion.
For a transformer maker riding India's power infrastructure wave, the test is converting order books into profitable execution. Accord Transformer & Switchgear passed that test in the September quarter, turning a robust order pipeline into a sharp profit surge.
Revenue for Q2 FY27 stood at ₹52.68 crore, up 90% from a year ago. Net profit more than tripled to ₹4.23 crore, a 238% jump. The quarter's net profit margin expanded by 350 basis points to 8.0%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 57.53
- Revenue (₹ Cr), Q2 FY26: 27.72
- Revenue (₹ Cr), Q4 FY26: 42.35
- Revenue (₹ Cr), Q2 FY27: 52.68
- Profit (₹ Cr), Q4 FY25: 5.45
- Profit (₹ Cr), Q2 FY26: 1.25
- Profit (₹ Cr), Q4 FY26: 3.25
- Profit (₹ Cr), Q2 FY27: 4.23
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 57.53
- Revenue (₹ Cr), Q2 FY26: 27.72
- Revenue (₹ Cr), Q4 FY26: 42.35
- Revenue (₹ Cr), Q2 FY27: 52.68
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY25: 5.45
- Profit (₹ Cr), Q2 FY26: 1.25
- Profit (₹ Cr), Q4 FY26: 3.25
- Profit (₹ Cr), Q2 FY27: 4.23
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY25: 9.5
- Net Profit Margin (%), Q2 FY26: 4.5
- Net Profit Margin (%), Q4 FY26: 7.7
- Net Profit Margin (%), Q2 FY27: 8.0
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 52.68YoY +90% | 27.72 |
| Profit (₹ Cr) | 4.23YoY +238% | 1.25 |
| Net Profit Margin (%) | 8.0YoY +78% | 4.5 |
The Leverage Behind the Leap
Management, in its earnings call summarized by MarketPing, attributed the margin expansion to operating leverage. Revenue nearly doubled while major overheads like salaries and facility costs remained largely fixed. This spread fixed costs over a much larger revenue base, lifting per-unit profitability.
Interest costs also fell by 50% year-on-year, providing a further tailwind. The result was a profit surge that far outpaced even the strong top-line growth.
A Full Pipeline and a Big Bet
The growth engine is a ₹173 crore order book reported as of September 30, according to a Business Standard release. Orders worth approximately ₹77 crore were secured in the first half, with a pipeline of about ₹200 crore under discussion for FY27.
Live Chart
· ACCORDTS
(BSE)
ISIN: INE132201018
This visibility supports management's reiterated guidance of 60–80% revenue growth over the next two to three years. The bigger bet is a new Extra High Voltage (EHV) plant, a ₹35–40 crore project that will lift annual capacity tenfold to 15,000 MVA.
The Squeeze That Comes With Scale
Scaling this fast brings its own pressures. The company's working capital cycle is currently four to five months, as per the MarketPing call summary, as it procures key raw materials like copper and oil immediately after receiving orders to hedge price volatility.
Management is targeting a reduction to three to four months, but this depends on commodity price stabilization. Furthermore, the new EHV plant's initial depreciation and interest costs are expected to weigh on net profit in its early months.
Key Points
- Profit surged 238% on a 90% revenue jump, with net margin expanding 350 basis points to 8.0%.
- Operating leverage, where revenue doubled while key fixed costs stayed flat, was the primary driver of the margin expansion.
- A strong ₹173 crore order book provides clear revenue visibility, supporting multi-year growth guidance of 60–80%.
- Working capital management and the successful ramp-up of the new EHV plant are the key execution challenges ahead.
Hexa Perspective
The quarter shows Accord successfully converting order inflow into financial performance, a critical step for any capital goods company. The margin expansion from operating leverage is real, but its sustainability hinges on maintaining this high volume run-rate.
The upcoming EHV expansion is a classic scale-or-stagnate move in a market management describes as structurally undersupplied. Investors are weighing the near-term profit dilution from the plant's startup costs against the long-term opportunity in higher-value transformers. The next few quarters will test both the company's execution on its large order book and its capital allocation discipline.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.