OCCL (OCCLLTD) Q2 FY27 Profit Falls 31% Sequentially Despite Doubling Revenue
The specialty chemical maker's revenue more than doubled year-on-year, but a sharp sequential profit drop highlights margin pressure from rising input costs.
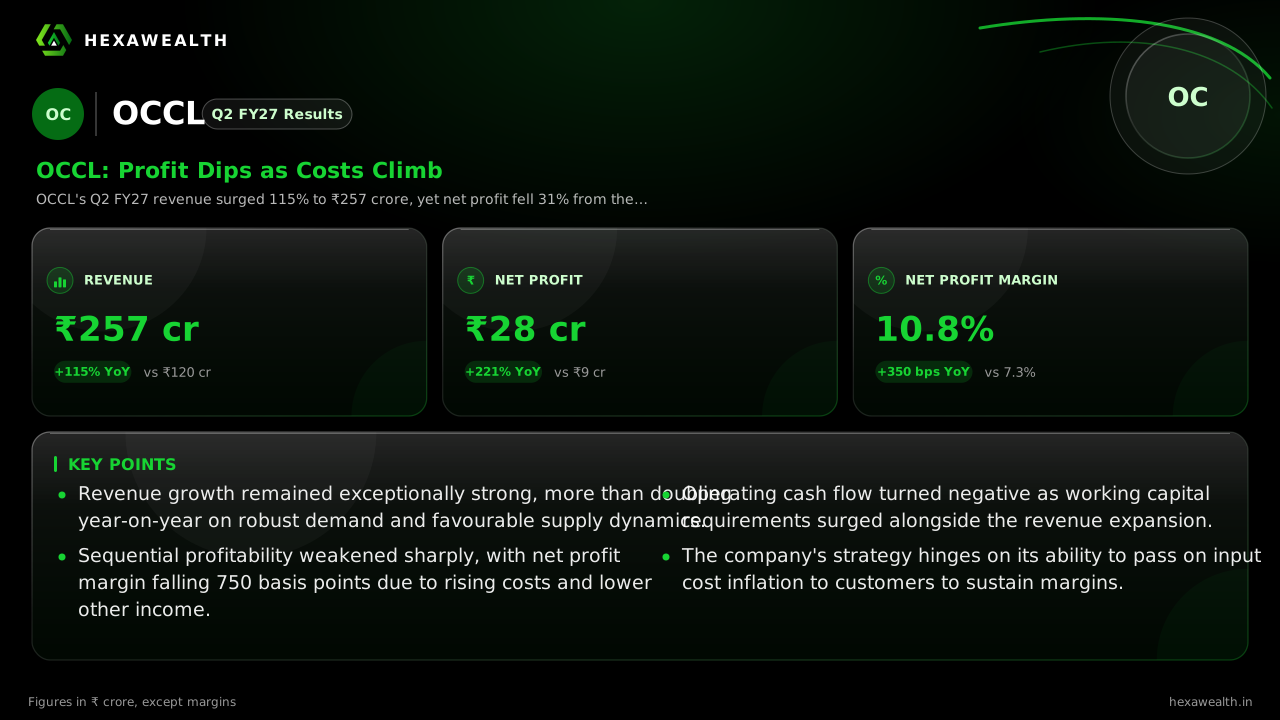
OCCL's Q2 FY27 revenue surged 115% to ₹257 crore, yet net profit fell 31% from the previous quarter. The drop reflects a margin squeeze as raw material costs rose faster than realisations, despite strong demand for its Insoluble Sulphur.
For OCCL, a key supplier of Insoluble Sulphur to the tyre industry, the September quarter was a story of two competing forces. Surging global demand and constrained Chinese supply pushed revenue to a record high. Yet profitability took a step back, revealing the cost pressures that came with that growth.
The numbers show the split. Revenue for Q2 FY27 stood at ₹257.04 crore, more than double the ₹119.64 crore from a year ago. Net profit grew even faster year-on-year, jumping 221% to ₹27.86 crore. The sequential view tells a different story. Profit fell 31% from the ₹40.25 crore earned in Q1 FY27, even as revenue grew 17%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 119.64
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 114.17
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 149.00
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 219.67
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 257.04
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 8.69
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 6.53
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 19.35
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 40.25
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 27.86
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 119.64
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 114.17
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 149.00
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 219.67
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 257.04
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 8.69
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 6.53
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 19.35
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 40.25
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 27.86
Net Profit Margin
- Net Profit Margin, Q2 FY26 (Sep 2025): 7.3%
- Net Profit Margin, Q3 FY26 (Dec 2025): 5.7%
- Net Profit Margin, Q4 FY26 (Mar 2026): 13.0%
- Net Profit Margin, Q1 FY27 (Jun 2026): 18.3%
- Net Profit Margin, Q2 FY27 (Sep 2026): 10.8%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 257.04 | 219.67 |
| Profit (₹ Cr) | 27.86 | 40.25 |
| Net Profit Margin | 10.8% | 18.3% |
Why the profit engine slowed
Management, cited by Multibagg.ai, attributed the strong yearly growth to higher sales volume and realisations for Insoluble Sulphur. This was driven by reduced Chinese imports into India, global supply constraints, and customer inventory stocking. However, the company noted that higher raw-material costs contributed to the price increases.
This link between cost and price became the quarter's pinch point. Total expenses rose 31% sequentially, outpacing the 17% revenue growth. A key factor was a steep drop in other income, which fell 83% to just ₹0.33 crore. Management also stated that the previous quarter's profit was higher due to an inventory valuation gain, clarifying the sequential decline.
The cash flow divergence
Strong earnings did not translate into cash. According to a Multibagg.ai report, OCCL reported a net cash outflow of ₹40.68 crore from operations for the first half of FY27. This was due to a significant build-up in inventory and trade receivables as the business scaled rapidly. It highlights the working capital intensity of the current growth phase.
Live Chart
· OCCLLTD
(BSE)
ISIN: INE0PK601023
The company maintains a conservative balance sheet, with a reported debt-to-equity ratio of 0.2. It also declared an interim dividend of ₹2 per share. Management's stated focus is on timely pass-through of raw material costs to protect per-tonne contribution margins while expanding domestic market share.
Key Points
- Revenue growth remained exceptionally strong, more than doubling year-on-year on robust demand and favourable supply dynamics.
- Sequential profitability weakened sharply, with net profit margin falling 750 basis points due to rising costs and lower other income.
- Operating cash flow turned negative as working capital requirements surged alongside the revenue expansion.
- The company's strategy hinges on its ability to pass on input cost inflation to customers to sustain margins.
Hexa Perspective
The quarter confirms OCCL is riding a powerful demand wave, but the ride is getting more expensive. The margin compression shows that cost recovery is lagging, a typical challenge in a rapid growth phase. The outlook depends on two factors holding: sustained demand from the global tyre industry and OCCL's pricing power to protect contribution margins.
The negative cash flow is a watchpoint, not an immediate alarm, given the low leverage. It signals that the quality of earnings will be tested in the coming quarters as the company manages its expanded scale. The story has shifted from pure growth to profitable, cash-generative growth.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.