CWD Q2 FY27's Profit Plunges 75% as Expansion Costs Bite
CWD's Q2 revenue jumped 46% year-on-year, but net profit collapsed 75% as heavy depreciation and interest costs from a major factory expansion squeezed margins.
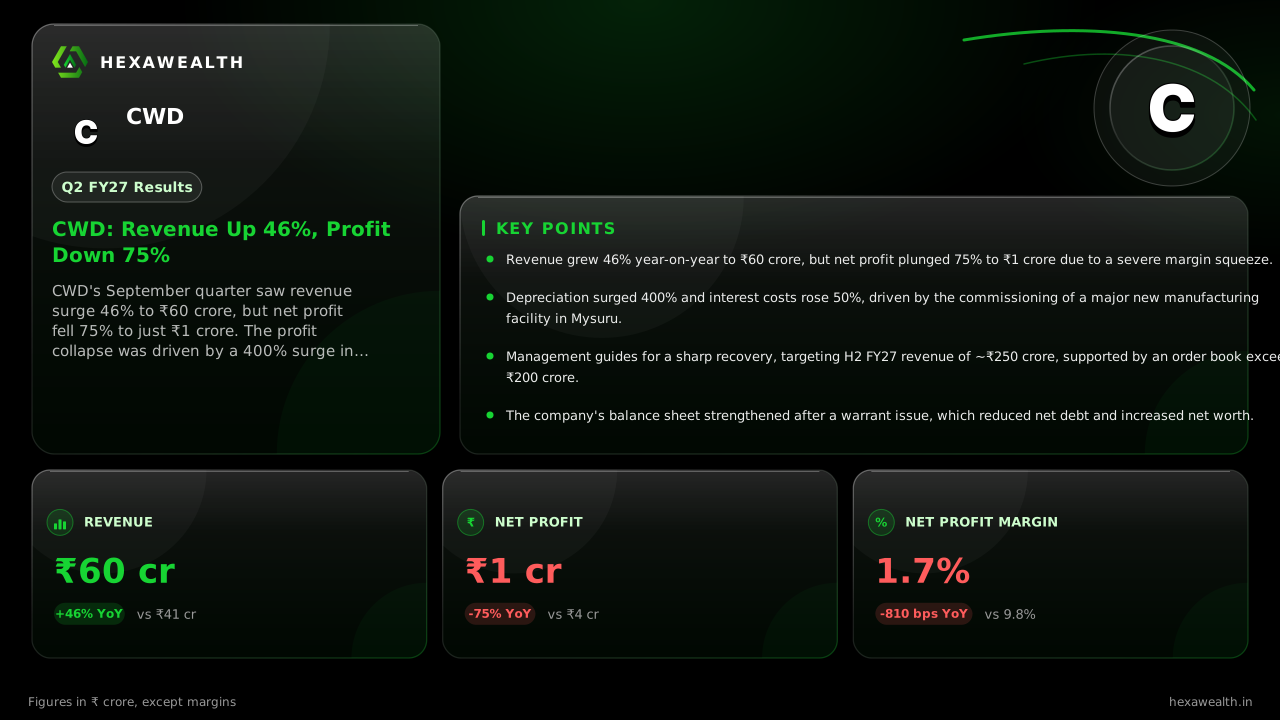
CWD's September quarter saw revenue surge 46% to ₹60 crore, but net profit fell 75% to just ₹1 crore. The profit collapse was driven by a 400% surge in depreciation from a new Mysuru factory and higher interest costs, squeezing the net margin to 1.7%.
For CWD, a manufacturer of smart devices and IoT solutions, growth has come at a steep price. The company's September quarter revenue surged 46% year-on-year to ₹60 crore, but its net profit collapsed 75% to just ₹1 crore. The story is one of aggressive investment finally hitting the income statement.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 7.0
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 27.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 41.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 106.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 60.0
- Profit (₹ Cr), Q2 FY25 (Sep 2024): -2.0
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 4.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 4.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 6.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 1.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 7.0
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 27.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 41.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 106.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 60.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25 (Sep 2024): -2.0
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 4.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 4.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 6.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 1.0
Net Profit Margin
- Net Profit Margin, Q2 FY25 (Sep 2024): -28.6%
- Net Profit Margin, Q4 FY25 (Mar 2025): 14.8%
- Net Profit Margin, Q2 FY26 (Sep 2025): 9.8%
- Net Profit Margin, Q4 FY26 (Mar 2026): 5.7%
- Net Profit Margin, Q2 FY27 (Sep 2026): 1.7%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 60.0 | 106.0 |
| Profit (₹ Cr) | 1.0 | 6.0 |
| Net Profit Margin | 1.7% | 5.7% |
The sequential drop from a ₹106-crore revenue quarter shows the lumpiness of its order-based business. Yet the real pressure came from costs that grew faster than sales.
Why the margins collapsed
A 400% year-on-year surge in depreciation was the primary culprit, as reported by Stockfin.ai. This stems from a major capacity expansion, including a new Mysuru factory that tripled daily soundbox output. Interest expense also rose 50% as the company borrowed to fund inventory for large orders.
With total expenses up 67% against the 46% revenue gain, the net profit margin shrank 810 basis points to 1.7%. The company's half-year EBITDA margin fell to 15.3% from 20.9% a year ago, confirming the operating squeeze.
Live Chart
· CWD
(BSE)
ISIN: INE0H8H01019
A stronger second half in sight?
Management has provided a clear path to recovery. According to Stockwatch.live, CWD expects H2 FY27 revenue of approximately ₹250 crore, lifting its full-year guidance to around ₹300 crore. This implies a massive sequential acceleration.
The optimism is backed by an order book exceeding ₹200 crore at the end of FY26, as noted by MarketPing. It includes soundbox orders worth ₹170-172 crore and a smart meter module order of about ₹45 crore. The new capacity is now aimed at fulfilling this backlog.
The cash trade-off
The aggressive investment has strained profits but strengthened the balance sheet. A recent warrant call raised ₹28.87 crore, which was used to repay short-term debt. MCapital reports that net debt fell sharply, with net worth rising to about ₹143 crore by September 2026.
This financial repair provides a cushion, but the stock market's reaction was harsh. CWD's share price fell over 10% on the results day, as investors weighed the severe margin compression against the promised second-half rebound.
Key Points
- Revenue grew 46% year-on-year to ₹60 crore, but net profit plunged 75% to ₹1 crore due to a severe margin squeeze.
- Depreciation surged 400% and interest costs rose 50%, driven by the commissioning of a major new manufacturing facility in Mysuru.
- Management guides for a sharp recovery, targeting H2 FY27 revenue of ~₹250 crore, supported by an order book exceeding ₹200 crore.
- The company's balance sheet strengthened after a warrant issue, which reduced net debt and increased net worth.
Hexa Perspective
CWD is in a classic investment phase, where top-line growth is visible but profitability is deferred. The quarter's margin collapse is a direct cost of the new capacity needed to execute its large order book.
The guidance for a ₹250-crore second half is ambitious, implying a nearly five-fold sequential jump. Execution on that scale is the only way operating leverage can start to offset the high fixed costs. Investors are betting the order book is real, but the stock's reaction shows patience for proof is thin.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.