CWD Q4 FY26's Revenue Triples to ₹106 Crore in Q4, But Profit Margin Halves
The IoT device maker's quarterly revenue jumped 293% year-on-year, yet a sharp rise in costs cut its net profit margin by more than half.
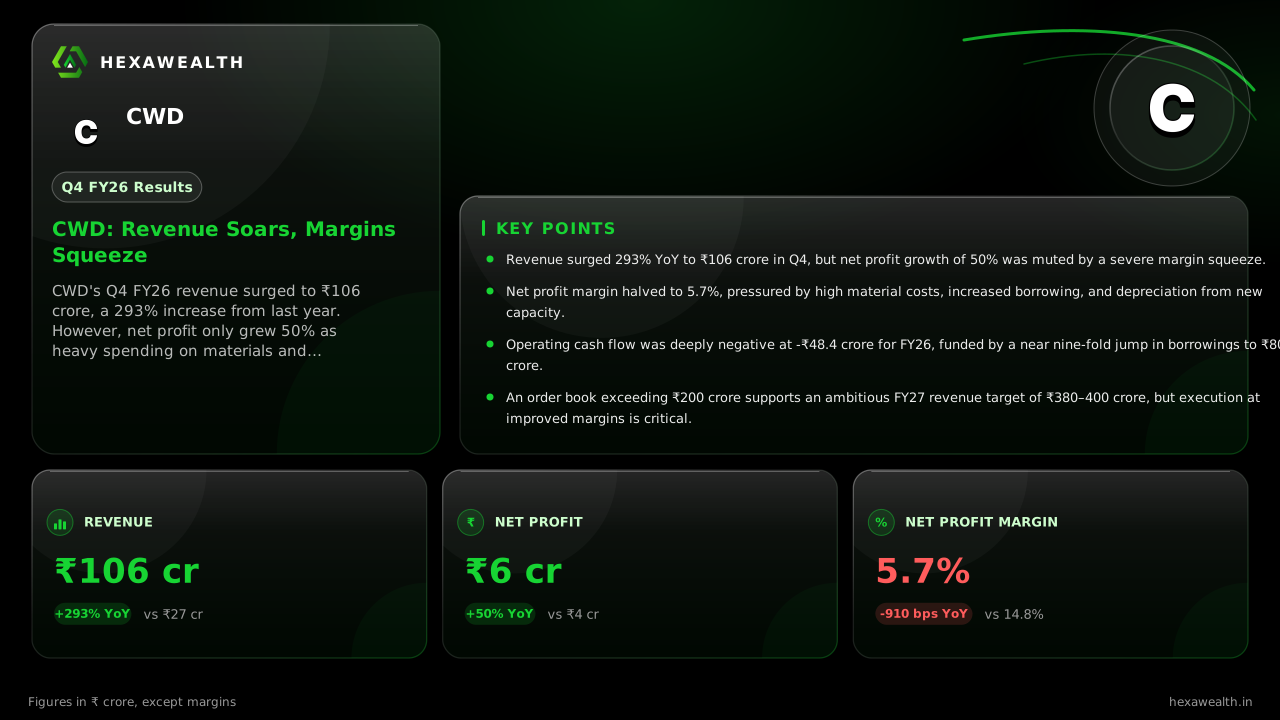
CWD's Q4 FY26 revenue surged to ₹106 crore, a 293% increase from last year. However, net profit only grew 50% as heavy spending on materials and capacity expansion squeezed margins and drained operating cash.
For CWD, a maker of payment soundboxes and smart meter modules, the March quarter was about proving it could deliver on a swelling order book. The result was a revenue explosion, but the cost of that growth left far less profit on each rupee of sales.
Revenue for Q4 FY26 was ₹106 crore, up 293% from a year ago and 159% from the September quarter. Net profit grew 50% year-on-year to ₹6 crore. The real story is in the margin: net profit margin shrank to 5.7%, down from 14.8% in Q4 FY25 and 9.8% in Q2 FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 15.0
- Revenue (₹ Cr), Q2 FY25: 7.0
- Revenue (₹ Cr), Q4 FY25: 27.0
- Revenue (₹ Cr), Q2 FY26: 41.0
- Revenue (₹ Cr), Q4 FY26: 106.0
- Profit (₹ Cr), Q4 FY24: 4.0
- Profit (₹ Cr), Q2 FY25: -2.0
- Profit (₹ Cr), Q4 FY25: 4.0
- Profit (₹ Cr), Q2 FY26: 4.0
- Profit (₹ Cr), Q4 FY26: 6.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 15.0
- Revenue (₹ Cr), Q2 FY25: 7.0
- Revenue (₹ Cr), Q4 FY25: 27.0
- Revenue (₹ Cr), Q2 FY26: 41.0
- Revenue (₹ Cr), Q4 FY26: 106.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 4.0
- Profit (₹ Cr), Q2 FY25: -2.0
- Profit (₹ Cr), Q4 FY25: 4.0
- Profit (₹ Cr), Q2 FY26: 4.0
- Profit (₹ Cr), Q4 FY26: 6.0
Net Profit Margin
- Net Profit Margin, Q4 FY24: 26.7%
- Net Profit Margin, Q2 FY25: -28.6%
- Net Profit Margin, Q4 FY25: 14.8%
- Net Profit Margin, Q2 FY26: 9.8%
- Net Profit Margin, Q4 FY26: 5.7%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 106.0YoY +293% | 27.0 |
| Profit (₹ Cr) | 6.0YoY +50% | 4.0 |
| Net Profit Margin | 5.7%YoY -61% | 14.8% |
Why the profit didn't keep up
Growth came at a high price. Total expenses surged 352% year-on-year, far outpacing revenue. A report from Arthneeti notes that materials accounted for about 84% of FY26 revenue, the dominant cost. The company also ramped up borrowing to fund inventory and receivables ahead of large orders, doubling its interest cost.
This spending funded a capacity leap. In January, CWD commissioned a Mysuru factory that tripled daily soundbox output, according to MarketPing. The capital outlay was significant: fixed asset additions were ₹34 crore for the year.
The cash trade-off
Funding this scale-up consumed cash. Operating cash flow was a negative ₹48.4 crore for FY26, as money got tied up in building inventory (₹58 crore) and waiting for customers to pay (₹35 crore in receivables). To bridge the gap, borrowings ballooned to ₹80 crore from ₹9 crore a year earlier.
Live Chart
· CWD
(BSE)
ISIN: INE0H8H01019
The company's annual report, cited by Newboard, shows an order book over ₹200 crore, providing visibility. Management is targeting FY27 revenue of ₹380–400 crore, implying the Q4 run-rate is a foundation, not a peak.
Key Points
- Revenue surged 293% YoY to ₹106 crore in Q4, but net profit growth of 50% was muted by a severe margin squeeze.
- Net profit margin halved to 5.7%, pressured by high material costs, increased borrowing, and depreciation from new capacity.
- Operating cash flow was deeply negative at -₹48.4 crore for FY26, funded by a near nine-fold jump in borrowings to ₹80 crore.
- An order book exceeding ₹200 crore supports an ambitious FY27 revenue target of ₹380–400 crore, but execution at improved margins is critical.
Hexa Perspective
The quarter confirms CWD can capture demand, turning orders into revenue at an impressive pace. The concern is the model's capital intensity. Margins are thin and cash conversion is poor, meaning growth requires constant external funding.
The FY27 guidance assumes not just sustained volume but also better profitability. For the stock to rerate from its current P/E of 58.6, the company must demonstrate that this quarter's margin is a low point, not a new normal. Investors are betting it can, but the proof will be in the coming quarters' cash flows.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.