LT Elevator (LTELEVATOR) Q2 FY27 Profit Stalls as Costs Outpace 51% Revenue Surge
LT Elevator's Q2 FY27 revenue jumped 51% year-on-year, but flat quarterly profit reveals margin pressure from rising costs and a changing business mix.
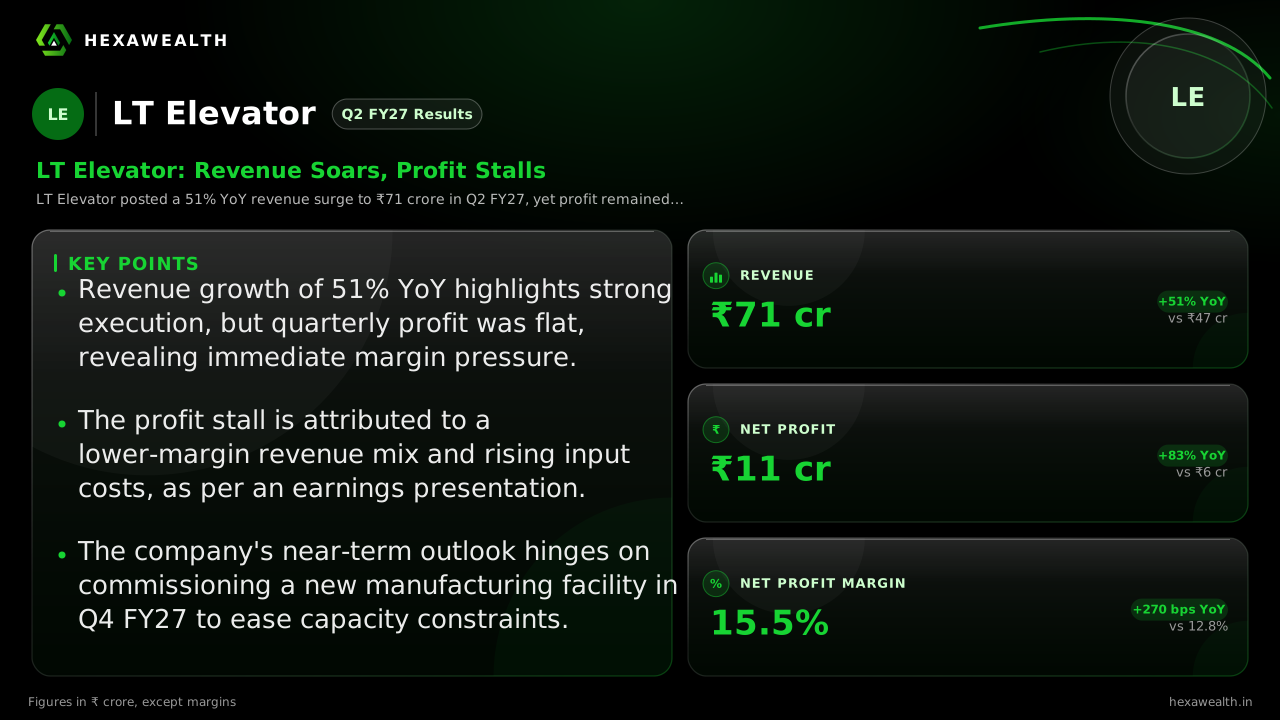
LT Elevator posted a 51% YoY revenue surge to ₹71 crore in Q2 FY27, yet profit remained flat sequentially. The stall points to margin compression from higher input costs and a shift in revenue mix, even as the company bets on a new facility for future growth.
For LT Elevator, scaling up is proving a double-edged sword. The September quarter delivered a 51% yearly revenue surge, a testament to strong execution and strategic acquisitions. Yet, the bottom line tells a different story, with profit stalling as costs rose faster than sales.
Revenue reached ₹71.0 crore, up 10.9% from the prior quarter. Net profit, however, was flat at ₹11.0 crore. This pushed the net profit margin down 170 basis points sequentially to 15.5%, even as it improved year-on-year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 20.0
- Revenue (₹ Cr), Q4 FY25: 37.0
- Revenue (₹ Cr), Q2 FY26: 47.0
- Revenue (₹ Cr), Q4 FY26: 64.0
- Revenue (₹ Cr), Q2 FY27: 71.0
- Profit (₹ Cr), Q2 FY25: 1.0
- Profit (₹ Cr), Q4 FY25: 8.0
- Profit (₹ Cr), Q2 FY26: 6.0
- Profit (₹ Cr), Q4 FY26: 11.0
- Profit (₹ Cr), Q2 FY27: 11.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 20.0
- Revenue (₹ Cr), Q4 FY25: 37.0
- Revenue (₹ Cr), Q2 FY26: 47.0
- Revenue (₹ Cr), Q4 FY26: 64.0
- Revenue (₹ Cr), Q2 FY27: 71.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 1.0
- Profit (₹ Cr), Q4 FY25: 8.0
- Profit (₹ Cr), Q2 FY26: 6.0
- Profit (₹ Cr), Q4 FY26: 11.0
- Profit (₹ Cr), Q2 FY27: 11.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 5.0
- Net Profit Margin (%), Q4 FY25: 21.6
- Net Profit Margin (%), Q2 FY26: 12.8
- Net Profit Margin (%), Q4 FY26: 17.2
- Net Profit Margin (%), Q2 FY27: 15.5
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 71.0YoY +51% | 47.0 |
| Profit (₹ Cr) | 11.0YoY +83% | 6.0 |
| Net Profit Margin (%) | 15.5YoY +21% | 12.8 |
Why the growth didn't reach profit
The flat profit came despite a 10.9% revenue increase. StockFin reported that profit before tax actually fell 6.7% quarter-on-quarter, indicating margin pressure. According to an earnings presentation cited by earningsreport.io, this was due to a lower margin across the portfolio and a change in revenue mix.
Specifically, the mix shifted toward projects, products, and manufacturing (PP&M), which typically carry lower margins. Higher manufacturing, construction, and staff costs also weighed on profitability. This suggests the company is investing heavily to fulfill a growing order book.
The capacity bet for future margins
Management is betting that a major capacity expansion will solve these growing pains. A new integrated manufacturing facility in West Bengal, with a ₹25 crore capex, is on track for commissioning in Q4 FY27, as reported by SAHI.com.
Live Chart
· LTELEVATOR
(BSE)
ISIN: INE0TJ801010
This plant aims to increase installed capacity by 2.5 times, supporting peak revenue of ₹350-400 crore. The move is critical to handling large institutional orders and improving execution efficiency. Success here is key to converting top-line momentum into sustained profit growth.
Key Points
- Revenue growth of 51% YoY highlights strong execution, but quarterly profit was flat, revealing immediate margin pressure.
- The profit stall is attributed to a lower-margin revenue mix and rising input costs, as per an earnings presentation.
- The company's near-term outlook hinges on commissioning a new manufacturing facility in Q4 FY27 to ease capacity constraints.
Hexa Perspective
This quarter shows LT Elevator in a transitional phase. Acquisitions and strong demand are driving impressive revenue, but the business is yet to achieve operating leverage. The margin squeeze from a shifting mix and higher costs is a near-term reality. The investment case now rests on the timely commissioning of the new plant. If successful, it should provide the scale needed to improve profitability. Until then, investors are paying for growth potential, with the stock's valuation reflecting expectations for a future margin recovery.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.