LT Elevator (LTELEVATOR) Q4 FY26 Profit Jumps 83% on Record Revenue, But Cash Flow Lags
The elevator maker closed FY26 with a 103% revenue surge, yet a ballooning order book is straining its working capital and cash conversion.
LT Elevator's Q4 FY26 profit soared 83% sequentially on a 73% yearly revenue jump. However, a deep negative operating cash flow and surging receivables highlight the working capital stress of rapid growth.
For LT Elevator, FY26 was a year of explosive top-line growth, more than doubling its revenue. The final quarter delivered the crescendo, but the financials reveal a business sprinting to fulfill a massive order book, with cash struggling to keep pace.
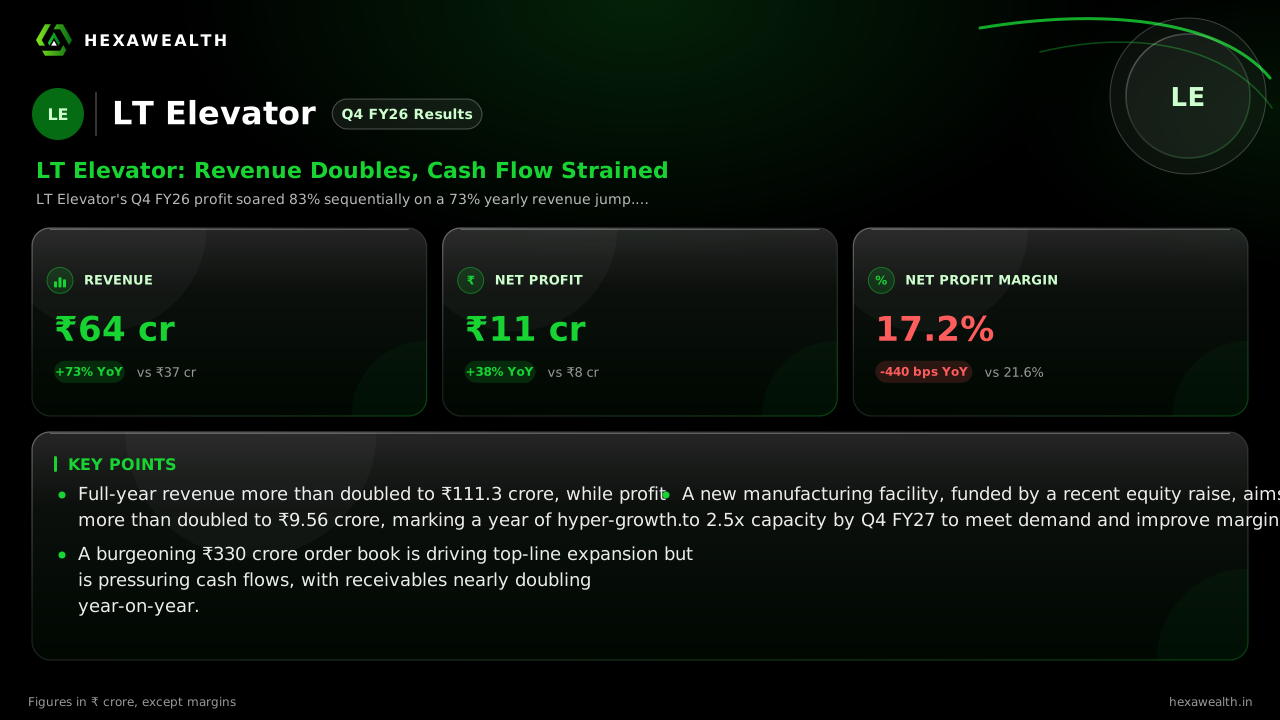
The March quarter revenue hit ₹64 crore, up 73% from a year ago. Profit followed, rising 37.5% year-on-year to ₹11 crore. Sequentially, the profit jump was sharper at 83%, recovering from a softer Q2. The full-year picture is even clearer: revenue crossed ₹111 crore, more than double FY25's figure, while profit more than doubled to ₹9.56 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 20.0
- Revenue (₹ Cr), Q4 FY25: 37.0
- Revenue (₹ Cr), Q2 FY26: 47.0
- Revenue (₹ Cr), Q4 FY26: 64.0
- Profit (₹ Cr), Q2 FY25: 1.0
- Profit (₹ Cr), Q4 FY25: 8.0
- Profit (₹ Cr), Q2 FY26: 6.0
- Profit (₹ Cr), Q4 FY26: 11.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 20.0
- Revenue (₹ Cr), Q4 FY25: 37.0
- Revenue (₹ Cr), Q2 FY26: 47.0
- Revenue (₹ Cr), Q4 FY26: 64.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 1.0
- Profit (₹ Cr), Q4 FY25: 8.0
- Profit (₹ Cr), Q2 FY26: 6.0
- Profit (₹ Cr), Q4 FY26: 11.0
Net Profit Margin
- Net Profit Margin, Q2 FY25: 5.0%
- Net Profit Margin, Q4 FY25: 21.6%
- Net Profit Margin, Q2 FY26: 12.8%
- Net Profit Margin, Q4 FY26: 17.2%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 64.0YoY +73% | 37.0 |
| Profit (₹ Cr) | 11.0YoY +38% | 8.0 |
| Net Profit Margin | 17.2%YoY -20% | 21.6% |
Why margins compressed on stellar sales
A year-on-year margin squeeze, down 440 basis points, tells the other half of the story. While revenue soared, total expenses doubled. Management, cited by Arthneeti, attributes this to a sales mix still weighted toward lower-margin business-to-government (B2G) projects, which involve slower payment cycles. The company is actively shifting toward higher-margin B2C home elevators to improve profitability.
The sequential margin recovery from Q2's 12.8% to 17.2% points to better operating leverage as revenue scaled. This improvement aligns with the 83% quarterly profit leap, driven by the revenue surge and a more favorable sales execution mix in the closing quarter.
The cash flow reality of growth
Beneath the profit growth lies a significant working capital build. Consolidated operating cash flow was deeply negative at -₹16.99 crore for FY26, as reported by ScanX. Trade receivables nearly doubled year-on-year to over ₹45 crore, reflecting the lag in collecting from government and large developer contracts.
Live Chart
· LTELEVATOR
(BSE)
ISIN: INE0TJ801010
This is the inherent tension in LT Elevator's model. Its combined order book, including subsidiary Ricardo, stands at roughly ₹320-330 crore, as per the Q4 earnings call. Winning large, slow-paying projects provides visibility but ties up capital. Management's stated solution is to grow the B2C segment, which brings advance payments and eases the strain.
Funding the capacity leap
To execute this backlog and capture future demand, a major capacity expansion is underway. The company has begun constructing a new integrated facility in West Bengal, with a capex of approximately ₹25 crore. According to SAHI, this plant aims to increase capacity by 2.5 times and support peak revenue of ₹350-400 crore when commissioned in Q4 FY27.
The funding path appears clear. In August 2026, the company completed a ₹42 crore preferential share issue. This, alongside the acquisition of a Korean subsidiary, subsequently turned its balance sheet net cash positive by September 2026, as noted by mCapital.
Key Points
- Full-year revenue more than doubled to ₹111.3 crore, while profit more than doubled to ₹9.56 crore, marking a year of hyper-growth.
- A burgeoning ₹330 crore order book is driving top-line expansion but is pressuring cash flows, with receivables nearly doubling year-on-year.
- A new manufacturing facility, funded by a recent equity raise, aims to 2.5x capacity by Q4 FY27 to meet demand and improve margin mix.
Hexa Perspective
The quarter confirms LT Elevator is successfully riding a wave of demand, with growth rates that are hard to ignore. The investment case now hinges on execution—converting a fat order book into cash profit without debilitating working capital stress.
The planned shift toward the B2C segment is critical. It promises better margins and faster cash conversion, which would resolve the current dichotomy of soaring profits and negative cash flow. Success here, coupled with timely capacity expansion, could sustain the high growth trajectory. The risk lies in any delay that prolongs the current cash-intensive growth phase.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.