Neetu Yoshi (NEETUYOSHI) Q2 FY27 Profit Stalls Despite 34% Revenue Jump
A sharp rise in raw material costs and delayed price recovery squeezed margins, leaving profit flat year-on-year despite strong top-line growth.
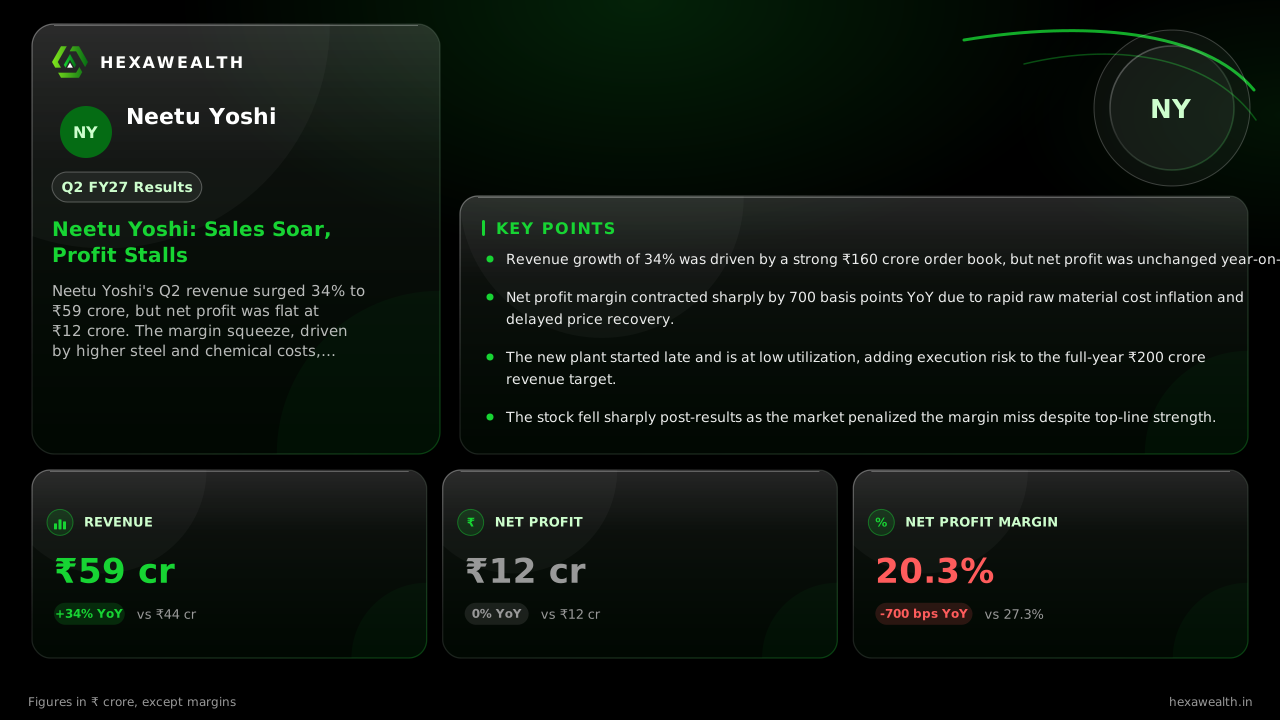
Neetu Yoshi's Q2 revenue surged 34% to ₹59 crore, but net profit was flat at ₹12 crore. The margin squeeze, driven by higher steel and chemical costs, highlights a key challenge as the company ramps up new capacity.
For a railway foundry specialist, a strong order book is only half the battle. Neetu Yoshi's September quarter showed the other half: revenue surged on the back of a ₹160 crore order book, but profit did not budge as input costs bit hard.
The numbers tell a story of growth without reward. Revenue climbed 34% year-on-year to ₹59 crore, yet net profit stayed flat at ₹12 crore. Sequentially, profit fell 8% even as revenue grew 9%, pushing the net profit margin down 380 basis points from the March quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q3 FY25 (Dec 2024): 16.2
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 35.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 44.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 54.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 59.0
- Profit (₹ Cr), Q3 FY25 (Dec 2024): 4.0
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 8.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 12.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 13.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 12.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q3 FY25 (Dec 2024): 16.2
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 35.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 44.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 54.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 59.0
Profit (₹ Cr)
- Profit (₹ Cr), Q3 FY25 (Dec 2024): 4.0
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 8.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 12.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 13.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 12.0
Net Profit Margin (%)
- Net Profit Margin (%), Q3 FY25 (Dec 2024): 25.0
- Net Profit Margin (%), Q4 FY25 (Mar 2025): 22.9
- Net Profit Margin (%), Q2 FY26 (Sep 2025): 27.3
- Net Profit Margin (%), Q4 FY26 (Mar 2026): 24.1
- Net Profit Margin (%), Q2 FY27 (Sep 2026): 20.3
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 59.0 | 54.0 |
| Profit (₹ Cr) | 12.0 | 13.0 |
| Net Profit Margin (%) | 20.3 | 24.1 |
Why the growth never reached the bottom line
Management, in its earnings call covered by MarketPing, pointed squarely at a cost-price mismatch. Steel and chemical prices rose faster than the company could recover them through price variation clauses (PVC). For Railway contracts, supplementary bills are raised only after documentation is complete, creating a lag. For private customers, price resets typically trail cost increases by one to two months.
This delay was severe. The investor presentation noted raw material expense jumped over 50% in the first half, consuming 55% of total income versus 47% a year ago. The result was a 700-basis-point year-on-year collapse in net profit margin.
A delayed ramp-up adds to the pressure
The new Haridwar plant, critical for future growth, started only in mid-September. Management said this delay cost about ₹10 crore in lost first-half revenue. The plant is running at just 20% efficiency, against a target of 50% for this fiscal year.
Live Chart
· NEETUYOSHI
(BSE)
ISIN: INE0UZO01024
With a debt-free balance sheet and about ₹15 crore in cash, funding the ₹10 crore track-section capex this year is not a concern. The challenge is execution. The company must sharply ramp up the new plant to meet its full-year revenue target of ₹200 crore, reiterated on the call.
The market's verdict on the squeeze
The stock reacted poorly to the margin story. According to MarketPing, shares fell 8.7% on the reaction day following the November 14 results, significantly underperforming the sector. The valuation at 27.7 times earnings trades at a 41% discount to the industry, reflecting skepticism about near-term profitability.
Key Points
- Revenue growth of 34% was driven by a strong ₹160 crore order book, but net profit was unchanged year-on-year.
- Net profit margin contracted sharply by 700 basis points YoY due to rapid raw material cost inflation and delayed price recovery.
- The new plant started late and is at low utilization, adding execution risk to the full-year ₹200 crore revenue target.
- The stock fell sharply post-results as the market penalized the margin miss despite top-line strength.
Hexa Perspective
The quarter frames Neetu Yoshi's near-term tension perfectly. Demand is not the issue, with a solid order book and Railway capex tailwinds. The test is whether operating execution can catch up.
Margins have two quarters to recover if input costs stabilize and PVC catch-up bills flow through. The new plant's ramp from 20% to 50% utilization is the lever for the second-half revenue surge management is banking on. Investors are weighing strong long-term visibility against near-term profitability pressures that have yet to ease.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.