Jubilant Industries (JUBLINDS) Q1 FY25 Profit Jumps 26% as Cost Cuts Offset Slow Sales
Jubilant Industries posted a 26% yearly profit rise in Q1 FY25, with lean initiatives driving margins higher despite modest revenue growth.
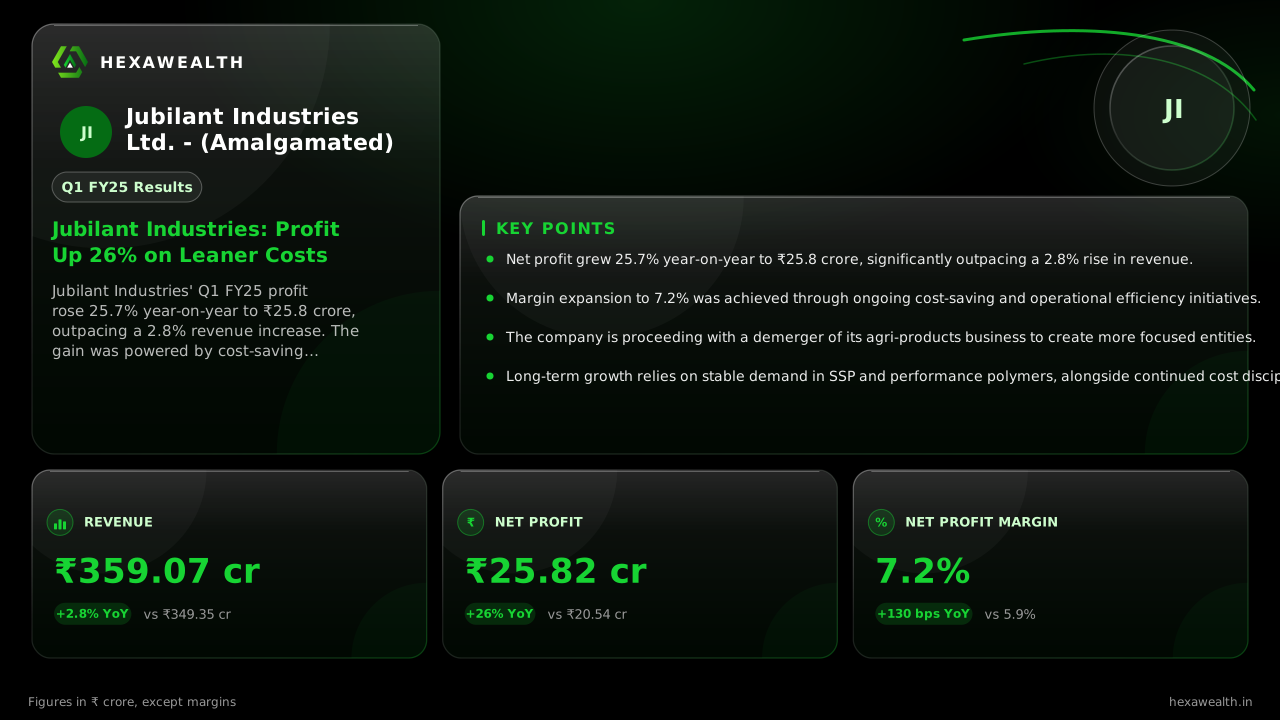
Jubilant Industries' Q1 FY25 profit rose 25.7% year-on-year to ₹25.8 crore, outpacing a 2.8% revenue increase. The gain was powered by cost-saving measures, with net profit margin expanding 130 basis points.
For a chemicals and agri-products maker, a quarter of steady sales often signals a wait for demand to catch up. Jubilant Industries turned that wait into a margin story, with profit climbing sharply on the back of disciplined cost control.
The numbers show a company leaning into efficiency. Revenue inched up 2.8% year-on-year to ₹359 crore, but net profit surged 25.7% to ₹25.8 crore. The net profit margin expanded to 7.2%, a 130-basis-point improvement from the same quarter last year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Jun 2023 (Q1 FY24): 349.35
- Revenue (₹ Cr), Sep 2023 (Q2 FY24): 312.10
- Revenue (₹ Cr), Dec 2023 (Q3 FY24): 292.71
- Revenue (₹ Cr), Mar 2024 (Q4 FY24): 300.49
- Revenue (₹ Cr), Jun 2024 (Q1 FY25): 359.07
- Profit (₹ Cr), Jun 2023 (Q1 FY24): 20.54
- Profit (₹ Cr), Sep 2023 (Q2 FY24): 8.57
- Profit (₹ Cr), Dec 2023 (Q3 FY24): -22.98
- Profit (₹ Cr), Mar 2024 (Q4 FY24): 22.01
- Profit (₹ Cr), Jun 2024 (Q1 FY25): 25.82
Revenue (₹ Cr)
- Revenue (₹ Cr), Jun 2023 (Q1 FY24): 349.35
- Revenue (₹ Cr), Sep 2023 (Q2 FY24): 312.10
- Revenue (₹ Cr), Dec 2023 (Q3 FY24): 292.71
- Revenue (₹ Cr), Mar 2024 (Q4 FY24): 300.49
- Revenue (₹ Cr), Jun 2024 (Q1 FY25): 359.07
Profit (₹ Cr)
- Profit (₹ Cr), Jun 2023 (Q1 FY24): 20.54
- Profit (₹ Cr), Sep 2023 (Q2 FY24): 8.57
- Profit (₹ Cr), Dec 2023 (Q3 FY24): -22.98
- Profit (₹ Cr), Mar 2024 (Q4 FY24): 22.01
- Profit (₹ Cr), Jun 2024 (Q1 FY25): 25.82
Net Profit Margin (%)
- Net Profit Margin (%), Jun 2023 (Q1 FY24): 5.9
- Net Profit Margin (%), Sep 2023 (Q2 FY24): 2.7
- Net Profit Margin (%), Dec 2023 (Q3 FY24): -7.9
- Net Profit Margin (%), Mar 2024 (Q4 FY24): 7.3
- Net Profit Margin (%), Jun 2024 (Q1 FY25): 7.2
| Metric | CurrentJun 2024 (Q1 FY25) | PreviousMar 2024 (Q4 FY24) |
|---|---|---|
| Revenue (₹ Cr) | 359.07 | 300.49 |
| Profit (₹ Cr) | 25.82 | 22.01 |
| Net Profit Margin (%) | 7.2 | 7.3 |
Where the Profit Came From
The profit jump was not driven by a sales boom. Instead, management's focus on cost optimisation, highlighted in a LinkedIn analysis of a group company, delivered the gains. These lean initiatives helped protect margins even as top-line growth remained modest.
This efficiency push is central to the outlook. The company, according to the same analysis, aims to sustain margins above 20% in its specialty chemicals business. For now, the broader performance polymers segment remains the steady profit driver.
The Road Ahead and a Strategic Split
Demand in key markets is sending mixed signals. The Single Super Phosphate (SSP) market in India, a core agri-product, is projected to grow steadily, supported by government subsidies. However, pricing in the agrochemical sector remains under pressure globally.
Live Chart
· JUBLINDS
(BSE)
ISIN: INE645L01011
A major strategic shift is also underway. The company has principally approved a plan to demerge its agri-products and sulphuric acid business. This move, detailed in a corporate presentation, aims to sharpen focus and could unlock value for both the high-margin polymers and the regional SSP powerhouse.
Key Points
- Net profit grew 25.7% year-on-year to ₹25.8 crore, significantly outpacing a 2.8% rise in revenue.
- Margin expansion to 7.2% was achieved through ongoing cost-saving and operational efficiency initiatives.
- The company is proceeding with a demerger of its agri-products business to create more focused entities.
- Long-term growth relies on stable demand in SSP and performance polymers, alongside continued cost discipline.
Hexa Perspective
The quarter demonstrates Jubilant Industries' ability to squeeze more profit from stable sales, a valuable skill in a competitive market. The success of its cost initiatives provided a clear buffer against sluggish revenue growth.
The planned demerger adds a new dimension. It promises sharper management focus and a cleaner investment story for both the specialty polymers and fertiliser businesses. Investors are now weighing the execution of this split against the company's ability to maintain its hard-won margin gains in both segments.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.