SFC Environmental Technologies (SFCTECH) Q1 FY27: Revenue Doubles But Profit Margin Implodes
The environmental tech firm's Q1 revenue jumped 98%, yet the net profit margin crashed to 1.1% from a full-year average of 19.9%.
SFC Environmental Technologies reported a 98% surge in Q1 FY27 revenue, but profits barely budged as margins collapsed. The quarter highlights the severe seasonality and working capital strain in its project-driven business.
For a company heading to market with a story of steady 20% profit margins, the first quarter of its public life delivered a stark reality check. SFC Environmental Technologies saw revenue nearly double year-on-year, but the bottom line barely moved, revealing a deep seasonal trough in its project execution cycle.
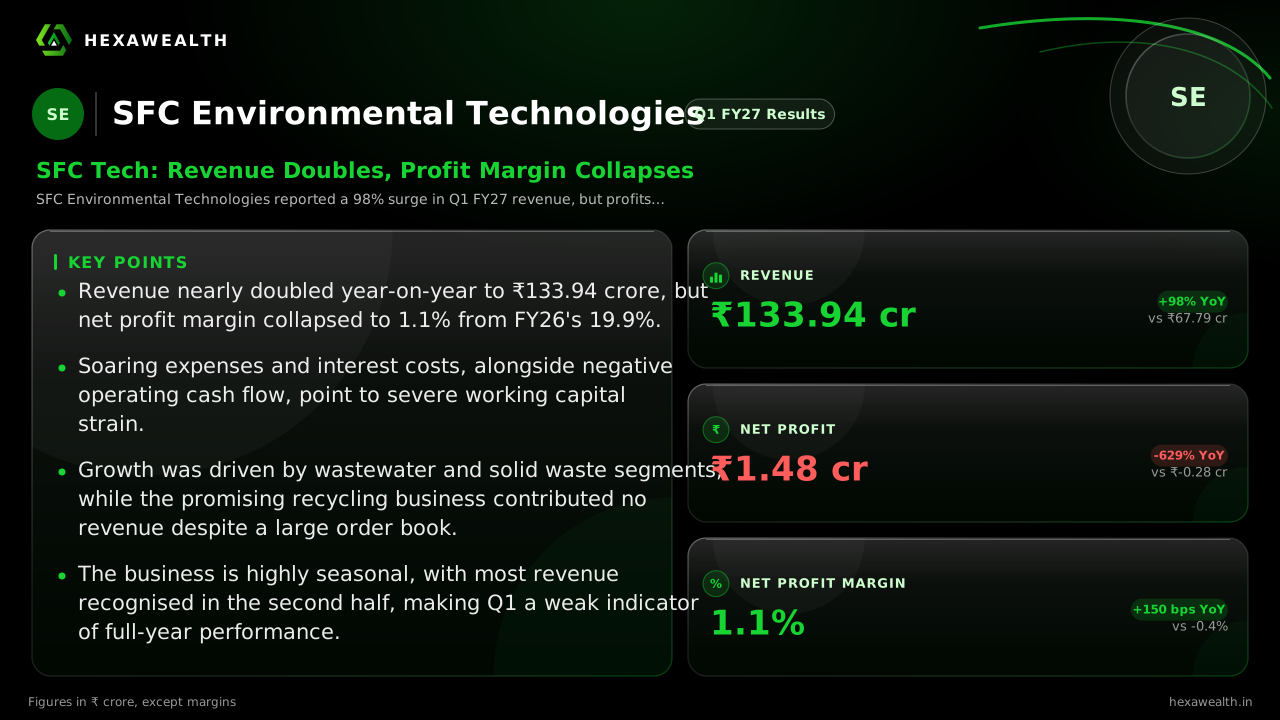
The numbers tell a story of two diverging lines. Revenue soared 97.6% to ₹133.94 crore, while profit after tax was a meagre ₹1.48 crore. The net profit margin collapsed to 1.1%, a staggering drop from the 19.9% average the company posted for the full year FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q1 FY26: 67.79
- Revenue (₹ Cr), Q1 FY27: 133.94
- Profit (₹ Cr), Q1 FY26: -0.28
- Profit (₹ Cr), Q1 FY27: 1.48
Revenue (₹ Cr)
- Revenue (₹ Cr), Q1 FY26: 67.79
- Revenue (₹ Cr), Q1 FY27: 133.94
Profit (₹ Cr)
- Profit (₹ Cr), Q1 FY26: -0.28
- Profit (₹ Cr), Q1 FY27: 1.48
Net Profit Margin
- Net Profit Margin, Q1 FY26: -0.4%
- Net Profit Margin, Q1 FY27: 1.1%
| Metric | CurrentQ1 FY27 | Same quarter LYQ1 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 133.94YoY +98% | 67.79 |
| Profit (₹ Cr) | 1.48YoY +629% | -0.28 |
| Net Profit Margin | 1.1%YoY +375% | -0.4% |
Why the profit vanished
Growth came at a steep cost. Total expenses surged 88.6%, nearly keeping pace with the top line. Interest costs jumped 84% as borrowings rose, hitting ₹204.77 crore by quarter-end. According to CNBC TV18, management plans to use IPO proceeds to repay ₹42 crore of debt, which could save ₹3-4 crore in annual interest.
The real pressure, however, is working capital. Operating cash flow was negative ₹21.34 crore, as reported by Ticker.finology. Money is tied up in receivables and project execution, a typical headache for firms dependent on government-linked engineering contracts.
A lopsided business mix
The revenue jump was driven by two core segments. Wastewater treatment contributed 48.5% and solid waste treatment 39.8%, as per a segment breakdown from Ticker.finology. Notably, the high-potential wastewater recycling segment, with a ₹561 crore order book, contributed zero recognised revenue, highlighting the lag between winning contracts and booking sales.
Live Chart
· SFCTECH
(BSE)
ISIN: INE0PKN01028
This uneven execution is baked into the model. Management told CNBC TV18 that 55-60% of annual revenue typically comes in the fourth quarter. The first quarter is hampered by monsoon delays and slower government payment cycles.
The market's cautious read
Analyst coverage is sparse post-IPO, but early reads are guarded. Brokerage SBI Securities assigned a 'Neutral' rating, citing the need to monitor execution and working capital efficiency. The valuation narrative, built on stable high-teens margins, now faces a reset as investors weigh whether Q1 was a seasonal trough or a sign of structural pressure.
The company's ₹1,656 crore order book offers visibility. Converting that backlog into profitable, cash-generating revenue is the challenge that will define its public-market credibility.
Key Points
- Revenue nearly doubled year-on-year to ₹133.94 crore, but net profit margin collapsed to 1.1% from FY26's 19.9%.
- Soaring expenses and interest costs, alongside negative operating cash flow, point to severe working capital strain.
- Growth was driven by wastewater and solid waste segments, while the promising recycling business contributed no revenue despite a large order book.
- The business is highly seasonal, with most revenue recognised in the second half, making Q1 a weak indicator of full-year performance.
Hexa Perspective
The quarter lays bare the core tension in SFC's story: strong top-line growth in a supported industry, versus an operationally intensive model that consumes cash. The 1.1% margin is likely a cyclical low, but the gap to the FY26 average is so wide that a return to mid-teens profitability this year seems ambitious.
Investors are now forced to price in execution risk, not just growth. The upcoming quarters will test if management can improve cash conversion while navigating government payment cycles. The order book provides a runway, but the margin of safety has narrowed considerably.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.