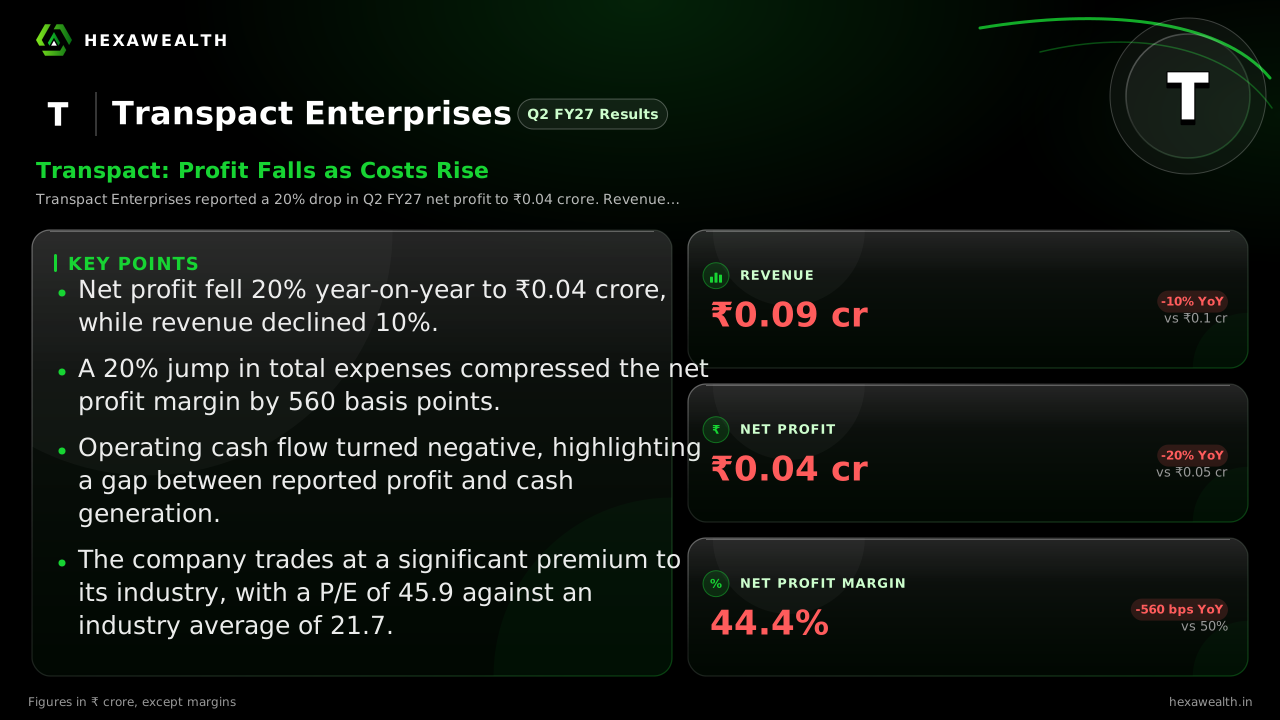
Transpact Enterprises (TRANSPACT) Q4 FY26 Profit Drops 20% Despite Higher Revenue
Transpact's Q4 FY26 net profit fell 20% year-on-year as a 50% jump in total expenses eroded a 12.5% revenue gain.
Transpact Enterprises closed FY26 with a mixed quarter. While annual revenue more than doubled, the March quarter saw profit decline due to sharply rising costs, squeezing the net margin by 1,810 basis points.
For Transpact Enterprises, a financial services and consulting firm, the final quarter of FY26 was a story of costs outpacing business. Revenue grew, but profitability took a significant hit, marking a sequential and yearly decline.
Revenue for the March quarter stood at ₹0.09 crore, up 12.5% from a year ago. Net profit, however, fell 20% to ₹0.04 crore. The net profit margin collapsed to 44.4%, down 1,810 basis points year-on-year and 560 points from the previous quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 0.00
- Revenue (₹ Cr), Q2 FY25: 0.00
- Revenue (₹ Cr), Q4 FY25: 0.08
- Revenue (₹ Cr), Q2 FY26: 0.10
- Revenue (₹ Cr), Q4 FY26: 0.09
- Profit (₹ Cr), Q4 FY24: -0.06
- Profit (₹ Cr), Q2 FY25: -0.05
- Profit (₹ Cr), Q4 FY25: 0.05
- Profit (₹ Cr), Q2 FY26: 0.05
- Profit (₹ Cr), Q4 FY26: 0.04
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 0.00
- Revenue (₹ Cr), Q2 FY25: 0.00
- Revenue (₹ Cr), Q4 FY25: 0.08
- Revenue (₹ Cr), Q2 FY26: 0.10
- Revenue (₹ Cr), Q4 FY26: 0.09
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: -0.06
- Profit (₹ Cr), Q2 FY25: -0.05
- Profit (₹ Cr), Q4 FY25: 0.05
- Profit (₹ Cr), Q2 FY26: 0.05
- Profit (₹ Cr), Q4 FY26: 0.04
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY24: -
- Net Profit Margin (%), Q2 FY25: -
- Net Profit Margin (%), Q4 FY25: 62.5
- Net Profit Margin (%), Q2 FY26: 50.0
- Net Profit Margin (%), Q4 FY26: 44.4
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 0.09YoY +12% | 0.08 |
| Profit (₹ Cr) | 0.04YoY -20% | 0.05 |
| Net Profit Margin (%) | 44.4YoY -29% | 62.5 |
Why Profitability Shrank
The sharp margin contraction was driven by a 50% year-on-year surge in total expenses, which rose to ₹0.06 crore. According to a report from ScanX.trade, this increase was primarily due to higher employee benefit expenses and other operating costs. Revenue growth could not keep pace with this cost inflation.
A Strong Full Year Masks Quarterly Pressure
Viewed over the full financial year, the picture is brighter but still reveals the Q4 strain. FY26 revenue jumped 118% to ₹0.18 crore, and profit soared 789% to ₹0.08 crore. Yet, the annual total expense line also grew by 148%, as noted in the annual analysis.
This suggests the cost pressures seen in Q4 were building through the year, even as the business scaled. The trailing twelve-month net profit margin is 33.3%, well below the Q4 FY26 level.
Live Chart
· TRANSPACT
(BSE)
ISIN: INE06YD01010
The Market's Muted Reaction
Despite the quarterly profit drop, the stock rose nearly 5% following the results announcement, as reported by The Economic Times. The company trades at a P/E of 48.4, a significant premium to its industry average of 22.0.
Analyst coverage remains sparse, with no major brokerages issuing ratings or target price changes after the results, according to data from Sharpely.in.
Key Points
- Q4 FY26 net profit fell 20% YoY to ₹0.04 crore despite a 12.5% rise in revenue.
- Total expenses surged 50% YoY, slashing the net profit margin by 1,810 basis points.
- For the full FY26, revenue doubled and profit increased nearly eightfold from a low base.
- The stock price gained post-results, but the company trades at a high valuation premium.
Hexa Perspective
The quarter underscores the challenge of maintaining profitability during a growth phase for this small-cap firm. While the full-year leap from loss to profit is notable, the Q4 cost surge raises questions about operating leverage.
With expenses growing faster than sales and a net margin that has fallen for two consecutive quarters, the path to sustained, quality earnings appears narrower. Investors are pricing in future growth, but the premium valuation leaves little room for further margin disappointment.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.