NTC Industries (NTCIND) Q2 FY27 Profit Dips Despite a Sharp 30% Revenue Jump
NTC Industries posted a 30% revenue surge in Q2 FY27, but net profit slipped as a one-time investment loss and reversed income masked strong underlying operations.
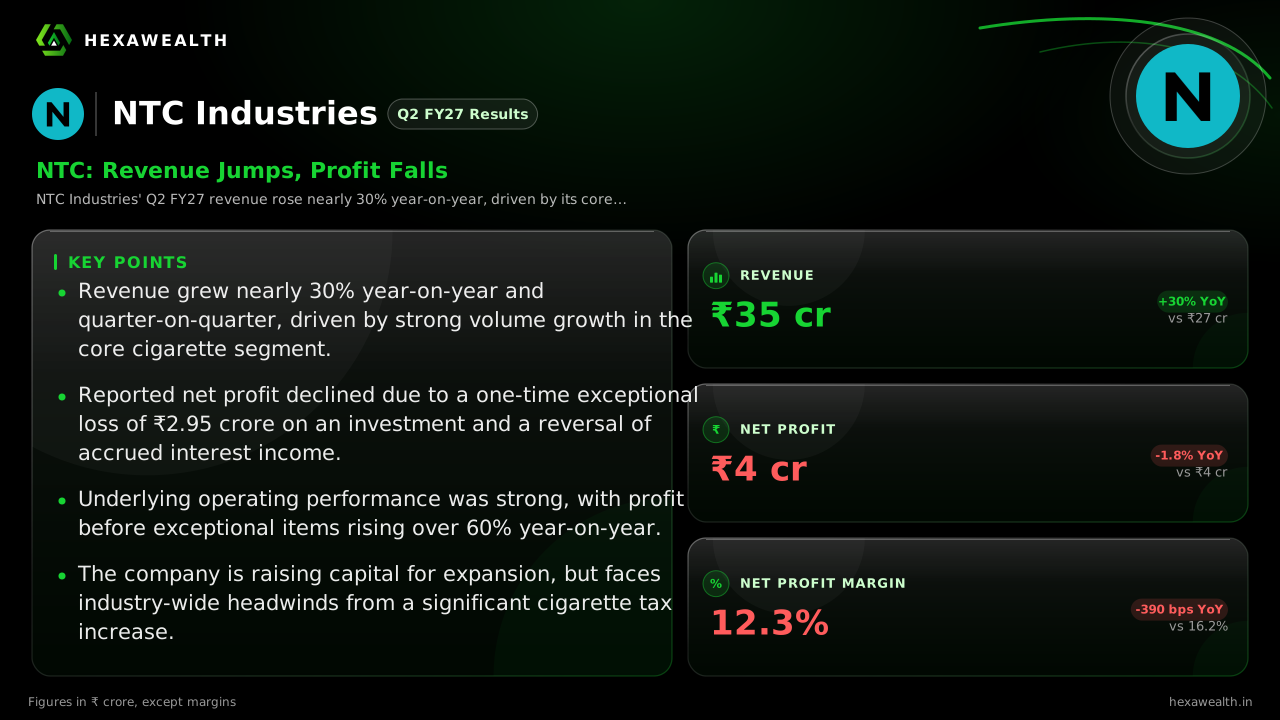
NTC Industries' Q2 FY27 revenue rose nearly 30% year-on-year, driven by its core cigarette business. However, net profit declined due to a significant exceptional loss on an investment and a reversal of accrued interest income.
For NTC Industries, a legacy cigarette maker, the September quarter presented a tale of two performances. The top line surged on robust volume growth, but the bottom line was weighed down by a balance sheet adjustment, revealing the tension between operational momentum and one-off financial hits.
The numbers show a clear divergence. Revenue climbed to ₹34.87 crore, up 29.9% from a year ago and 30.9% from the previous quarter. Yet, net profit contracted to ₹4.28 crore, down 1.8% year-on-year and a sharp 30.1% sequentially. The net profit margin compressed to 12.3%, a drop of 1070 basis points from Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 34.87YoY +30% | 26.63 | 26.85 |
| Profit (₹ Cr) | 4.28YoY -1.8% | 6.12 | 4.36 |
| Net Profit Margin (%) | 12.3YoY -24% | 23.0 | 16.2 |
Why the profit fell despite sales growth
The profit decline was not due to weak operations. According to a report by scanx.trade, profit before exceptional items actually rose 60.8% year-on-year to ₹6.39 crore. The reported profit was hit by two specific items. First, a ₹2.95 crore loss on the remeasurement of an investment in Creando Associates. Second, a reversal of ₹1.98 crore in accrued interest income. Together, these turned other income negative for the quarter.
This explains the dramatic quarter-on-quarter margin collapse. The prior quarter had benefited from positive other income of ₹3.16 crore, flattering its profit. The core cigarette business, however, drove the revenue growth with significant expansion in both volume and value terms, as noted by the same report.
The broader industry headwind
The strong volume growth comes against a challenging regulatory backdrop for the legal cigarette industry. A report on ITC by Motilal Oswal highlights a major GST 2.0 tax reset, estimating a 60-65% increase in cigarette taxes effective February 2026. This has led to calibrated price hikes and an expected volume decline across the sector as companies balance tax pass-through with illicit trade concerns.
NTC's ability to grow volumes in this environment points to its niche positioning. The company is also funding expansion, having sought shareholder approval for a ₹27.5 crore promoter warrant issue in August to fund manufacturing capacity growth, as per scanx.trade.
Cash flow and the path ahead
The company's financial position saw working capital adjustments. scanx.trade noted cash flow from operations was negative ₹0.89 crore for the half-year, though an improvement from the prior year. Funds were used for short-term loans and inventory build-up. The balance sheet remains conservative with a debt-to-equity ratio of 0.37.
The stock has significantly underperformed, down 34.7% over the past year to around ₹120. It trades at a P/E of 10.9, a 40% discount to the industry average, reflecting market caution over the sector's tax overhang and the company's recent profit volatility.
Key Points
- Revenue grew nearly 30% year-on-year and quarter-on-quarter, driven by strong volume growth in the core cigarette segment.
- Reported net profit declined due to a one-time exceptional loss of ₹2.95 crore on an investment and a reversal of accrued interest income.
- Underlying operating performance was strong, with profit before exceptional items rising over 60% year-on-year.
- The company is raising capital for expansion, but faces industry-wide headwinds from a significant cigarette tax increase.
Hexa Perspective
The quarter underscores a clean operational story clouded by a non-recurring financial charge. The core business is demonstrating volume resilience even as the broader legal cigarette industry navigates a disruptive tax change. For the momentum to sustain, NTC must continue its volume-led growth without further impairment surprises.
Investors are weighing the robust underlying profit growth against the sector's regulatory risks and the stock's deep valuation discount. The next few quarters will test whether volume gains can be maintained as industry-wide price increases take full effect.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.