Pritika Auto (PRITIKAUTO) Q2 FY27 Profit Slumps 33% Despite Strong Revenue Growth
The tractor parts maker delivered a 29% revenue surge in Q2 FY27, but raw material costs racing ahead of sales left profit sharply lower.
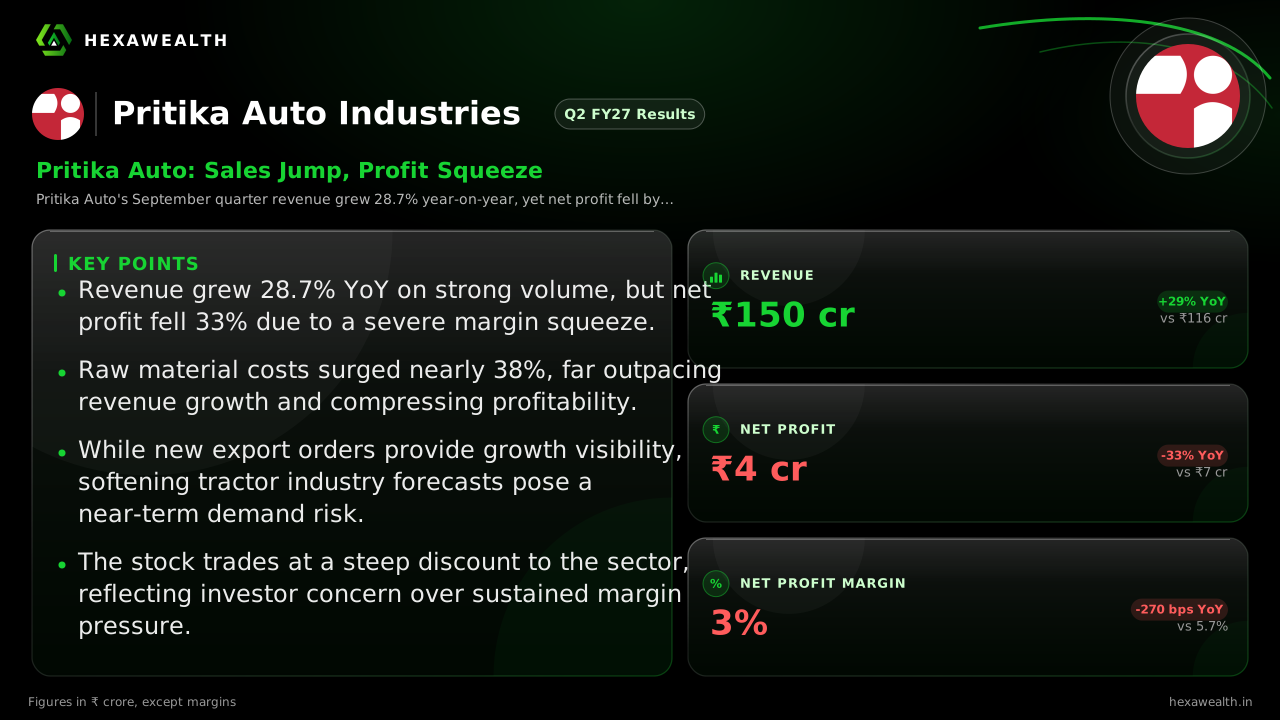
Pritika Auto's September quarter revenue grew 28.7% year-on-year, yet net profit fell by a third. The gap highlights a severe margin squeeze from input costs, even as order books and production volumes expand.
For a precision component supplier riding India's tractor demand, the top line is the easy part. Pritika Auto's challenge this quarter was keeping that sales growth from being consumed by costs—a test it narrowly passed on revenue but failed on profit.
The standalone numbers show the tension clearly. Revenue rose 28.7% year-on-year to ₹149.81 crore, yet net profit fell 33% to ₹4.43 crore. The net profit margin contracted 270 basis points to just 3%. Sequentially, profit dropped 37.7% even as revenue inched up 3.3%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 149.81YoY +29% | 144.97 | 116.44 |
| Profit (₹ Cr) | 4.43YoY -33% | 7.11 | 6.61 |
| Net Profit Margin | 3.0%YoY -47% | 4.9% | 5.7% |
Why the growth never reached the bottom line
A 34.9% surge in total consolidated expenditure, reported by Multibagg.ai, ran far ahead of sales. Raw material costs were the primary driver, with standalone material consumption up 37.8% year-on-year according to scanx.trade. Management cited elevated input costs and an evolving product mix for the pressure.
While employee costs and depreciation fell sharply from the prior quarter, those savings were swamped by the raw material bill. The result was a profit squeeze that overshadowed a solid 21.6% increase in production volume.
A mixed outlook from the field
Demand visibility remains strong. The company reported a new high-value export order from an Italian precision engineering firm and progress on its KION USA order. Yet, the broader tractor industry is turning cautious.
Key customer Mahindra & Mahindra has revised its FY27 industry outlook to flat, citing a weak monsoon and pressure on farm incomes. Analysts at Escorts Kubota now expect marginal single-digit degrowth for the full year, a notable shift from earlier expectations.
The market's verdict
Investors initially focused on the revenue beat. The stock gained 2.6% on results day to close at ₹15.46, noted MarketsMojo. The valuation remains deeply discounted, trading at a P/E of 8.3 against an industry average of 37.1.
This discount reflects persistent skepticism. The stock is down 31.5% over three years, underperforming significantly despite this quarter's sales strength. The market is pricing in the margin risk more than the volume growth.
Key Points
- Revenue grew 28.7% YoY on strong volume, but net profit fell 33% due to a severe margin squeeze.
- Raw material costs surged nearly 38%, far outpacing revenue growth and compressing profitability.
- While new export orders provide growth visibility, softening tractor industry forecasts pose a near-term demand risk.
- The stock trades at a steep discount to the sector, reflecting investor concern over sustained margin pressure.
Hexa Perspective
Pritika Auto's quarter is a classic case of top-line execution meeting a harsh cost reality. The 270-basis-point margin contraction year-on-year is the figure that matters, revealing how little operating leverage the current sales mix provides.
The path forward hinges on two forces: management's ability to pass on input costs or optimize them, and whether domestic tractor demand holds up against a weakening monsoon narrative. The sequential margin improvement from Q1 offers a faint hope, but with industry giants turning cautious, the cost-price scissors may not open soon. Investors are left weighing deep value against a profitability engine that is currently misfiring.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.