All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 11 November 20263 min read

Namo Ewaste (NAMOEWASTE) Q2 FY27's Revenue Jumps 40% But Profit Growth Falters on Rising Costs

The e-waste recycler posted strong top-line growth in Q2 FY27, but a sharp rise in interest and employee costs held back net profit expansion.

By Abhinav Swaroop, CFA, Chief Business Officer: Hexawealth · Created 11 November 2026

Namo Ewaste Management's Q2 FY27 revenue surged 40% year-on-year to ₹122 crore. However, profit grew at a slower 29% as interest costs tripled and employee expenses rose sharply, squeezing the net margin.

For Namo Ewaste Management, growth is not the problem. The formal recycler’s challenge is making its expanding top line pay, a tension laid bare in its September quarter. Revenue jumped 40% from a year ago, yet profit growth lagged behind as the costs of funding and running its ambitious expansion bit into margins.

The numbers show a business scaling fast but not yet efficiently. Revenue reached ₹122.5 crore, while net profit settled at ₹9.0 crore. The net profit margin compressed 60 basis points year-on-year to 7.4%, even as it improved sequentially from the March quarter.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Revenue & profitQ2 FY25 (Sep 2024) 67.00, Q4 FY25 (Mar 2025) 83.00, Q2 FY26 (Sep 2025) 87.32, Q4 FY26 (Mar 2026) 107.28, Q2 FY27 (Sep 2026) 122.47. Q2 FY25 (Sep 2024) 5.00, Q4 FY25 (Mar 2025) 3.12, Q2 FY26 (Sep 2025) 6.99, Q4 FY26 (Mar 2026) 7.36, Q2 FY27 (Sep 2026) 9.02050100150200Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Revenue (₹ Cr), Q2 FY25 (Sep 2024): 67.00
  • Revenue (₹ Cr), Q4 FY25 (Mar 2025): 83.00
  • Revenue (₹ Cr), Q2 FY26 (Sep 2025): 87.32
  • Revenue (₹ Cr), Q4 FY26 (Mar 2026): 107.28
  • Revenue (₹ Cr), Q2 FY27 (Sep 2026): 122.47
  • Profit (₹ Cr), Q2 FY25 (Sep 2024): 5.00
  • Profit (₹ Cr), Q4 FY25 (Mar 2025): 3.12
  • Profit (₹ Cr), Q2 FY26 (Sep 2025): 6.99
  • Profit (₹ Cr), Q4 FY26 (Mar 2026): 7.36
  • Profit (₹ Cr), Q2 FY27 (Sep 2026): 9.02

Revenue (₹ Cr)

Revenue (₹ Cr)Q2 FY25 (Sep 2024) 67.00, Q4 FY25 (Mar 2025) 83.00, Q2 FY26 (Sep 2025) 87.32, Q4 FY26 (Mar 2026) 107.28, Q2 FY27 (Sep 2026) 122.47050100150200Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Revenue (₹ Cr), Q2 FY25 (Sep 2024): 67.00
  • Revenue (₹ Cr), Q4 FY25 (Mar 2025): 83.00
  • Revenue (₹ Cr), Q2 FY26 (Sep 2025): 87.32
  • Revenue (₹ Cr), Q4 FY26 (Mar 2026): 107.28
  • Revenue (₹ Cr), Q2 FY27 (Sep 2026): 122.47

Profit (₹ Cr)

Profit (₹ Cr)Q2 FY25 (Sep 2024) 5.00, Q4 FY25 (Mar 2025) 3.12, Q2 FY26 (Sep 2025) 6.99, Q4 FY26 (Mar 2026) 7.36, Q2 FY27 (Sep 2026) 9.0205101520Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Profit (₹ Cr), Q2 FY25 (Sep 2024): 5.00
  • Profit (₹ Cr), Q4 FY25 (Mar 2025): 3.12
  • Profit (₹ Cr), Q2 FY26 (Sep 2025): 6.99
  • Profit (₹ Cr), Q4 FY26 (Mar 2026): 7.36
  • Profit (₹ Cr), Q2 FY27 (Sep 2026): 9.02

Net Profit Margin (%)

Net Profit Margin (%)Q2 FY25 (Sep 2024) 7.5, Q4 FY25 (Mar 2025) 3.8, Q2 FY26 (Sep 2025) 8.0, Q4 FY26 (Mar 2026) 6.9, Q2 FY27 (Sep 2026) 7.40%5%10%15%20%Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Net Profit Margin (%), Q2 FY25 (Sep 2024): 7.5
  • Net Profit Margin (%), Q4 FY25 (Mar 2025): 3.8
  • Net Profit Margin (%), Q2 FY26 (Sep 2025): 8.0
  • Net Profit Margin (%), Q4 FY26 (Mar 2026): 6.9
  • Net Profit Margin (%), Q2 FY27 (Sep 2026): 7.4
MetricCurrentQ2 FY27 (Sep 2026)PreviousQ4 FY26 (Mar 2026)
Revenue (₹ Cr)
122.47
107.28
Profit (₹ Cr)
9.02
7.36
Net Profit Margin (%)
7.4
6.9

Why profit trailed revenue

Growth came from ramping up collection networks and processing more material, as noted by Sector Alpha. But costs rose faster. Employee expenses soared 55% year-on-year, likely tied to staffing new facilities. More critically, interest costs surged over 300% to ₹2.05 crore.

This spike is linked to debt for a major new project. Management plans a ₹60 crore hydrometallurgy plant, as reported by Alfafinder, to extract critical minerals from battery waste. While debt-to-equity remains a low 0.03, the quarterly interest burden has jumped as this expansion financing kicks in.

The expansion balancing act

Namo Ewaste is betting on three near-term projects: a new Hyderabad e-waste plant, a pilot hydrometallurgy unit, and the large commercial plant. The goal, per a May 2026 call cited by Newboard, is to roughly double revenue this year to about ₹400 crore. Profit is meant to follow, with a target PAT margin of 7-10% over the next few years.

Live Chart

· NAMOEWASTE

(BSE)

ISIN: INE08NZ01012

The quarter’s margin pressure shows how hard that balance is. Foreign institutional investors seem wary, having cut their stake for four consecutive quarters to zero, according to Sector Alpha. The stock, however, has had a strong run, up nearly 69% over the past year.

Key Points

  • Revenue growth of 40.3% YoY significantly outpaced profit growth of 29.0%, indicating margin pressure from expansion costs.
  • Interest expense tripled year-on-year, linked to debt financing for a planned ₹60 crore hydrometallurgy plant, a key future growth driver.
  • Management maintains an aggressive FY27 revenue target of ~₹400 crore, aiming to double from the FY26 base, with profitability hinging on successful project execution.

Hexa Perspective

The quarter confirms Namo Ewaste’s ability to capture volume in a growing formal recycling market. The concern is the cost of that growth. The margin squeeze from rising interest and employee costs is a direct result of its capital-intensive expansion strategy.

The next few quarters will test whether new capacities—especially in high-margin battery recycling—can ramp up quickly enough to improve profitability. Until then, investors are paying a premium for potential, with the stock trading at a P/E of 53.4, well above the industry average of 35.9.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
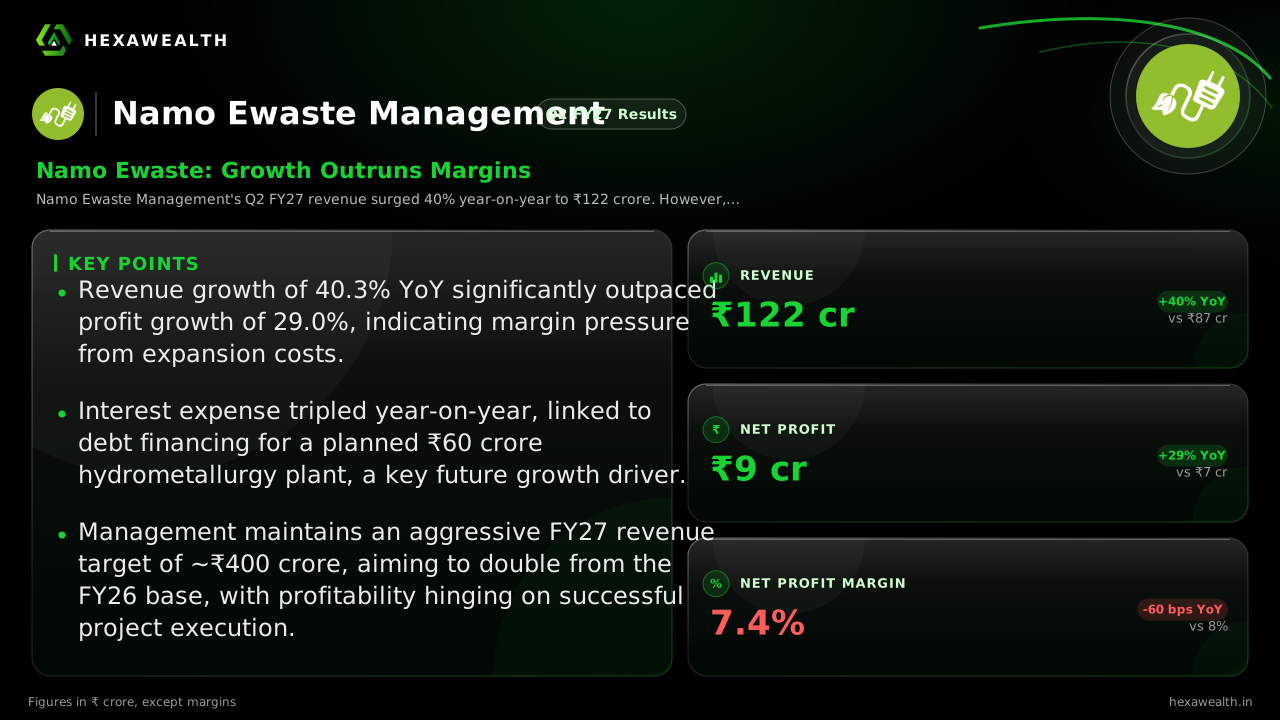
Namo Ewaste Management (NAMOEWASTE) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Namo Ewaste Management's Q2 FY27 results?
Namo Ewaste Management reported revenue of ₹122.47 crore and a net profit of ₹9.02 crore for the quarter ended September 2026. This represents a year-on-year growth of 40.3% in revenue and 29.0% in profit. The net profit margin for the quarter was 7.4%.
Why did Namo Ewaste Management's net profit margin decline YoY despite strong revenue growth?
Namo Ewaste's net profit margin fell 60 basis points year-on-year to 7.4% because costs rose faster than sales. Interest expense surged over 300% to ₹2.05 crore, linked to project financing, and employee costs jumped 55%. This expansion-related spending squeezed profitability even as revenue grew 40%.
What caused the 303% surge in interest cost for Namo Ewaste in Q2 FY27?
The 303% year-on-year surge in interest cost to ₹2.05 crore is tied to debt raised for capacity expansion. According to reports, the company is financing a planned ₹60 crore hydrometallurgy plant to extract critical minerals from battery waste, which has increased its quarterly interest burden.
What explains the sharp 931% QoQ jump in other income for Namo Ewaste?
Namo Ewaste's other income rose 931% quarter-on-quarter to ₹1.45 crore in Q2 FY27. While the specific source isn't detailed in the results, such a large, one-off jump is typically non-operational and may include items like foreign exchange gains or one-time subsidies. It is not considered a sustainable part of core earnings.
Why did employee costs for Namo Ewaste rise 55% YoY in Q2 FY27?
Employee costs rose 55% year-on-year to ₹5.52 crore, significantly outpacing revenue growth. This is likely due to hiring and staffing for new facilities, including the upcoming Hyderabad e-waste plant and expansion of technical teams for its battery recycling and hydrometallurgy projects.
What is the nature of the debt that caused Namo Ewaste's interest expense to triple?
The debt is primarily for funding a significant capacity expansion. Namo Ewaste is planning a ₹60 crore hydrometallurgy plant, as reported by Alfafinder, and has confirmed eligibility for a government subsidy under the National Critical Mineral Mission. The drawn-down debt for this and other projects led to the tripling of quarterly interest expense.
Is Namo Ewaste Management undertaking significant capacity expansion?
Yes, Namo Ewaste is in a major expansion phase. Key projects include a 25,000 MT Hyderabad e-waste plant, a pilot hydrometallurgy unit by end-2026, and a commercial ₹60 crore hydrometallurgy plant. Funding for the large plant is planned via debt, for which the company has secured subsidy eligibility.
What guidance did Namo Ewaste management provide for FY27?
On a May 2026 earnings call cited by Newboard, management targeted revenue of about ₹400 crore for FY27, roughly double the FY26 base, split evenly between batteries and e-waste. They aimed for a blended EBITDA margin of 17-20% and a net profit margin of 7-10% over the next three to four years.
Did Namo Ewaste Management's Q2 FY27 results beat analyst estimates?
The research snippets do not provide specific consensus analyst estimates for Q2 FY27 revenue and profit to determine a beat or miss. The results show the company delivered strong top-line growth of 40.3% but faced margin pressure that held back profit expansion.
Have FIIs increased or decreased their stake in Namo Ewaste Management recently?
Foreign Institutional Investors (FIIs) have consistently decreased their stake. According to Sector Alpha, FIIs cut their holding for four consecutive quarters, reducing it from 3.5% to 0% by the September 2026 quarter. This suggests institutional caution despite the company's growth narrative.
How did Namo Ewaste Management's stock price react to the Q2 FY27 results?
Specific post-results reaction data isn't available in the research. However, the stock has performed strongly over the past year, with a 68.8% return from November 2025 to November 2026. The company also issued a clarification in September 2026 stating a significant price move was market-driven with no undisclosed information.
Namo eWaste Management Q2 net profit
Namo Ewaste Management's net profit for the quarter ended September 2026 (Q2 FY27) was ₹9.02 crore. This marks a 29.0% increase from the ₹6.99 crore profit reported in the same quarter last year (Q2 FY26).
Namo eWaste Management September quarter profit
Namo Ewaste Management's profit for the September 2026 quarter (Q2 FY27) was ₹9.02 crore. This is up 29.0% from the ₹6.99 crore earned in the September 2025 quarter. The company's revenue for the period was ₹122.47 crore.