Sahara Maritime (SMARITIME) Q2 FY27 Profit Slips 75% Despite Strong Revenue Growth
The logistics firm's Q2 FY27 revenue jumped 68% year-on-year, but a sharp rise in expenses and working capital pressure cut quarterly profit by three-quarters.
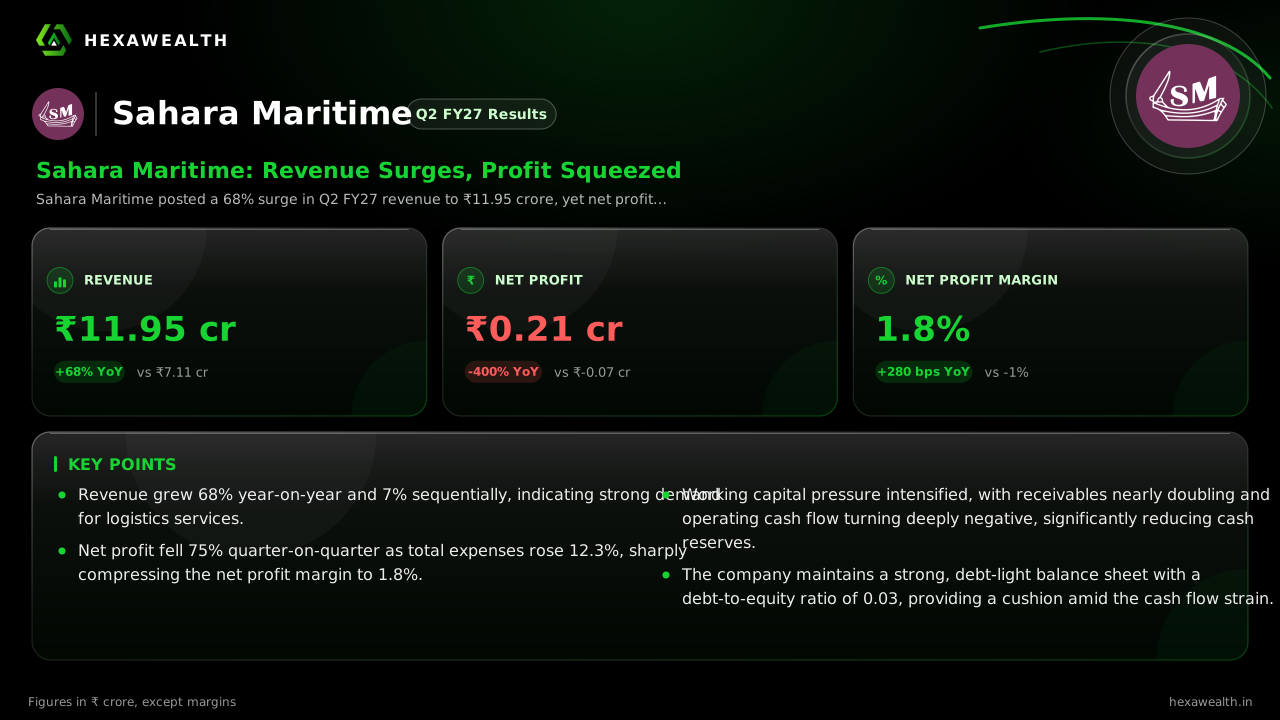
Sahara Maritime posted a 68% surge in Q2 FY27 revenue to ₹11.95 crore, yet net profit fell 75% sequentially to ₹0.21 crore. The quarter highlights a margin squeeze as costs rose faster than sales, while receivables ballooned, draining cash.
For Sahara Maritime, a logistics player navigating a recovering freight market, the September quarter delivered a clear split. Top-line momentum surged, but profitability took a severe hit as costs and cash flow pressures mounted.
The numbers tell the story of two diverging trends. Revenue for Q2 FY27 rose to ₹11.95 crore, up 68% from a year ago and 7% from the prior quarter. Yet, net profit fell sharply to ₹0.21 crore, a 75% drop sequentially from ₹0.84 crore in Q4 FY26. The net profit margin contracted by 570 basis points to just 1.8%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 7.79
- Revenue (₹ Cr), Q4 FY25: 17.45
- Revenue (₹ Cr), Q2 FY26: 7.11
- Revenue (₹ Cr), Q4 FY26: 11.14
- Revenue (₹ Cr), Q2 FY27: 11.95
- Profit (₹ Cr), Q2 FY25: -0.34
- Profit (₹ Cr), Q4 FY25: 0.57
- Profit (₹ Cr), Q2 FY26: -0.07
- Profit (₹ Cr), Q4 FY26: 0.84
- Profit (₹ Cr), Q2 FY27: 0.21
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 7.79
- Revenue (₹ Cr), Q4 FY25: 17.45
- Revenue (₹ Cr), Q2 FY26: 7.11
- Revenue (₹ Cr), Q4 FY26: 11.14
- Revenue (₹ Cr), Q2 FY27: 11.95
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: -0.34
- Profit (₹ Cr), Q4 FY25: 0.57
- Profit (₹ Cr), Q2 FY26: -0.07
- Profit (₹ Cr), Q4 FY26: 0.84
- Profit (₹ Cr), Q2 FY27: 0.21
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: -4.4
- Net Profit Margin (%), Q4 FY25: 3.3
- Net Profit Margin (%), Q2 FY26: -1.0
- Net Profit Margin (%), Q4 FY26: 7.5
- Net Profit Margin (%), Q2 FY27: 1.8
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 11.95YoY +68% | 7.11 |
| Profit (₹ Cr) | 0.21YoY +400% | -0.07 |
| Net Profit Margin (%) | 1.8YoY +280% | -1.0 |
Where the growth went
The 68% year-on-year revenue jump, as reported by StockFin.ai, reflects improved operational activity. However, total expenses grew even faster, rising 12.3% quarter-on-quarter to outpace the 7% revenue gain. This suggests the company absorbed higher freight and handling costs to secure business, a common pressure in a competitive logistics environment.
The margin squeeze was compounded by a complete absence of other income, which contributed ₹0.05 crore in the previous quarter. This stripped away a small but meaningful buffer for the bottom line.
The cash cost of sales
Strong sales came at a steep working capital price. According to a report from mcapital.in, trade receivables nearly doubled to ₹11.18 crore by September 2026 from ₹5.99 crore in March. This surge led to a negative operating cash flow of ₹4.05 crore for the half-year, draining the cash balance from ₹6.94 crore to ₹2.78 crore.
Live Chart
· SMARITIME
(BSE)
ISIN: INE0PSJ01011
The company is effectively financing its customers' cycles, a model that boosts revenue but strains liquidity. Until collection efficiency improves, this cash burn will limit financial flexibility despite the profit turnaround from last year's loss.
Key Points
- Revenue grew 68% year-on-year and 7% sequentially, indicating strong demand for logistics services.
- Net profit fell 75% quarter-on-quarter as total expenses rose 12.3%, sharply compressing the net profit margin to 1.8%.
- Working capital pressure intensified, with receivables nearly doubling and operating cash flow turning deeply negative, significantly reducing cash reserves.
- The company maintains a strong, debt-light balance sheet with a debt-to-equity ratio of 0.03, providing a cushion amid the cash flow strain.
Hexa Perspective
The quarter presents a classic growth-versus-profitability trade-off. Sahara Maritime is successfully capturing higher sales volumes in a recovering market, but it has not yet translated that into stable earnings. The severe margin contraction and cash outflow suggest the growth is neither high-quality nor fully under its control.
The path forward hinges on two factors: the ability to pass on rising freight costs to customers and a material improvement in receivable collections. With a lean balance sheet, the company has time to adjust, but the current model of growth funded by its own cash is unsustainable for the long term.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.