Davin Sons Retail (DAVIN) Q2 FY27 Profit Rises 55% Despite a 26% Revenue Drop
Davin Sons Retail's Q2 FY27 saw a sharp revenue decline, but a rebound in profit margin tells a story of cost cuts and a business in transition.
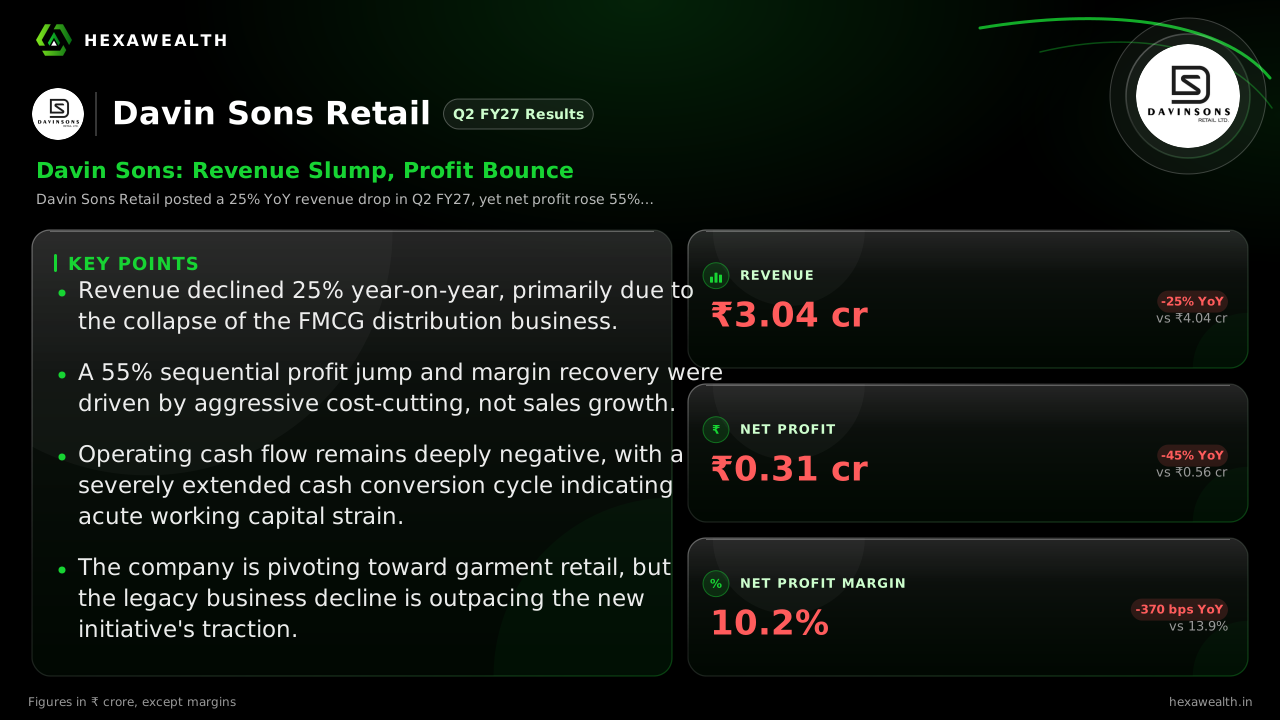
Davin Sons Retail posted a 25% YoY revenue drop in Q2 FY27, yet net profit rose 55% sequentially. The quarter highlights the company's pivot from a collapsed FMCG distribution segment and the strain of a ballooning cash conversion cycle.
For Davin Sons Retail, the September quarter was a study in contrasts. The company's long-running pivot from a struggling FMCG distributor to a garment manufacturer-retailer continued, but the legacy business left a deep mark on the top line. Revenue fell sharply, yet a tighter grip on costs delivered a surprising sequential profit bounce.
The numbers show a business in transition. Revenue of ₹3.04 crore was down 25% from a year ago and 26% from the prior quarter. Net profit, however, rose 55% sequentially to ₹0.31 crore, lifting the net profit margin to 10.2% from a low 4.9% in Q4 FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 6.28
- Revenue (₹ Cr), Q4 FY25: 7.24
- Revenue (₹ Cr), Q2 FY26: 4.04
- Revenue (₹ Cr), Q4 FY26: 4.12
- Revenue (₹ Cr), Q2 FY27: 3.04
- Profit (₹ Cr), Q2 FY25: 0.74
- Profit (₹ Cr), Q4 FY25: 0.93
- Profit (₹ Cr), Q2 FY26: 0.56
- Profit (₹ Cr), Q4 FY26: 0.20
- Profit (₹ Cr), Q2 FY27: 0.31
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 6.28
- Revenue (₹ Cr), Q4 FY25: 7.24
- Revenue (₹ Cr), Q2 FY26: 4.04
- Revenue (₹ Cr), Q4 FY26: 4.12
- Revenue (₹ Cr), Q2 FY27: 3.04
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 0.74
- Profit (₹ Cr), Q4 FY25: 0.93
- Profit (₹ Cr), Q2 FY26: 0.56
- Profit (₹ Cr), Q4 FY26: 0.20
- Profit (₹ Cr), Q2 FY27: 0.31
Net Profit Margin
- Net Profit Margin, Q2 FY25: 11.8%
- Net Profit Margin, Q4 FY25: 12.8%
- Net Profit Margin, Q2 FY26: 13.9%
- Net Profit Margin, Q4 FY26: 4.9%
- Net Profit Margin, Q2 FY27: 10.2%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Period | Sep 2026 | Sep 2025 |
| Revenue (₹ Cr) | 3.04YoY -25% | 4.04 |
| Profit (₹ Cr) | 0.31YoY -45% | 0.56 |
| Net Profit Margin | 10.2%YoY -27% | 13.9% |
The Collapsed Engine
The primary driver of the revenue slump was the near-total collapse of the FMCG distribution segment. Research from Scanx.trade shows this segment's revenue fell nearly 90% year-on-year in FY26. This drastic reduction in a previously significant revenue stream explains the bulk of the top-line decline, leaving the garment manufacturing business to carry the load.
A Margin Rebound Built on Austerity
Despite lower sales, profit improved because the company cut deeper. Total expenses fell 32% quarter-on-quarter, with purchases of stock-in-trade down sharply. The sequential margin recovery of 530 basis points was a relief from the severely pinched 4.9% margin of the March quarter. However, costs are rising in other areas. Depreciation more than doubled year-on-year, and employee expenses increased, according to a report by Multibagg.ai.
The Cash Flow Conundrum
Profitability on paper is not translating into cash. The company reported a net cash outflow of ₹92.47 lakh from operations for the half-year, per Multibagg.ai. This points to severe working capital stress. Data from Cruxal shows the cash conversion cycle stretched to 752 days in FY26, meaning money is tied up for over two years before turning back into cash.
Live Chart
· DAVIN
(BSE)
ISIN: INE0Q2L01013
Key Points
- Revenue declined 25% year-on-year, primarily due to the collapse of the FMCG distribution business.
- A 55% sequential profit jump and margin recovery were driven by aggressive cost-cutting, not sales growth.
- Operating cash flow remains deeply negative, with a severely extended cash conversion cycle indicating acute working capital strain.
- The company is pivoting toward garment retail, but the legacy business decline is outpacing the new initiative's traction.
Hexa Perspective
The quarter underscores a business caught between two models. The old FMCG engine has stalled before the new retail focus can provide meaningful scale. While cost discipline has provided a temporary profit cushion, the path to sustainable growth is unclear. The ballooning working capital cycle is a critical red flag, suggesting operational inefficiency that could strain the lean balance sheet. Investors are weighing whether the garment business can gain scale fast enough to offset the legacy decline, a turnaround that appears quarters away at best.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.