Davin Sons Retail (DAVIN) Q4 FY26 Profit Plunges 78% as FMCG Business Collapses
The garment retailer’s quarterly revenue fell 43% year-on-year, with a sharp decline in its FMCG distribution segment driving the steep drop in profitability.
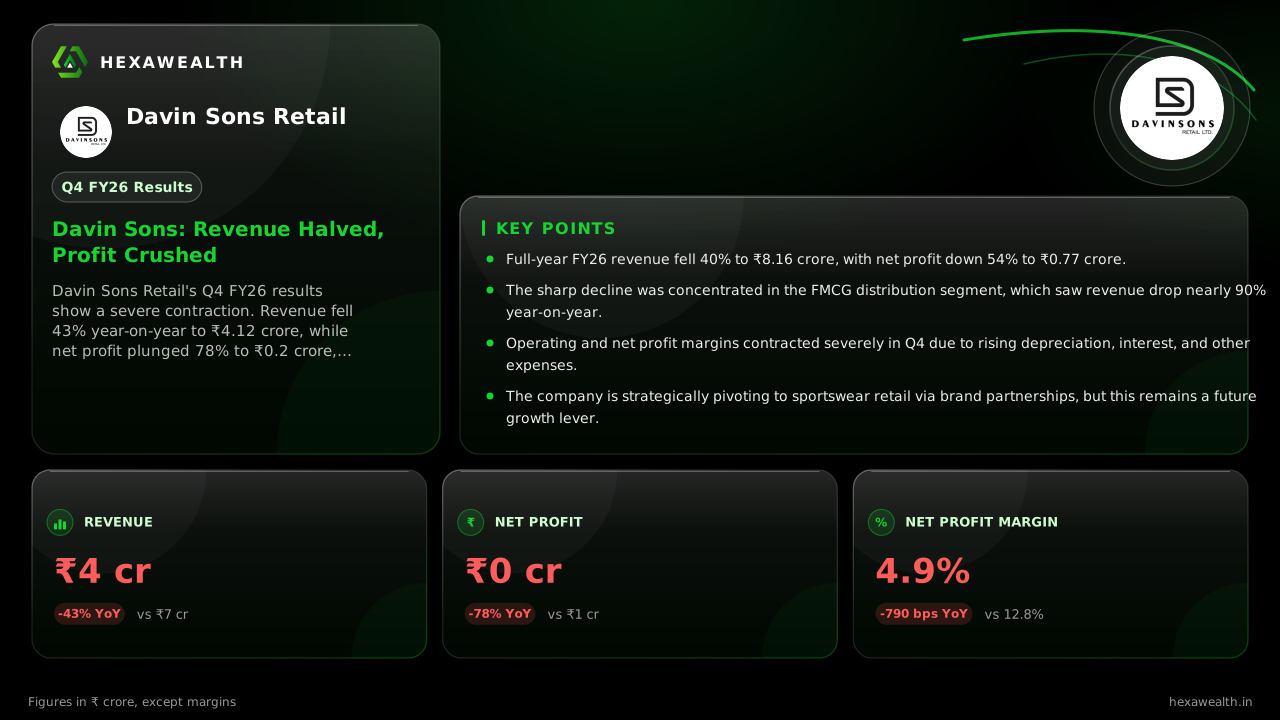
Davin Sons Retail's Q4 FY26 results show a severe contraction. Revenue fell 43% year-on-year to ₹4.12 crore, while net profit plunged 78% to ₹0.2 crore, as its FMCG distribution business saw a dramatic slowdown.
For Davin Sons Retail, the pivot from a backend manufacturer to a front-end retailer has hit a severe roadblock. The company’s March quarter results reveal a business in steep contraction, with revenue nearly halving and profits evaporating as its core FMCG distribution segment collapsed.
The numbers tell a story of broad-based decline. Revenue for Q4 FY26 fell 43% year-on-year to ₹4.12 crore. Net profit plunged 78% to just ₹0.2 crore, with the net profit margin shrinking to 4.9% from 12.8% a year ago. Sequentially, a 2% revenue uptick was overwhelmed by a 64% profit drop.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 8.98
- Revenue (₹ Cr), Q2 FY25: 6.28
- Revenue (₹ Cr), Q4 FY25: 7.24
- Revenue (₹ Cr), Q2 FY26: 4.04
- Revenue (₹ Cr), Q4 FY26: 4.12
- Profit (₹ Cr), Q4 FY24: 0.85
- Profit (₹ Cr), Q2 FY25: 0.74
- Profit (₹ Cr), Q4 FY25: 0.93
- Profit (₹ Cr), Q2 FY26: 0.56
- Profit (₹ Cr), Q4 FY26: 0.20
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 8.98
- Revenue (₹ Cr), Q2 FY25: 6.28
- Revenue (₹ Cr), Q4 FY25: 7.24
- Revenue (₹ Cr), Q2 FY26: 4.04
- Revenue (₹ Cr), Q4 FY26: 4.12
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 0.85
- Profit (₹ Cr), Q2 FY25: 0.74
- Profit (₹ Cr), Q4 FY25: 0.93
- Profit (₹ Cr), Q2 FY26: 0.56
- Profit (₹ Cr), Q4 FY26: 0.20
Net Profit Margin
- Net Profit Margin, Q4 FY24: 9.5%
- Net Profit Margin, Q2 FY25: 11.8%
- Net Profit Margin, Q4 FY25: 12.8%
- Net Profit Margin, Q2 FY26: 13.9%
- Net Profit Margin, Q4 FY26: 4.9%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 4.12YoY -43% | 7.24 |
| Profit (₹ Cr) | 0.20YoY -78% | 0.93 |
| Net Profit Margin | 4.9%YoY -62% | 12.8% |
The FMCG Segment Vanishes
Research from Scanx.trade shows the primary driver was a near-total collapse in the FMCG distribution business. Revenue from this segment fell to ₹79.15 lakh for the full year FY26 from ₹741.94 lakh in FY25. This drastic reduction in a previously significant revenue stream explains the bulk of the top-line decline.
Why Margins Caved In
Despite slightly higher revenue, the quarter’s profitability was crushed. Total expenses rose 21% sequentially, with depreciation more than doubling to ₹0.19 crore, likely from recent asset additions. Interest costs also tripled. The operating profit margin, as reported by Cruxal, halved to 11.2% from 22.8% in the previous quarter.
A Pivot in Progress
The company’s long-term strategy involves a shift toward organized sportswear retail. According to SGI Europe, Davin Sons has signed preliminary MOUs with brands like Skechers and Adidas to open multi-brand outlets. This pivot aims to replace the fading FMCG distribution, but it is a future prospect, not a current revenue source.
Live Chart
· DAVIN
(BSE)
ISIN: INE0Q2L01013
The financial strain is visible in cash flows. Data from Cruxal shows net cash used in operations was ₹3.84 crore for FY26. While the balance sheet remains lean on debt, the cash conversion cycle stretched to 752 days, indicating severe working capital inefficiency.
Key Points
- Full-year FY26 revenue fell 40% to ₹8.16 crore, with net profit down 54% to ₹0.77 crore.
- The sharp decline was concentrated in the FMCG distribution segment, which saw revenue drop nearly 90% year-on-year.
- Operating and net profit margins contracted severely in Q4 due to rising depreciation, interest, and other expenses.
- The company is strategically pivoting to sportswear retail via brand partnerships, but this remains a future growth lever.
Hexa Perspective
The quarter underscores the risks of a transitional business model. The old FMCG engine has stalled before the new retail initiative can provide meaningful traction. With cash flows deeply negative and working capital cycles ballooning, the operational stress is acute.
The stock’s steep decline over the past year—down over 85% according to DataCedar—reflects this fundamental deterioration. Investors are now weighing whether the nascent sportswear retail foray can gain scale fast enough to offset the legacy decline, a turnaround that appears quarters away at best.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.