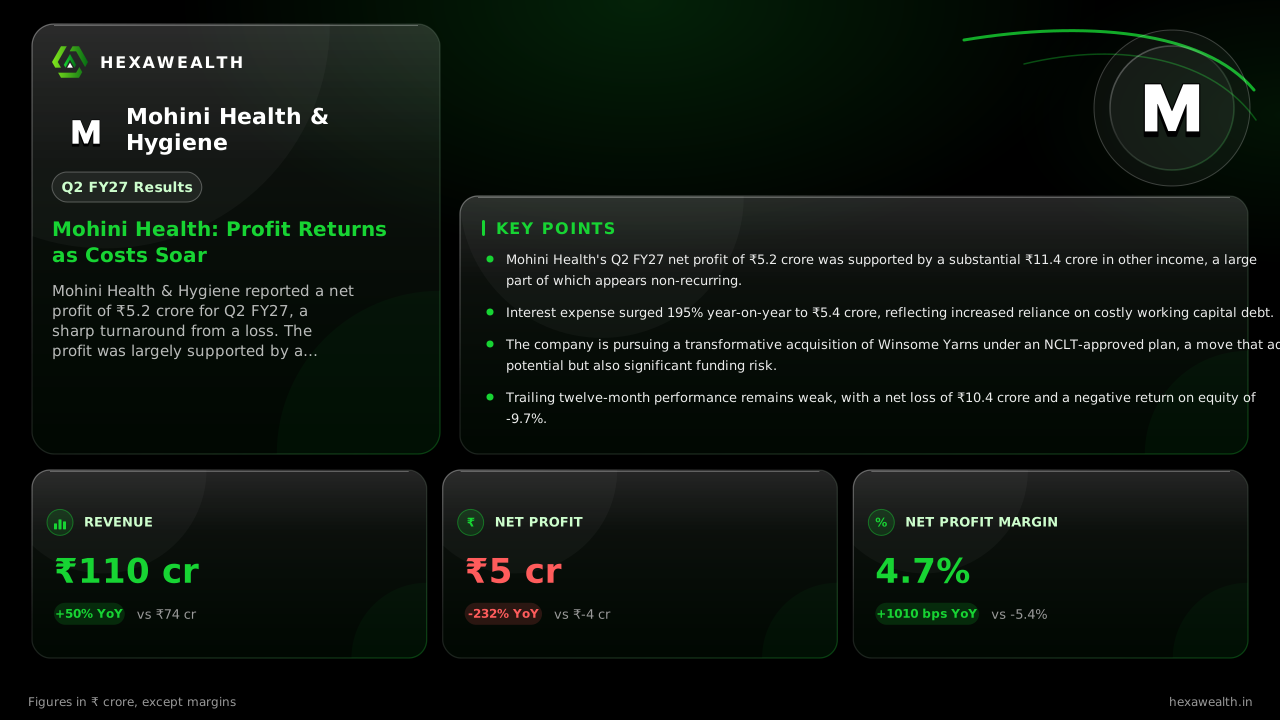
Mohini Health (MHHL) Q2 FY27 Profit Returns on a One-Off, But Debt Costs Triple
The healthcare products maker swung to a quarterly profit, but the recovery was driven by non-operating income as interest expense nearly tripled year-on-year.
Mohini Health & Hygiene reported a net profit of ₹5.2 crore for Q2 FY27, a sharp turnaround from a loss. The profit was largely supported by a one-off income item, while core operations were strained by a near-tripling of interest costs.
For a company that bleaches raw cotton into medical-grade products, the quarter's story is a thin margin stretched by debt. Mohini Health & Hygiene swung to a small profit, but the recovery is fragile, built on a one-time gain as borrowing costs surge.
The numbers show a stark divide. Revenue jumped 50% year-on-year to ₹110.4 crore. Yet, net profit of ₹5.2 crore was propped up by other income of ₹11.4 crore, a figure flagged by Moat Margin Research as largely non-operating. The core business was squeezed by a near-tripling of interest expense to ₹5.4 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 110.43YoY +50% | 73.54 |
| Profit (₹ Cr) | 5.20YoY +232% | -3.95 |
| Net Profit Margin | 4.7%YoY +187% | -5.4% |
The one-off that saved the quarter
A reported profit of ₹5.2 crore marks a sharp improvement from the prior quarter's deep loss. However, research from Moat Margin Research suggests the profit rise came largely from non-operating income, which the filing did not detail. Without this ₹11.4 crore other income, the operating business would have posted a significant loss.
A debt burden that will not lift soon
Interest expense nearly tripled both year-on-year and quarter-on-quarter. This surge points to higher working capital borrowings, a view supported by analysis from newboard.in. The site notes cash is tied up in cotton stock and customer dues, financed by bank lines. India Ratings cut the company's long-term rating to IND BB- with a negative outlook in September 2026.
A pivot with its own costs
Management's stated plan is to take over and revive insolvent yarn maker Winsome Yarns. The NCLT approved a ₹162.9 crore resolution plan in April 2026. While this offers a new avenue, it demands capital infusion and adds complexity. The company also seeks to move its listing to the main board and launch new products, but provides no concrete guidance.
Key Points
- Mohini Health's Q2 FY27 net profit of ₹5.2 crore was supported by a substantial ₹11.4 crore in other income, a large part of which appears non-recurring.
- Interest expense surged 195% year-on-year to ₹5.4 crore, reflecting increased reliance on costly working capital debt.
- The company is pursuing a transformative acquisition of Winsome Yarns under an NCLT-approved plan, a move that adds potential but also significant funding risk.
- Trailing twelve-month performance remains weak, with a net loss of ₹10.4 crore and a negative return on equity of -9.7%.
Hexa Perspective
The quarter reveals a business caught between a needed operational reset and a punishing cost of capital. The return to profit is not a sign of core strength but a pause enabled by a one-off. The tripling of interest cost is the more durable signal, reflecting strained liquidity that a major acquisition will only intensify. Investors are weighing a potential turnaround story against a balance sheet under rating agency scrutiny. For the stock, down 41% over the past year, the path to sustained earnings requires not just revenue growth but a material reduction in financial leverage—a tall order as it embarks on its most capital-intensive project yet.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.