Brilliant Portfolios (BRIPORT) Q2 FY27 Profit Plunges 87% as Interest Costs Bite
The NBFC's revenue grew 30% year-on-year, but a sharp 54% quarterly jump in interest expense erased nearly all profitability.
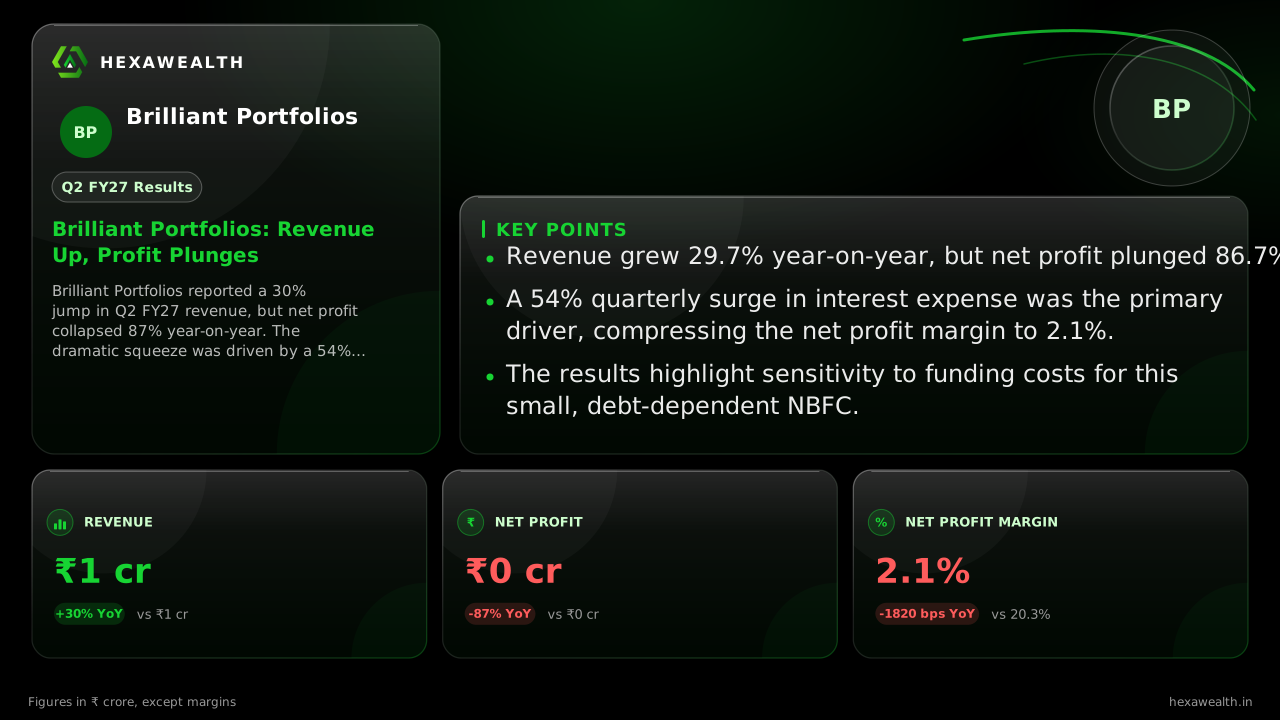
Brilliant Portfolios reported a 30% jump in Q2 FY27 revenue, but net profit collapsed 87% year-on-year. The dramatic squeeze was driven by a 54% quarterly surge in interest costs, which overwhelmed top-line growth.
For a small NBFC, the core challenge is earning more from loans than it pays for the money. Brilliant Portfolios' September quarter shows that equation breaking down, as a surge in borrowing costs consumed nearly all its income.
The numbers tell a story of divergence. Revenue rose 30% year-on-year to ₹0.96 crore. Yet, net profit collapsed 87% to just ₹0.02 crore. The net profit margin, a healthy 20.3% a year ago, shrank to 2.1%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 0.96YoY +30% | 0.97 | 0.74 |
| Profit (₹ Cr) | 0.02YoY -87% | 0.24 | 0.15 |
| Net Profit Margin | 2.1%YoY -90% | 24.3% | 20.3% |
The Interest Cost Squeeze
The primary culprit was a 54% quarter-on-quarter jump in interest expense, which rose to ₹0.77 crore. According to MarketPing, the company's biggest cost is interest on borrowings that fund its loan book. With revenue flat sequentially, this surge directly erased profitability.
This pressure aligns with a broader sector trend noted by The Economic Times, where rising funding costs threaten NBFC margins. The report suggests incremental costs have inched up, particularly for lenders reliant on market borrowings.
A Light Cost Base, But Not Enough
Other operating expenses fell 77% from the June quarter, as noted in the company's cost structure. Yet, this provided little relief against the finance cost tide. The quarter saw no one-off provisions, indicating the margin collapse was purely operational.
The market reaction was muted, with the stock unchanged at ₹10.26 upon the announcement, per MarketsMojo. With no institutional holdings and a P/E of 4.2 trading at an 81% discount to the industry, the results confirmed existing concerns about scalability and leverage.
Key Points
- Revenue grew 29.7% year-on-year, but net profit plunged 86.7%.
- A 54% quarterly surge in interest expense was the primary driver, compressing the net profit margin to 2.1%.
- The results highlight sensitivity to funding costs for this small, debt-dependent NBFC.
Hexa Perspective
The quarter underscores the fragility of the model when rates bite. For profitability to recover, Brilliant Portfolios must either pass higher costs to borrowers—a challenge in a competitive market—or find cheaper funding. With the RBI in a tightening cycle, as per sector reports, this cost pressure may persist. The path forward hinges on managing this spread, a tall order for a small player with thin equity and no institutional backing.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.