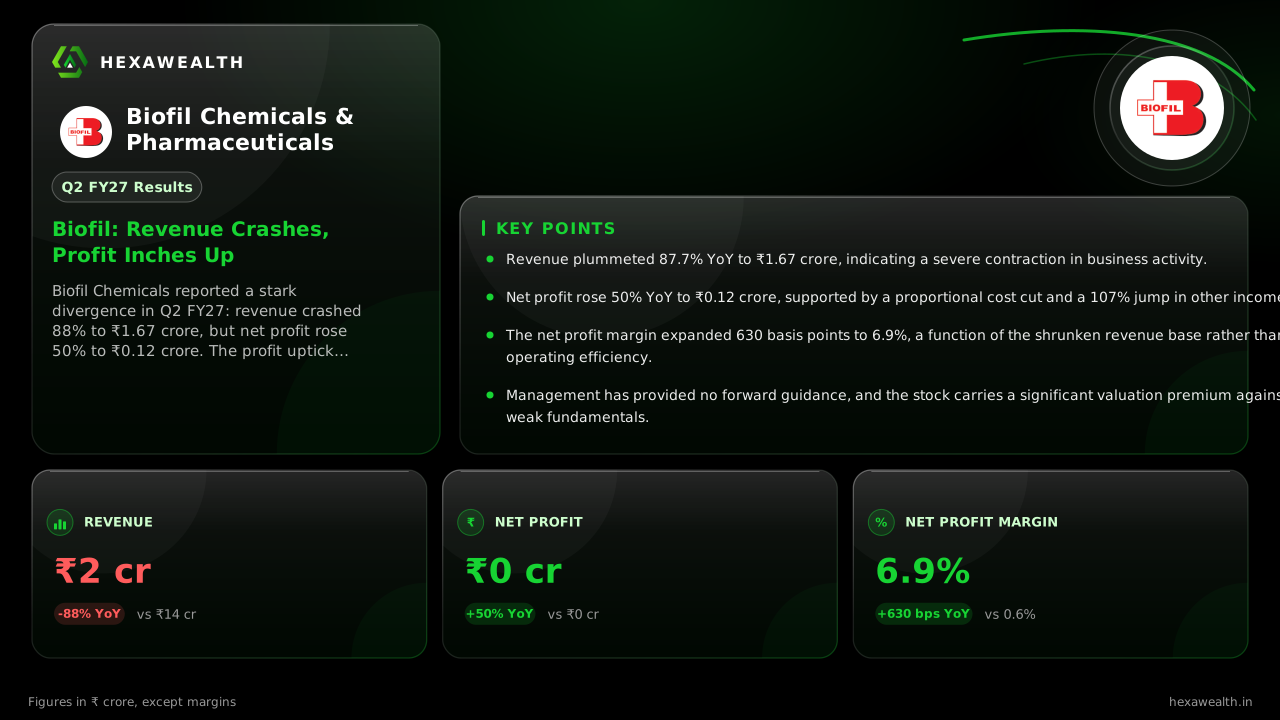
Biofil Chemicals reported a stark divergence in Q2 FY27: revenue crashed 88% to ₹1.67 crore, but net profit rose 50% to ₹0.12 crore. The profit uptick was driven by a severe cost cut and a doubling of other income.
For Biofil Chemicals, a quarter defined by extreme volatility has become the norm. The September quarter delivered another jarring swing, with revenue collapsing but a sliver of profit emerging from a drastically shrunken cost base.
Revenue fell 88% year-on-year to ₹1.67 crore, while net profit managed a 50% rise to ₹0.12 crore. The profit margin expanded sharply to 6.9%, up from 0.6% a year ago, as total expenses fell in lockstep with the top line.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
Metric
CurrentQ2 FY27 (Sep 2026)
PreviousQ1 FY27 (Jun 2026)
Revenue (₹ Cr)
1.67
12.35
Profit (₹ Cr)
0.12
0.11
Net Profit Margin
6.9%
0.9%
The Cost Cut That Created a Margin
The severe revenue drop was almost entirely matched by an 88% fall in total expenses. This suggests a near-total halt in the company's core trading or manufacturing activities. Employee costs and depreciation held relatively steady, indicating the business maintained its fixed structure.
A key support was other income, which more than doubled year-on-year to ₹0.13 crore. According to data from Tapetide, this non-operational boost was critical in lifting profit before tax by 39% despite the operational stall.
A Business in Pause
Research suggests the revenue collapse stems from a cyclical trough in trading activity. A report by ScanX noted that the prior quarter's growth was driven by the Chemical Division's trading, while the Pharma Division posted a loss. The current quarter likely reflects a pause between large, irregular trading deals.
Furthermore, the company's manufacturing facility is undergoing renovation for Schedule M compliance, as per a ScanX analysis. This disruption may have curtailed production-led revenue for at least another quarter.
The Market's Skeptical View
The extreme volatility has drawn sharp criticism. MarketsMojo maintains a 'Strong Sell' rating, citing a 22% CAGR decline in operating profits over five years and “flat financial performance.” Institutional interest remains absent, with FII and DII holdings near zero, according to Cruxal.
Key Points
Revenue plummeted 87.7% YoY to ₹1.67 crore, indicating a severe contraction in business activity.
Net profit rose 50% YoY to ₹0.12 crore, supported by a proportional cost cut and a 107% jump in other income.
The net profit margin expanded 630 basis points to 6.9%, a function of the shrunken revenue base rather than operating efficiency.
Management has provided no forward guidance, and the stock carries a significant valuation premium against weak fundamentals.
“
Hexa Perspective
The quarter reveals a business operating in fits and starts, reliant on sporadic trading deals rather than steady manufacturing. The margin expansion is a mathematical artifact of a shrunken denominator, not a sign of improved profitability.
With manufacturing upgrades ongoing and no visible order pipeline, revenue recovery is uncertain and likely to remain lumpy. The stock's 165% premium to the industry PE, against this backdrop of operational instability, presents a stark disconnect that investors continue to price with deep skepticism.
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Frequently asked questions
What were Biofil Chemicals & Pharmaceuticals' Q2 FY27 results?
For Q2 FY27 (September 2026), Biofil Chemicals reported revenue of ₹1.67 crore, down 87.7% year-on-year. Net profit was ₹0.12 crore, up 50% from the same quarter last year. The net profit margin expanded to 6.9% from 0.6% in Q2 FY26.
Why did Biofil Chemicals' revenue collapse by ~88% in Q2 FY27?
Biofil Chemicals' revenue collapse to ₹1.67 crore suggests a near-total halt in its core trading or manufacturing activities. Research indicates the company's revenue is highly volatile and driven by irregular trading deals, with the current quarter likely being a trough between such transactions.
What drove the sharp improvement in Biofil Chemicals' net profit margin despite the revenue crash?
Biofil's net profit margin rose 600 basis points QoQ to 6.9% because total expenses fell almost as sharply as revenue (-86.6% QoQ). Furthermore, other income more than doubled, providing a critical boost to the bottom line on a drastically reduced revenue base.
Did Biofil Chemicals have a major one-off expense in Q1 FY27?
No major one-off expense was reported for Q1 FY27. The low 0.9% net margin that quarter was due to high costs of materials and stock-in-trade, which consumed nearly 95% of total income, as per an EquityTale breakdown of the financials.
What is the breakdown of Biofil Chemicals' revenue between chemicals and pharmaceuticals?
Specific segment breakdown for Q2 FY27 is not provided in the results. However, research from ScanX covering the prior quarter noted that Q1 growth was driven by trading in the Chemical Division, while the Pharma Division posted a segment loss.
Why did 'other income' for Biofil Chemicals more than double in Q2 FY27?
Biofil Chemicals' other income rose 107% year-on-year to ₹0.13 crore in Q2 FY27. While the specific source isn't detailed, this non-operational income was a key factor in supporting profit before tax, which grew 39% despite the massive revenue decline.
What is the cash flow and working capital situation for Biofil Chemicals?
Annual cash flow data from Cruxal shows volatility. For FY26 ended March 2026, cash from operations was negative ₹0.60 crore. The cash conversion cycle was 171 days, indicating capital is tied up in working capital for an extended period.
Does Biofil Chemicals have any large pending orders to normalize revenue?
There is no disclosure of a significant order book or pipeline in the recent filings. A StockFin.ai analysis notes management has not provided forward-looking guidance on revenue or growth, indicating a lack of visible near-term catalysts.
Is Biofil Chemicals undergoing any major plant shutdown or expansion?
Yes. According to a ScanX report, Biofil's manufacturing facility is undergoing renovation to comply with revised Schedule M regulations. The completion was expected within three to six months from August 2026, which may have disrupted production.
Has Biofil Chemicals announced any asset sales or divestments recently?
In FY26, shareholders approved the sale or transfer of leasehold rights for an industrial land parcel in Dhar, Madhya Pradesh, as per an InCred Money summary. No major recent divestments were announced alongside the Q2 results.
What were the analyst estimates for Biofil Chemicals Q2 FY27 results?
There is no record of published analyst estimates for Biofil Chemicals' Q2 FY27 results. Coverage of the company is minimal, and the results announcement did not reference a consensus to beat or miss.
Which brokerages have changed their rating for Biofil Chemicals after Q2 FY27?
No new brokerage rating changes were reported immediately following the Q2 FY27 results. MarketsMojo maintained its 'Strong Sell' rating on the stock, last updated in September 2026, citing weak fundamentals and financial trends.
Are mutual funds or FIIs increasing their stake in Biofil Chemicals?
No. Shareholding data from Cruxal shows FII holding has been 0.00% and DII holding a negligible 0.08% since at least September 2025. Promoter holding has remained stable at 46.79%, indicating no institutional accumulation.
What are the key concerns raised by analysts about Biofil Chemicals?
Analysts, including MarketsMojo, highlight concerns over declining long-term operating profit growth, poor debt servicing ability, extreme revenue volatility, and a lack of sustainable earnings. The company's premium valuation despite these weaknesses is also a key risk.
Biofil Chemicals & Pharmaceuticals Q2 net profit?
Biofil Chemicals & Pharmaceuticals reported a net profit of ₹0.12 crore for the second quarter of FY27, ended September 2026. This represents a 50% increase compared to the net profit of ₹0.08 crore in the same quarter of the previous year.