Bench Mark Infotech (BMISL) Q2 FY27's Profit Margins Narrow Even as Order Book Swells
The IT infrastructure provider posted a Q2 profit of ₹1.12 crore on revenue of ₹13.91 crore, with margins under pressure from project execution costs.
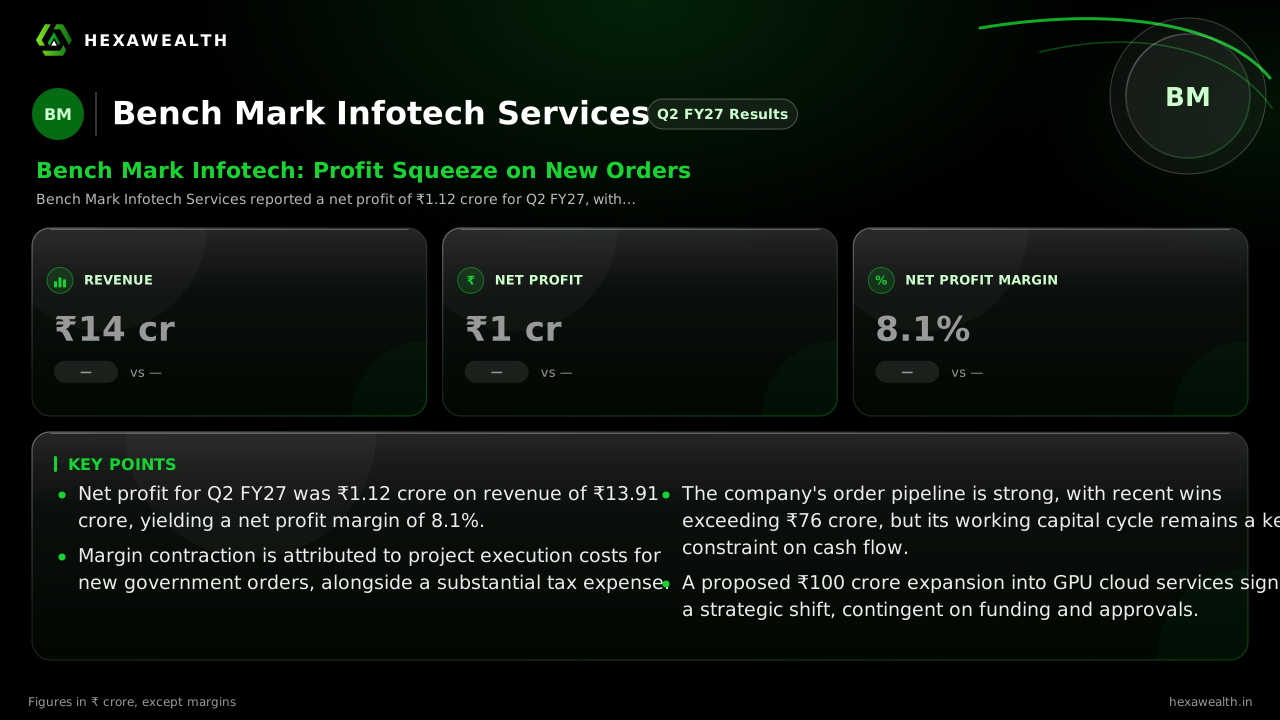
Bench Mark Infotech Services reported a net profit of ₹1.12 crore for Q2 FY27, with revenue at ₹13.91 crore. The quarter saw a significant margin contraction compared to the annual average, even as the company secured large government orders.
For IT infrastructure providers like Bench Mark Infotech, growth is often a story of project execution and working capital cycles. The September quarter delivered a mixed script: a steady revenue base of ₹13.91 crore, but a net profit margin that compressed sharply to 8.1%, well below the company's FY26 annual average of 16.9%.
| Metric | CurrentSep 2026 (Q2 FY27) |
|---|---|
| Revenue (₹ Cr) | 13.91 |
| Profit (₹ Cr) | 1.12 |
| Net Profit Margin | 8.1% |
The gap between revenue and profit points to a margin squeeze. A tax expense of ₹1.73 crore, as reported by Arthneeti, consumed a significant portion of the pre-tax profit of ₹2.85 crore. This left a net profit of ₹1.12 crore for the quarter.
Why Margins Narrowed
Project execution costs are the likely culprit. The company's business model, detailed in its IPO documents, involves procuring equipment and managing installation for government IT contracts. As Flash Finance reports, Bench Mark recently won orders worth ₹66.67 crore and ₹9.98 crore from government clients. Ramping up these new projects typically involves upfront costs for materials, logistics, and manpower before revenue is fully recognized, pressuring near-term profitability.
A Full Pipeline Meets a Cash Constraint
The future revenue stream appears robust. The company's order book stood at ₹12.18 crore as of mid-September, according to Newboard.in. Furthermore, management has announced an ambitious ₹100 crore phased investment to expand into GPU-as-a-Service, as noted by Arthneeti. However, this growth ambition runs into a historical cash flow challenge. Operating cash flow was deeply negative in FY26, with trade receivables absorbing over 90% of annual revenue.
This working capital intensity means that while the order book grows, converting those wins into cash remains a critical hurdle. The market acknowledged both the promise and the pressure, with the stock closing up 5% on the day before the results, as per Flash Finance data.
Key Points
- Net profit for Q2 FY27 was ₹1.12 crore on revenue of ₹13.91 crore, yielding a net profit margin of 8.1%.
- Margin contraction is attributed to project execution costs for new government orders, alongside a substantial tax expense.
- The company's order pipeline is strong, with recent wins exceeding ₹76 crore, but its working capital cycle remains a key constraint on cash flow.
- A proposed ₹100 crore expansion into GPU cloud services signals a strategic shift, contingent on funding and approvals.
Hexa Perspective
The quarter underscores the classic tension in project-based IT services: a bulging order book does not immediately translate to bottom-line strength. Bench Mark's profitability is currently caught between the costs of servicing new contracts and a tax outlay.
The path forward hinges on execution efficiency and collections. If the company can streamline project costs and accelerate receivables from its government clients, the margin pressure could ease as these large orders mature. Investors are betting on that transition, but the cash flow statement will be the ultimate validator.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.