Lotus Eye Hospital (LOTUSEYE) Q2 FY27 Profit Dips 28% Despite Strong Revenue Growth
Revenue jumped 36% year-on-year, but a sharp sequential drop in profit highlights the cost pressures from the company's ongoing expansion.
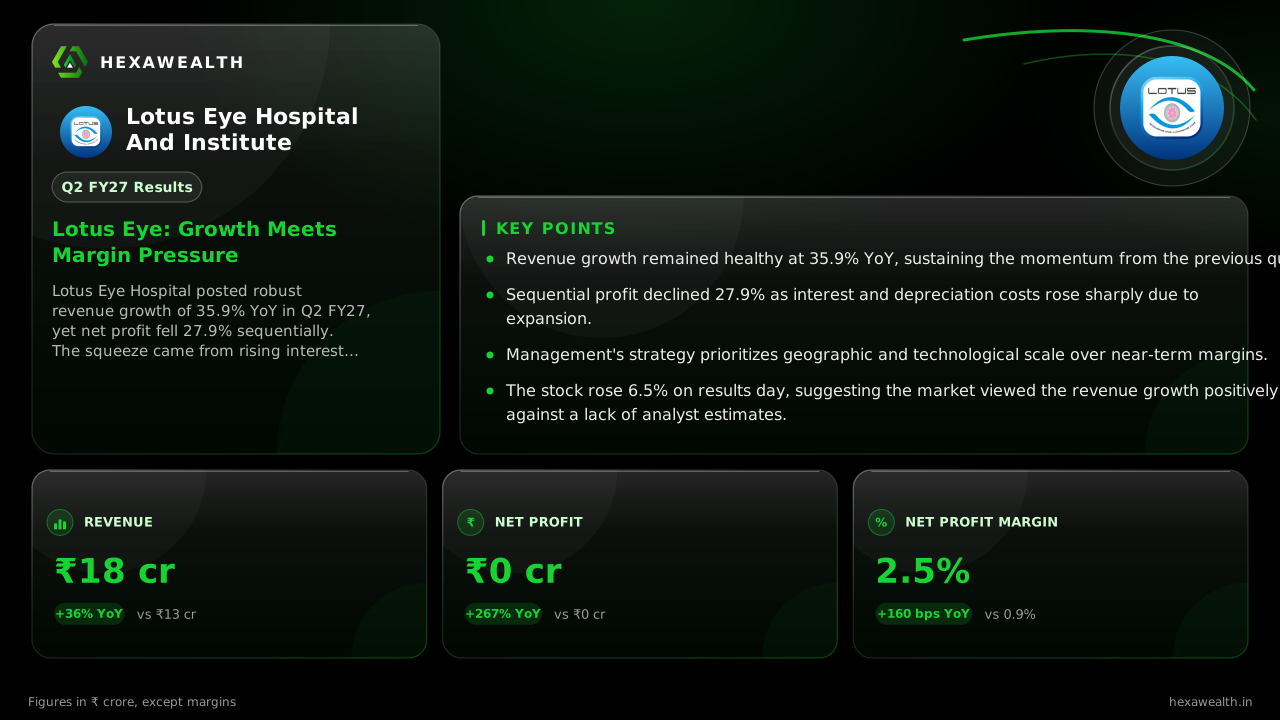
Lotus Eye Hospital posted robust revenue growth of 35.9% YoY in Q2 FY27, yet net profit fell 27.9% sequentially. The squeeze came from rising interest and depreciation costs linked to new capacity additions.
For Lotus Eye Hospital, the September quarter was a story of two speeds. The top line continued its strong run, but the bottom line stumbled under the weight of a deliberate, capital-heavy expansion strategy.
Revenue reached ₹17.72 crore, up 35.9% from a year ago and 3.9% from the previous quarter. Net profit, however, fell to ₹0.44 crore, a 27.9% drop sequentially even as it showed a large year-on-year improvement from a low base. The net profit margin compressed by 110 basis points from Q1.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 13.04
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 13.55
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 13.61
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 17.06
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 17.72
- Net Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.12
- Net Profit (₹ Cr), Q3 FY26 (Dec 2025): -0.26
- Net Profit (₹ Cr), Q4 FY26 (Mar 2026): -0.32
- Net Profit (₹ Cr), Q1 FY27 (Jun 2026): 0.61
- Net Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.44
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 13.04
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 13.55
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 13.61
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 17.06
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 17.72
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.12
- Net Profit (₹ Cr), Q3 FY26 (Dec 2025): -0.26
- Net Profit (₹ Cr), Q4 FY26 (Mar 2026): -0.32
- Net Profit (₹ Cr), Q1 FY27 (Jun 2026): 0.61
- Net Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.44
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 17.72 | 17.06 |
| Net Profit (₹ Cr) | 0.44 | 0.61 |
| PAT Margin (%) | 2.5 | 3.6 |
The Expansion Bill Comes Due
The profit squeeze is directly tied to funding growth. Interest expense surged 374.5% year-on-year and 17% quarter-on-quarter. Depreciation more than doubled from last year.
This combination, noted in a Univest preview, is consistent with debt-funded capacity additions now contributing to revenue but also to the cost structure. Management is prioritizing scale, with a new branch opened in Erode, Tamil Nadu, as reported by ALFA News.
A Volatile Path to Scale
Profitability has been volatile as the company invests. The trailing twelve-month net profit margin stands at a thin 0.8%. A StockFin.ai analysis states management is focused on expanding clinical capabilities and technology while strengthening cost control.
Live Chart
· LOTUSEYE
(BSE)
ISIN: INE947I01017
The near-term outlook hinges on how quickly new centres can ramp up patient volumes to offset their fixed costs. The company trades at a significant discount to the industry average P/E, reflecting the market's caution on this margin recovery timeline.
Key Points
- Revenue growth remained healthy at 35.9% YoY, sustaining the momentum from the previous quarter.
- Sequential profit declined 27.9% as interest and depreciation costs rose sharply due to expansion.
- Management's strategy prioritizes geographic and technological scale over near-term margins.
- The stock rose 6.5% on results day, suggesting the market viewed the revenue growth positively against a lack of analyst estimates.
Hexa Perspective
The quarter confirms Lotus Eye is in a classic growth-investment phase. The revenue engine is working, but the full benefit of new capacity is still ahead. The critical watchpoint is operating leverage: can patient volumes grow fast enough to outpace the rising fixed costs of depreciation and interest?
With negligible institutional ownership and a steady promoter stake, the stock's move will be driven by evidence of this margin inflection. For now, the story is one of promising top-line expansion awaiting a more profitable bottom line.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.