Billwin Industries (BILLWIN) Q2 FY27 Profit Dives 69% as New Facility Costs Bite
The safety gear maker's revenue fell nearly 50% year-over-year, with profit dropping even more sharply as higher fixed costs from a new plant squeezed margins.
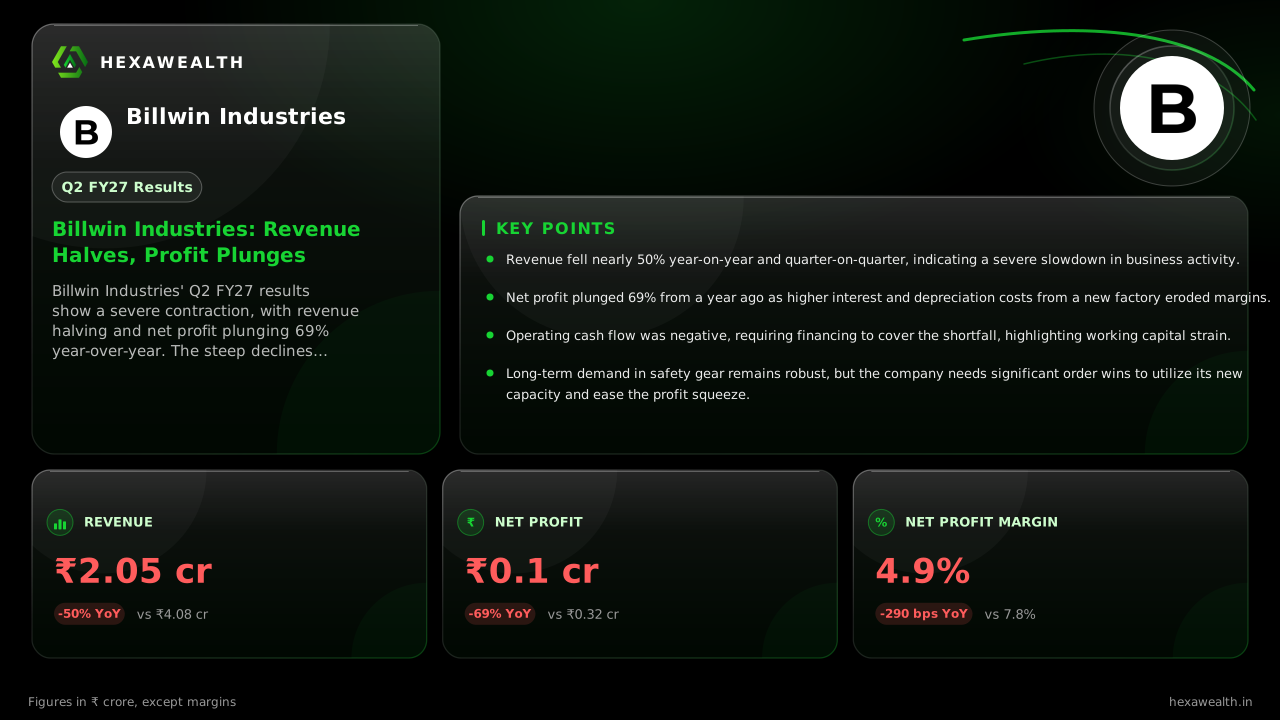
Billwin Industries' Q2 FY27 results show a severe contraction, with revenue halving and net profit plunging 69% year-over-year. The steep declines highlight the pressure from a new manufacturing facility's costs amid a sharp drop in sales.
For Billwin Industries, a maker of life jackets and inflatable boats, the September quarter revealed the painful gap between building capacity and realizing its benefits. Revenue collapsed by nearly half from a year ago, while profit fell even more sharply as the fixed costs of a new factory hit the income statement.
The numbers tell a story of deep contraction. Revenue for Q2 FY27 was ₹2.05 crore, down 49.8% from the same quarter last year and 48.9% lower than the March quarter. Net profit stood at just ₹0.1 crore, a 68.8% year-on-year plunge. The company's net profit margin, while improving slightly from the prior quarter, remains less than half of what it was a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 2.83
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 4.20
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 4.08
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 4.01
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 2.05
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 0.38
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 0.30
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.32
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 0.14
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.10
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 2.83
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 4.20
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 4.08
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 4.01
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 2.05
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 0.38
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 0.30
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.32
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 0.14
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.10
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 2.05 | 4.01 |
| Profit (₹ Cr) | 0.10 | 0.14 |
| Net Margin (%) | 4.9 | 3.5 |
The Capex Squeeze
The profit drop was not due to one-off items. Instead, the pressure came from rising fixed costs that began with a major expansion. A report from Hexawealth notes Billwin started production at a new facility on Mumbai's outskirts in October 2025. This investment led to a 33% year-on-year jump in interest expense and kept depreciation charges elevated, squeezing margins just as sales plummeted.
The company's cash flow statement, reported by MarketsMojo, shows operations consumed ₹0.26 crore in the half-year. Financing inflows of ₹0.32 crore were needed to fund this and a small investment outflow, leaving cash at a minimal ₹0.02 crore. This underscores the financial strain during a period of weak sales.
A Market Waiting for Orders
Research suggests the broader market for protective gear in India has strong long-term prospects. Future Market Insights forecasts India's offshore fall protection market to grow at a 7.2% annual rate through 2036. However, Billwin's current slump indicates it has yet to convert this potential into firm orders for its new capacity.
Live Chart
· BILLWIN
(BSE)
ISIN: INE0CRS01012
The company did secure a technology transfer from the Ministry of Defence in September to manufacture submarine escape suits, as reported by Equitybulls. But such defense contracts take time to translate into production revenue, offering little near-term relief for the steep sales decline witnessed this quarter.
Key Points
- Revenue fell nearly 50% year-on-year and quarter-on-quarter, indicating a severe slowdown in business activity.
- Net profit plunged 69% from a year ago as higher interest and depreciation costs from a new factory eroded margins.
- Operating cash flow was negative, requiring financing to cover the shortfall, highlighting working capital strain.
- Long-term demand in safety gear remains robust, but the company needs significant order wins to utilize its new capacity and ease the profit squeeze.
Hexa Perspective
Billwin Industries is caught in a classic expansion trap. It has invested in new capacity, evidenced by higher fixed costs, but the expected sales ramp-up has not materialized, leading to a severe earnings contraction. The success of this bet now hinges entirely on securing large, executable orders to fill the new plant.
The company's valuation, trading at a P/E of 42.9 against an industry average of 35.7, prices in growth that is conspicuously absent from current operations. Investors are left weighing the promise of the defense contract and market potential against the immediate reality of plunging sales and strained finances. The next few quarters must show a decisive reversal in revenue trajectory to validate the capex spend.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.