Looks Health Services (LOOKS) Revenue Jumps 86% But Profit Stalls in Q2 FY27
The aesthetic clinic chain saw a sharp rise in sales, but costs grew faster, leaving net profit unchanged from a year ago.
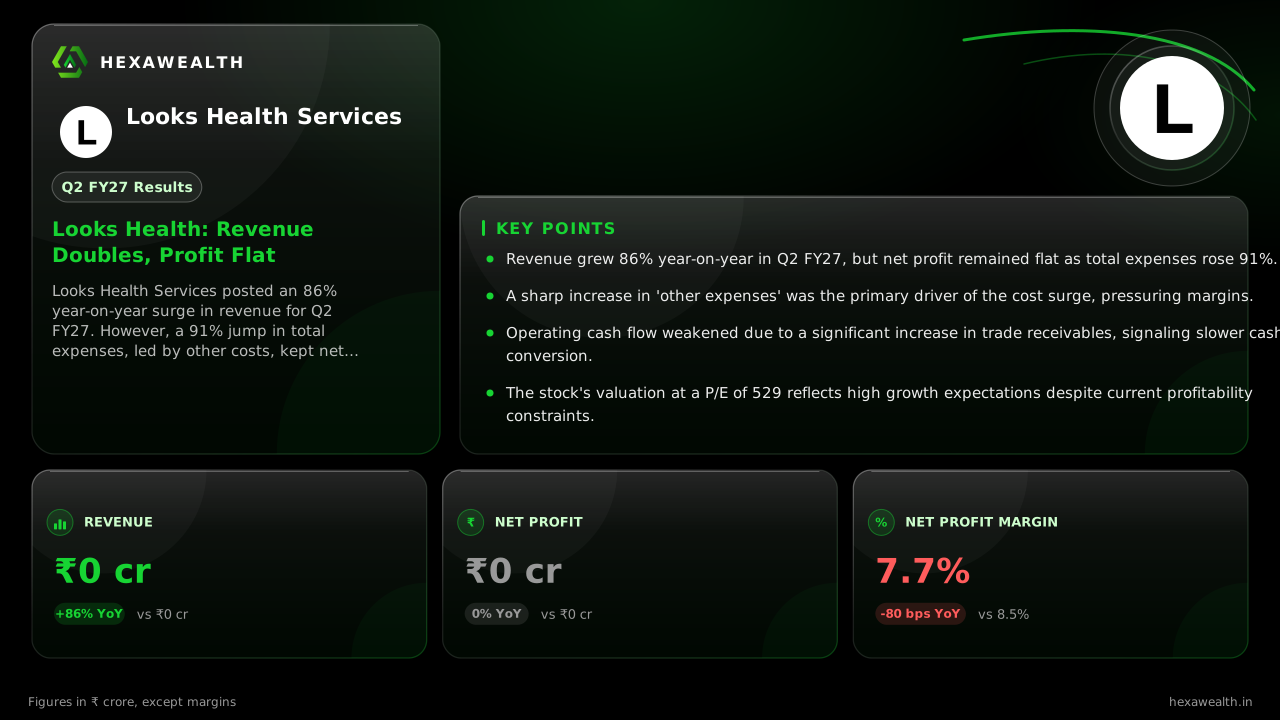
Looks Health Services posted an 86% year-on-year surge in revenue for Q2 FY27. However, a 91% jump in total expenses, led by other costs, kept net profit flat and pressured margins.
For a small chain of cosmetic and hair clinics, a near-doubling of quarterly revenue signals strong demand. Yet for Looks Health Services, that top-line surge in the September quarter did not translate into higher profits, as costs rose even faster.
The numbers show the split. Revenue grew 86% year-on-year to ₹0.13 crore. Sequentially, sales rose 8% from the June quarter. Net profit, however, was flat at ₹0.01 crore compared to Q2 FY26. The net profit margin contracted 80 basis points year-on-year to 7.7%, though it recovered sharply from a weak 1.6% in Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 0.07
- Revenue (₹ Cr), Q3 FY26: 0.12
- Revenue (₹ Cr), Q4 FY26: 0.12
- Revenue (₹ Cr), Q1 FY27: 0.12
- Revenue (₹ Cr), Q2 FY27: 0.13
- Profit (₹ Cr), Q2 FY26: 0.01
- Profit (₹ Cr), Q3 FY26: 0.01
- Profit (₹ Cr), Q4 FY26: 0.01
- Profit (₹ Cr), Q1 FY27: 0.00
- Profit (₹ Cr), Q2 FY27: 0.01
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 0.07
- Revenue (₹ Cr), Q3 FY26: 0.12
- Revenue (₹ Cr), Q4 FY26: 0.12
- Revenue (₹ Cr), Q1 FY27: 0.12
- Revenue (₹ Cr), Q2 FY27: 0.13
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 0.01
- Profit (₹ Cr), Q3 FY26: 0.01
- Profit (₹ Cr), Q4 FY26: 0.01
- Profit (₹ Cr), Q1 FY27: 0.00
- Profit (₹ Cr), Q2 FY27: 0.01
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26: 8.5
- Net Profit Margin (%), Q3 FY26: 6.5
- Net Profit Margin (%), Q4 FY26: 6.5
- Net Profit Margin (%), Q1 FY27: 1.6
- Net Profit Margin (%), Q2 FY27: 7.7
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Period Ended | Sep 2026 | Jun 2026 | Sep 2025 |
| Revenue (₹ Cr) | 0.13YoY +86% | 0.12 | 0.07 |
| Profit (₹ Cr) | 0.01YoY 0% | 0.00 | 0.01 |
| Net Profit Margin (%) | 7.7YoY -9.4% | 1.6 | 8.5 |
Where the revenue growth went
Total expenses surged 91% year-on-year, nearly matching the revenue jump. A report from scanx.trade notes this was primarily due to a sharp increase in 'other expenses', which rose to ₹6.86 lakh from ₹0.99 lakh a year ago. This suggests the cost of delivering higher sales—potentially marketing, commissions, or clinic operations—rose disproportionately.
The cash flow catch
While the profit statement showed growth, the cash flow story is different. The same report highlights a significant decline in operating cash flow for the first half of FY27. This was attributed to a ₹14.50 lakh build-up in trade receivables, indicating that cash collection is lagging behind recorded sales.
A valuation disconnect
Despite the operational challenges, the stock has doubled over the past year. At a price-to-earnings ratio of 529, it trades at a massive premium to the industry average of 86. The market appears to be pricing in future growth from a still-tiny revenue base, overlooking current profitability pressures.
Live Chart
· LOOKS
(BSE)
ISIN: INE204N01013
Key Points
- Revenue grew 86% year-on-year in Q2 FY27, but net profit remained flat as total expenses rose 91%.
- A sharp increase in 'other expenses' was the primary driver of the cost surge, pressuring margins.
- Operating cash flow weakened due to a significant increase in trade receivables, signaling slower cash conversion.
- The stock's valuation at a P/E of 529 reflects high growth expectations despite current profitability constraints.
Hexa Perspective
The quarter reveals a company in an aggressive growth phase, where expanding the top line is coming at a high cost. The margin pressure and lengthening cash cycle are classic signs of a business scaling before achieving operating efficiency.
The sustainability of this model hinges on whether these rising costs are one-time investments for growth or a persistent feature. For now, the market's premium valuation bets heavily on the former, demanding clear evidence of future margin expansion and better cash flow discipline.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.