Vegorama Punjabi Angithi (VPAL) Q4 FY26 Profit Doubles as Expansion Fuels Growth
The cloud kitchen operator posted a 35% revenue jump and doubled its net profit in Q4 FY26, driven by aggressive expansion and improved operating leverage.
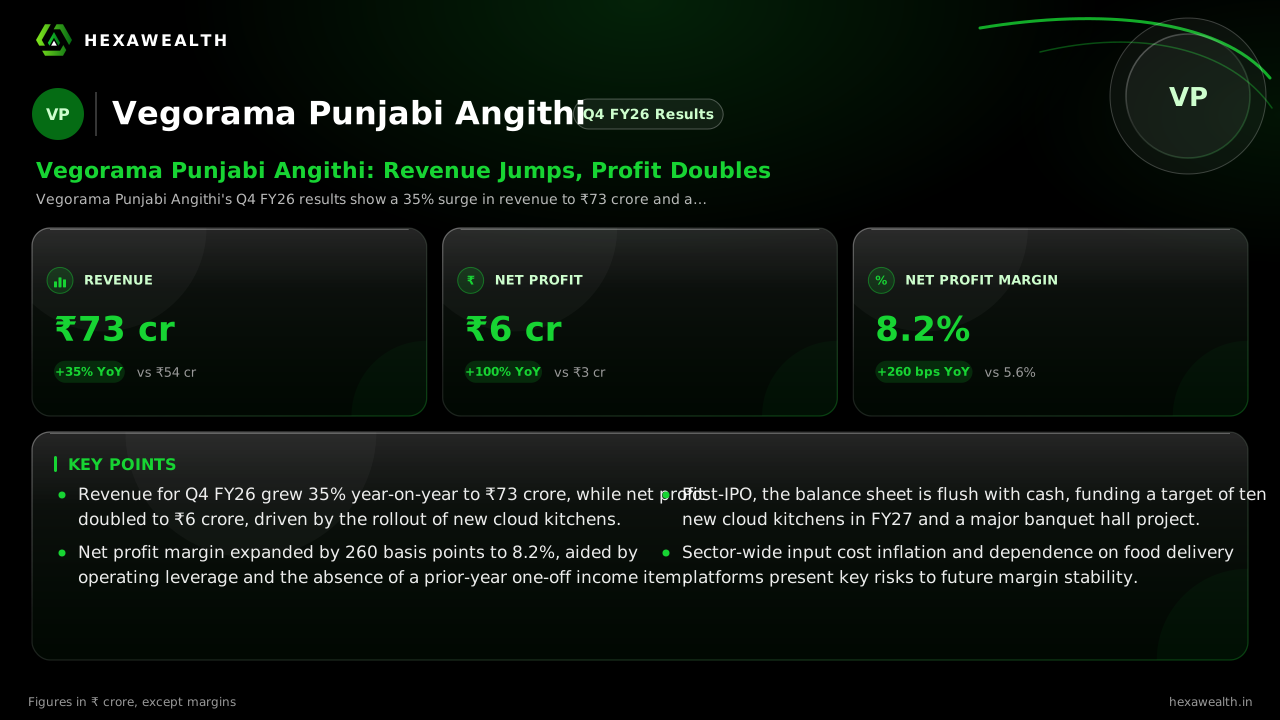
Vegorama Punjabi Angithi's Q4 FY26 results show a 35% surge in revenue to ₹73 crore and a 100% jump in profit to ₹6 crore. The growth is powered by new cloud kitchen openings and a sharp 260 basis point expansion in net profit margin.
For Vegorama Punjabi Angithi, growth is a function of kitchens. The cloud kitchen operator, which went public in May 2026, ended its first post-IPO year by showing what its capital can do: revenue and profit both surged as it rolled out new locations.
The March quarter revenue hit ₹73 crore, up 35% from a year ago. Net profit doubled to ₹6 crore. This capped a full year where revenue grew 39% to ₹141 crore and profit rose 47% to ₹12 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 54.0
- Revenue (₹ Cr), Q4 FY26: 73.0
- Profit (₹ Cr), Q4 FY25: 3.0
- Profit (₹ Cr), Q4 FY26: 6.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 54.0
- Revenue (₹ Cr), Q4 FY26: 73.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY25: 3.0
- Profit (₹ Cr), Q4 FY26: 6.0
Net Profit Margin
- Net Profit Margin, Q4 FY25: 5.6%
- Net Profit Margin, Q4 FY26: 8.2%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 73.0YoY +35% | 54.0 |
| Profit (₹ Cr) | 6.0YoY +100% | 3.0 |
| Net Profit Margin | 8.2%YoY +46% | 5.6% |
The Engine Behind the Surge
Growth came from adding kitchens. The company ended FY26 with 27 cloud kitchens, up from 19 a year earlier, according to its annual report. New kitchens in Noida, Gurugram, and Delhi opened in recent months. This expansion, coupled with centralised purchasing, helped profit outpace sales.
Operating leverage kicked in as expenses grew slower than revenue. Total costs rose 30% year-on-year, allowing the net profit margin to expand by 260 basis points. The prior-year quarter also had a ₹1 crore other income gain that did not repeat, making the underlying profit growth even stronger.
A Cash-Rich Balance Sheet for More Growth
The company's war chest is now its defining feature. Its May 2026 IPO raised ₹30.7 crore, and a report from mcapital.in notes about ₹20.5 crore of that remains in fixed deposits. This turns a small net debt position into substantial net cash, funding an ambitious expansion plan.
Live Chart
· VPAL
(BSE)
ISIN: INE1L3801017
Management, in a July 2026 investor presentation, targets ten new cloud kitchens in FY27, aiming for two per quarter. A larger Gurugram banquet and fine-dine project is also in the works. The cash buffer provides a clear runway for this growth.
The Squeeze That Looms
Not all pressures are financial. The National Restaurant Association of India warned in November 2026 that rising input costs for raw materials and utilities are squeezing the entire sector. For Vegorama, where food costs are nearly half of revenue, this is a direct threat.
The company's heavy reliance on two delivery platforms, which accounted for over 90% of revenue, also limits pricing power in a competitive online marketplace. Growth is robust, but the path to sustaining margins will be tested by these industry-wide cost headwinds.
Key Points
- Revenue for Q4 FY26 grew 35% year-on-year to ₹73 crore, while net profit doubled to ₹6 crore, driven by the rollout of new cloud kitchens.
- Net profit margin expanded by 260 basis points to 8.2%, aided by operating leverage and the absence of a prior-year one-off income item.
- Post-IPO, the balance sheet is flush with cash, funding a target of ten new cloud kitchens in FY27 and a major banquet hall project.
- Sector-wide input cost inflation and dependence on food delivery platforms present key risks to future margin stability.
Hexa Perspective
The quarter confirms the capital-light, high-return model works at scale. With an ROE of 25.6% and a net cash position, the company has the fuel to execute its kitchen-led growth plan for the next 12-18 months.
The tension lies in the model's constraints. Profitability hinges on managing food costs, which are volatile, and navigating commissions from the two delivery platforms that control its customer access. The current expansion can drive top-line growth, but the real test will be preserving margins when industry costs rise and the company cannot fully pass them on.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.