Logica Infoway (LOGICA) Q4 FY26 Profit Growth Lags Revenue as Debt Costs Rise
The IT distributor's revenue surged 22% in Q4 FY26, but profit grew slower as higher interest costs squeezed its thin margins.
Logica Infoway closed FY26 with record revenue, driven by retail expansion and new mandates. However, profit growth lagged behind sales as rising debt costs and thin margins held back the bottom line.
For a distributor like Logica Infoway, growth is a double-edged sword. Every new store and sales mandate pushes revenue higher, but it also demands more working capital, which comes at a cost. The company’s March quarter results show that tension playing out in real time.
Revenue for Q4 FY26 jumped 22% year-on-year to ₹729 crore, capping a full year where sales grew 18% to a record ₹1,316 crore. Profit for the quarter rose 14% to ₹8 crore, but that was slower than the top-line growth. The net profit margin slipped slightly to 1.1%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 557
- Revenue (₹ Cr), Q2 FY25: 515
- Revenue (₹ Cr), Q4 FY25: 597
- Revenue (₹ Cr), Q2 FY26: 587
- Revenue (₹ Cr), Q4 FY26: 729
- Profit (₹ Cr), Q4 FY24: 6
- Profit (₹ Cr), Q2 FY25: 3
- Profit (₹ Cr), Q4 FY25: 7
- Profit (₹ Cr), Q2 FY26: 6
- Profit (₹ Cr), Q4 FY26: 8
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 557
- Revenue (₹ Cr), Q2 FY25: 515
- Revenue (₹ Cr), Q4 FY25: 597
- Revenue (₹ Cr), Q2 FY26: 587
- Revenue (₹ Cr), Q4 FY26: 729
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 6
- Profit (₹ Cr), Q2 FY25: 3
- Profit (₹ Cr), Q4 FY25: 7
- Profit (₹ Cr), Q2 FY26: 6
- Profit (₹ Cr), Q4 FY26: 8
Net Profit Margin
- Net Profit Margin, Q4 FY24: 1.1%
- Net Profit Margin, Q2 FY25: 0.6%
- Net Profit Margin, Q4 FY25: 1.2%
- Net Profit Margin, Q2 FY26: 1.0%
- Net Profit Margin, Q4 FY26: 1.1%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 729YoY +22% | 597 |
| Profit (₹ Cr) | 8YoY +14% | 7 |
| Net Profit Margin | 1.1%YoY -8.3% | 1.2% |
The cost of funding growth
The gap between revenue and profit growth points to a margin squeeze. Interest expense surged 33% year-on-year in the quarter, as borrowings climbed to fund expansion. According to a report from mcapital.in, short-term loans for working capital rose to ₹186.8 crore by March 2026.
This is the nature of a trading business, where brands largely set the margin structure. The company’s own retail stores offer better profitability, and revenue from this segment grew 60% in FY26, as noted in its annual report. But the capital needed to stock those stores is expensive.
A retail-led roadmap
Management is betting that this investment will pay off. The company guided for continued double-digit revenue growth in FY27, aiming to expand its store network from 77 to over 100. It expects the EBITDA margin to move towards 2.7-3.0% as newer stores mature.
Live Chart
· LOGICA
(BSE)
ISIN: INE0BSU01018
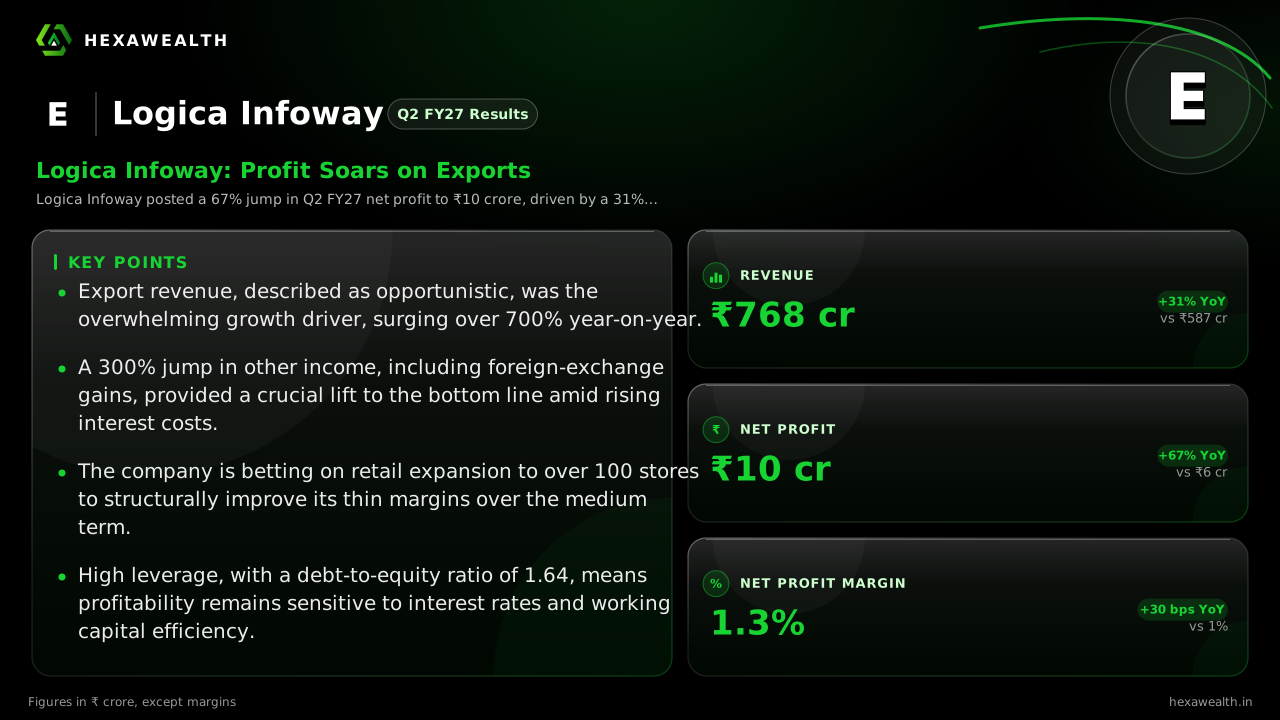
Early signs are promising. For H1 FY27, the company reported to mcapital.in that revenue jumped 31% and profit soared 57%. This performance, aided by other income, suggests the retail shift is gaining traction.
Key Points
- Full-year revenue hit a record ₹1,316 crore, up 17.6%, but annual profit growth of 35% outpaced the quarterly trend.
- Rising interest costs, up 33% YoY in Q4, squeezed net margins as the company borrowed to fund store expansion and working capital.
- The strategic pivot to higher-margin company-owned retail is showing results, with the segment's revenue up 60% in FY26.
- Management's FY27 guidance targets over 100 stores and an EBITDA margin of 2.7-3.0%, supported by a strong start to the year.
Hexa Perspective
Logica Infoway is executing a clear shift from wholesale distribution to retail, a move that should structurally improve its thin margins over time. The near-term story, however, is about funding that transition.
With a debt-to-equity ratio of 1.83, the company’ profitability is highly sensitive to interest rates and its ability to turn inventory quickly. The guidance for margin improvement hinges on new stores maturing as planned and the working capital cycle not stretching further. Investors are weighing robust growth against the capital intensity required to sustain it.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.