Astonea Labs (ASTONEALAB) Profit Soars 150% as Margins Jump in Q2 FY27
The API maker's revenue grew 45.5% year-on-year, while net profit margin expanded by 220 basis points, driven by a higher share of own OTC brands.
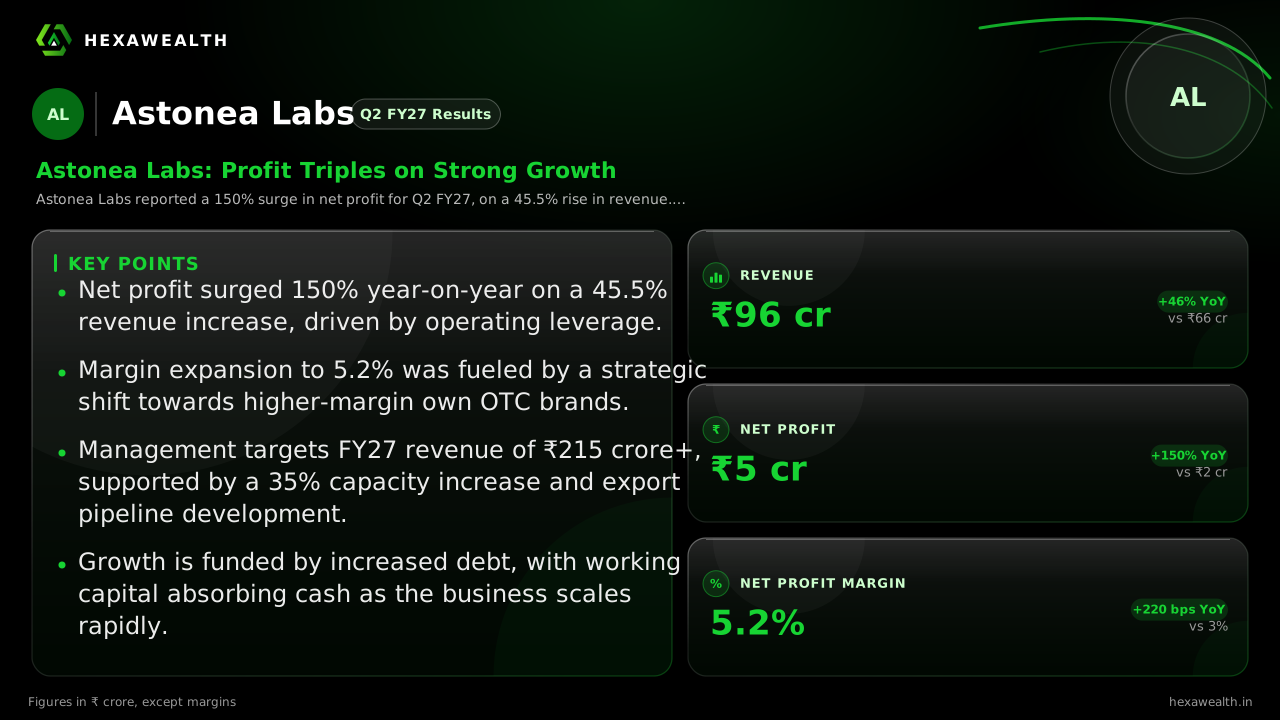
Astonea Labs reported a 150% surge in net profit for Q2 FY27, on a 45.5% rise in revenue. Margins expanded sharply as the company's own over-the-counter brands gained traction, with management guiding for over ₹215 crore in revenue this fiscal year.
For a pharmaceutical company building its own brands, the shift from contract manufacturing to higher-margin sales is the critical turn. Astonea Labs' September quarter shows that pivot taking hold, with profit growth far outpacing a strong top line as its own over-the-counter portfolio gains ground.
The numbers tell a story of accelerating momentum. Revenue hit ₹96 crore, up 45.5% from a year ago and 18.5% from the prior quarter. Net profit tripled year-on-year to ₹5 crore, and the net profit margin expanded to 5.2%, a 220-basis-point improvement.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 47.0
- Revenue (₹ Cr), Q2 FY26: 66.0
- Revenue (₹ Cr), Q4 FY26: 81.0
- Revenue (₹ Cr), Q2 FY27: 96.0
- Profit (₹ Cr), Q2 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 2.0
- Profit (₹ Cr), Q4 FY26: 3.0
- Profit (₹ Cr), Q2 FY27: 5.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 47.0
- Revenue (₹ Cr), Q2 FY26: 66.0
- Revenue (₹ Cr), Q4 FY26: 81.0
- Revenue (₹ Cr), Q2 FY27: 96.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 2.0
- Profit (₹ Cr), Q4 FY26: 3.0
- Profit (₹ Cr), Q2 FY27: 5.0
Net Profit Margin
- Net Profit Margin, Q2 FY25: 4.3%
- Net Profit Margin, Q2 FY26: 3.0%
- Net Profit Margin, Q4 FY26: 3.7%
- Net Profit Margin, Q2 FY27: 5.2%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 96.0YoY +45% | 66.0 |
| Profit (₹ Cr) | 5.0YoY +150% | 2.0 |
| Net Profit Margin | 5.2%YoY +73% | 3.0% |
The margin engine: OTC brands take the wheel
Management, cited in reports from StockFin and Multibagger.ai, attributes the sharp margin expansion to a larger contribution from its own OTC brands. This shift to higher-margin sales more than offset a 100% year-on-year rise in depreciation and a ₹0.46 crore exceptional loss from a plant fire in April.
The underlying operational strength is clear. Reports note that adjusted for the fire loss, profit growth was even stronger at about 173% year-on-year. This operational leverage is the core of the story, not one-off gains.
Funding a growth sprint
This growth is capital-intensive. Borrowings rose to ₹57.15 crore by September, according to MarketPing, funding a 35% expansion in tablet manufacturing capacity and swelling working capital. Operating cash flow was negative ₹10.44 crore for the half-year as inventories and receivables built up to support the sales ramp.
Live Chart
· ASTONEALAB
(BSE)
ISIN: INE0TG901011
The company's guidance, reported by StockFin, sets a high bar: revenue of ₹215 crore or more for FY27, implying a 45% full-year growth rate from FY26. This requires a larger second half, but management points to delayed September dispatches due to regulatory audits as a near-term catalyst for Q3.
Key Points
- Net profit surged 150% year-on-year on a 45.5% revenue increase, driven by operating leverage.
- Margin expansion to 5.2% was fueled by a strategic shift towards higher-margin own OTC brands.
- Management targets FY27 revenue of ₹215 crore+, supported by a 35% capacity increase and export pipeline development.
- Growth is funded by increased debt, with working capital absorbing cash as the business scales rapidly.
Hexa Perspective
Astonea Labs is in a high-investment phase, trading cash flow for market share and brand building. The margin expansion proves the model works when OTC sales rise, but the sustainability of this leap hinges on executing the ambitious second-half revenue target.
The stock's 10% jump on results day, per MarketPing, reflects approval of the operational beat. The risk is that the valuation, at a significant premium to the industry, already prices in the multi-year growth guidance. Execution on exports and managing the debt-funded balance sheet will determine if the current momentum is the start of a new trend or a peak.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.