All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 22 November 20262 min read

Maharaja & Speedex (SPEEDEX) Q2 FY27 Posts Strong Growth on New Capacity

Maharaja & Speedex India reported a 34.5% jump in revenue and a 42.9% rise in net profit for Q2 FY27, driven by newly added manufacturing lines.

By Vinayak Gandhi, CFA · Created 14 November 2026

Maharaja & Speedex India delivered robust Q2 FY27 results, with revenue rising 34.5% and net profit up 42.9% year-on-year. The growth was powered by its expanded manufacturing capacity and a favorable regulatory environment.

Maharaja & Speedex India’s first earnings call since its September IPO framed the quarter around a simple test: could new capacity translate into sales before competitors caught up? The answer was a clear yes, with revenue hitting ₹78 crore and profit reaching ₹10 crore.

The numbers show broad-based strength. Revenue grew 35% from a year ago, while net profit climbed 43%. The net profit margin improved by 70 basis points to 12.8%, indicating that growth came with better profitability.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Revenue & profitQ2 FY26 58.0, Q2 FY27 78.0. Q2 FY26 7.0, Q2 FY27 10.0050100150200Q2 FY26Q2 FY27
  • Revenue (₹ Cr), Q2 FY26: 58.0
  • Revenue (₹ Cr), Q2 FY27: 78.0
  • Profit (₹ Cr), Q2 FY26: 7.0
  • Profit (₹ Cr), Q2 FY27: 10.0

Revenue (₹ Cr)

Revenue (₹ Cr)Q2 FY26 58.0, Q2 FY27 78.0050100150200Q2 FY26Q2 FY27
  • Revenue (₹ Cr), Q2 FY26: 58.0
  • Revenue (₹ Cr), Q2 FY27: 78.0

Profit (₹ Cr)

Profit (₹ Cr)Q2 FY26 7.0, Q2 FY27 10.005101520Q2 FY26Q2 FY27
  • Profit (₹ Cr), Q2 FY26: 7.0
  • Profit (₹ Cr), Q2 FY27: 10.0

Net Profit Margin

Net Profit MarginQ2 FY26 12.1%, Q2 FY27 12.8%0%5%10%15%20%Q2 '26Q2 '27
  • Net Profit Margin, Q2 FY26: 12.1%
  • Net Profit Margin, Q2 FY27: 12.8%
MetricCurrentQ2 FY27Same quarter LYQ2 FY26
Revenue (₹ Cr)
78.0YoY +34%
58.0
Profit (₹ Cr)
10.0YoY +43%
7.0
Net Profit Margin
12.8%YoY +5.8%
12.1%

Growth from the factory floor

Management, in its earnings call covered by StockWatch, attributed the surge to capacity-led volume growth. New lines added in February ramped up to 95% efficiency, lifting annual capacity to 72 lakh units. An 8% price hike also contributed, according to the Q&A transcript from Sovrenn.

The profit growth outpaced sales thanks to operating leverage. A shift to more in-house manufacturing boosted gross margins, while debt repayment from IPO proceeds kept interest costs flat. Depreciation doubled due to the new machinery, but this was more than offset by the revenue surge.

The guidance that hedges its bets

Looking ahead, the company is confident but vague. CEO Akash Agarwal told analysts the firm is targeting over 45% revenue growth for FY27, as noted by ALFA Finder. This implies a sharp acceleration in the second half.

Live Chart

· SPEEDEX

(BSE)

ISIN: INE0SVD01012

The roadmap, however, lacks specific quarterly targets. Management later clarified that EBITDA margins would likely stabilize around 19-20%, not expand further, as economies of scale offset gains from a shift toward higher-margin own-brand sales.

Key Points

  • Revenue and profit grew over 35% year-on-year, driven by successful ramp-up of new manufacturing capacity.
  • Profitability improved as operating leverage kicked in, though management expects margins to hold steady near current levels.
  • The balance sheet strengthened significantly, with debt-to-equity falling to 0.04 after using IPO funds to repay borrowings.
  • Full-year guidance of over 45% growth is ambitious and requires flawless execution of the remaining capacity expansion to 103 lakh units by March 2027.

Hexa Perspective

The quarter validates the capacity-expansion thesis that underpinned the recent IPO. Growth is real and margins are healthy. The catch is in the forward view. Achieving the guided acceleration means the new lines must hit their utilization targets without a hitch, and the planned shift toward own-brand sales must gain traction.

Investors are left weighing solid execution against aspirational guidance. The stock trades at a discount to the industry, but that gap will close only if the company delivers the steep second-half ramp it has promised.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
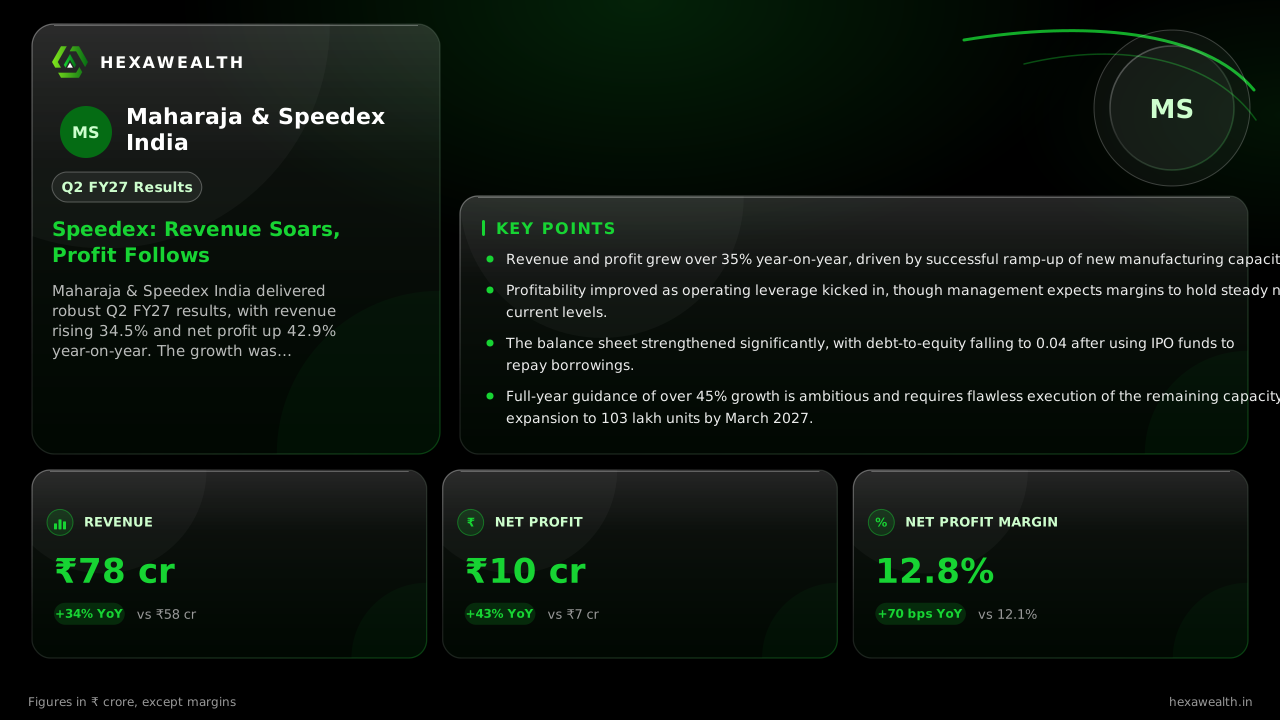
Maharaja & Speedex India (SPEEDEX) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Maharaja & Speedex India's Q2 FY27 results?
For Q2 FY27 (quarter ended September 2026), Maharaja & Speedex reported consolidated revenue of ₹78 crore, a 34.5% increase year-on-year. Net profit was ₹10 crore, up 42.9% from the same quarter last year. The net profit margin improved to 12.8%.
What drove Maharaja & Speedex India's revenue growth in Q2 FY27?
The 34.5% revenue growth was primarily capacity-led, according to management on the earnings call. New manufacturing lines ramped up production, driving higher sales volumes. An approximate 8% price increase also contributed to the top-line growth.
Why did Maharaja & Speedex India's depreciation expense double in Q2 FY27?
Depreciation expense doubled year-on-year to ₹2 crore in Q2 FY27 due to the capitalization of new plant and machinery. This investment was part of the company's capacity expansion, funded through internal accruals and IPO proceeds.
What was Maharaja & Speedex India's management guidance after Q2 FY27?
Management, on the Q2 FY27 earnings call, expressed confidence in achieving over 45% revenue growth for the full FY27. They also guided for EBITDA margins to remain sustainable around 19-19.5% and outlined a target to increase own-brand sales to 65% of revenue in 3-4 years.
Which product segment performed best for Maharaja & Speedex in Q2 FY27?
The company's stainless steel and kitchenware segment drove strong demand, leading to the 36% revenue growth for H1 FY27. Management also noted a product mix shift towards higher-value items, increasing their contribution.
What is Maharaja & Speedex India's order book status post Q2 FY27?
The company operates in a supply-constrained market, and management highlighted strong demand visibility. They stated that the expanded capacity of 103 lakh units could generate a monthly revenue run-rate of ₹23-24 crore once fully operational by March 2027.
Is Maharaja & Speedex India undertaking any capacity expansion?
Yes. The company increased capacity to 72 lakh units annually using internal funds and is executing an IPO-funded expansion to reach 103 lakh units by March 2027. This is expected to support its targeted revenue growth of over 45% for FY27.
Did Maharaja & Speedex India's Q2 results beat analyst estimates?
The company delivered strong organic growth of 36% revenue and a 19.2% EBITDA margin for H1 FY27, which was seen as a bullish print. However, analyst notes from StockWatch point out that forward guidance was hedged and lacked specific quantified targets for FY27/FY28.
Are institutional investors increasing their stake in Maharaja & Speedex India?
Yes. Following its September 2026 IPO, institutional ownership increased. Domestic Institutional Investors (DIIs) held 11.70% and Foreign Institutional Investors (FIIs) held 0.62% as of September 2026, up from zero in the prior quarter.
What are the key risks facing Maharaja & Speedex India?
Key risks include competitive intensity from established brands like Cello and Borosil, volatility in raw material (stainless steel) prices, and execution risk associated with the rapid capacity ramp-up to 103 lakh units by March 2027.
Maharaja & Speedex Q2FY27 Results: Net profit up 50% YoY to ₹9.9 crore
Maharaja & Speedex India reported a consolidated net profit of ₹9.9 crore for H1 FY27, marking a 49.7% increase year-on-year. This was driven by a 36.2% rise in revenue to ₹78.5 crore, fueled by strong demand in its stainless steel and kitchenware segment.
Maharaja & Speedex H1FY27 revenue up 36% to ₹78.5 crore
For the first half of FY27 (April-September 2026), Maharaja & Speedex India's revenue from operations grew 36% year-on-year to ₹78.5 crore. EBITDA for the period increased 52% to ₹15.1 crore, with the margin expanding to 19.2%.