LK Mehta Polymers (LKMEHTA) Q4 FY26 Profit Dips 6% Despite Strong Revenue Growth
The plastic products maker posted a 17% yearly sales jump in Q4, but higher costs and interest expenses squeezed its bottom line, highlighting margin pressure.
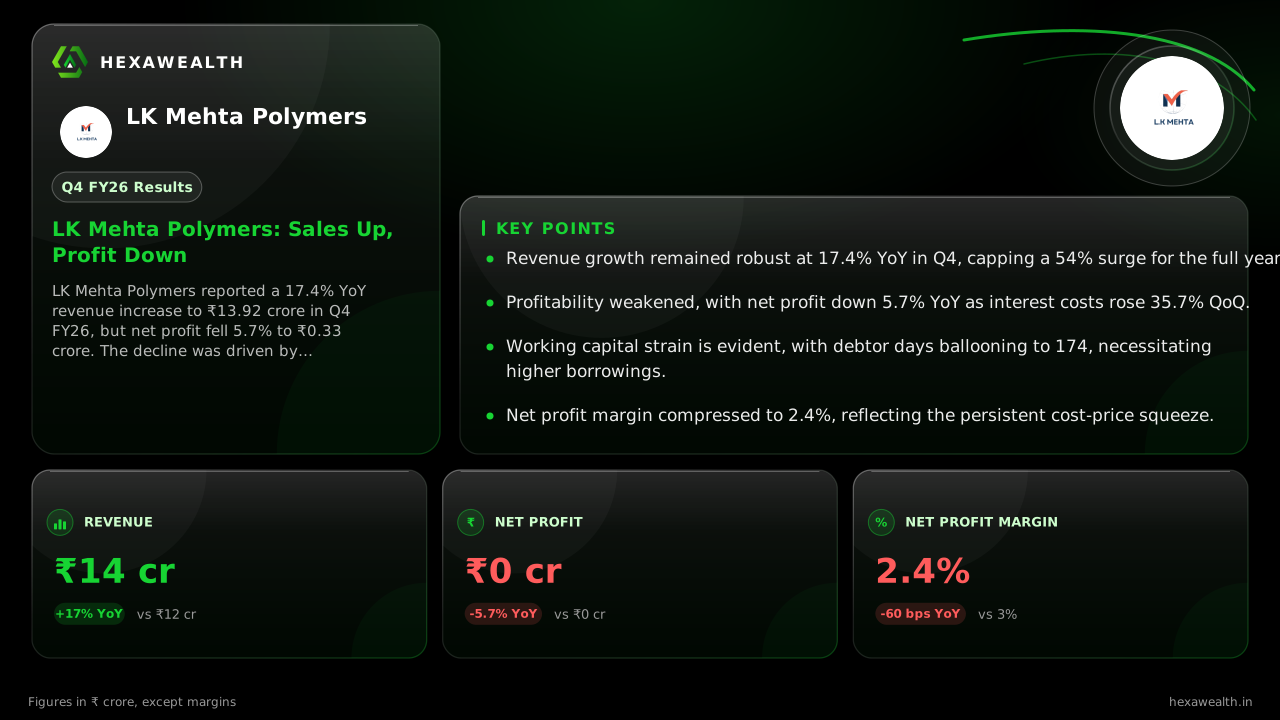
LK Mehta Polymers reported a 17.4% YoY revenue increase to ₹13.92 crore in Q4 FY26, but net profit fell 5.7% to ₹0.33 crore. The decline was driven by rising interest costs and a sharp compression in net profit margins.
For LK Mehta Polymers, a year of rapid top-line expansion ended with a familiar industrial squeeze. The quarter showed revenue growth outpacing profit, a sign that costs are rising faster than the company can pass them on.
The March quarter revenue of ₹13.92 crore was up 17.4% from a year ago, but down 8.8% sequentially from a strong September quarter. Net profit for the quarter was ₹0.33 crore, a 5.7% decline year-on-year, though it improved 10% from the previous quarter. The annual picture is starker: FY26 revenue surged 54% to ₹29.19 crore, but profit grew a modest 3.7%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 7.11
- Revenue (₹ Cr), Q3 FY25: 4.75
- Revenue (₹ Cr), Q4 FY25: 11.86
- Revenue (₹ Cr), Q2 FY26: 15.27
- Revenue (₹ Cr), Q4 FY26: 13.92
- Profit (₹ Cr), Q2 FY25: 0.25
- Profit (₹ Cr), Q3 FY25: 0.16
- Profit (₹ Cr), Q4 FY25: 0.35
- Profit (₹ Cr), Q2 FY26: 0.30
- Profit (₹ Cr), Q4 FY26: 0.33
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 7.11
- Revenue (₹ Cr), Q3 FY25: 4.75
- Revenue (₹ Cr), Q4 FY25: 11.86
- Revenue (₹ Cr), Q2 FY26: 15.27
- Revenue (₹ Cr), Q4 FY26: 13.92
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 0.25
- Profit (₹ Cr), Q3 FY25: 0.16
- Profit (₹ Cr), Q4 FY25: 0.35
- Profit (₹ Cr), Q2 FY26: 0.30
- Profit (₹ Cr), Q4 FY26: 0.33
Net Profit Margin
- Net Profit Margin, Q2 FY25: 3.5%
- Net Profit Margin, Q3 FY25: 3.4%
- Net Profit Margin, Q4 FY25: 3.0%
- Net Profit Margin, Q2 FY26: 2.0%
- Net Profit Margin, Q4 FY26: 2.4%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 13.92YoY +17% | 11.86 |
| Profit (₹ Cr) | 0.33YoY -5.7% | 0.35 |
| Net Profit Margin | 2.4%YoY -20% | 3.0% |
The cost of funding growth
The primary drag on profitability was a sharp rise in finance costs. Interest expense jumped 35.7% quarter-on-quarter and 8.6% year-on-year to ₹0.38 crore. According to a MarketPing analysis, this was fueled by a rise in short-term borrowings to ₹8.70 crore in FY26, up from ₹4.74 crore, as the company financed swelling trade receivables.
Customer payment cycles have stretched significantly. Data from Newboard.in shows debtor days extended to 174 in FY26 from 117 a year earlier, tying up more cash in working capital. This need for external funding is eating directly into the bottom line.
A margin squeeze with no quick fix
Higher raw material prices also played a role. A Global Risk Community report noted that polypropylene prices in India saw substantial increases during the period, with imported cargoes rising up to 48% in Q2 2026. While domestic prices were more moderate, the input cost pressure is clear.
Live Chart
· LKMEHTA
(BSE)
ISIN: INE0FFF01017
The result is a sustained margin compression. The company's net profit margin for the quarter was 2.4%, down 60 basis points from the same quarter last year. For the full year, the operating profit margin fell 250 basis points to 4.6%, as per the annual analysis.
Key Points
- Revenue growth remained robust at 17.4% YoY in Q4, capping a 54% surge for the full year.
- Profitability weakened, with net profit down 5.7% YoY as interest costs rose 35.7% QoQ.
- Working capital strain is evident, with debtor days ballooning to 174, necessitating higher borrowings.
- Net profit margin compressed to 2.4%, reflecting the persistent cost-price squeeze.
Hexa Perspective
The quarter underscores the challenge of a capital-intensive growth model. LK Mehta Polymers is successfully scaling sales, but the economics are being undermined by the cost of funding that very growth. The extended receivables cycle suggests either intense competition or weaker customer credit terms.
For the margin pressure to ease, the company needs either a sustained drop in polymer prices, an improvement in its working capital efficiency, or pricing power to pass costs through. With peers like Time Technoplast reporting strong margin performance, the issue appears company-specific. The trajectory of borrowings and receivables in the coming quarters will be critical to watch.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.