Dr. Lal Pathlabs (LALPATHLAB) Q2 FY27 Profit Jumps 27.5% on Record Volume Growth
The diagnostics leader posted its strongest quarterly revenue growth in five years, driven by broad-based patient and sample volume increases.
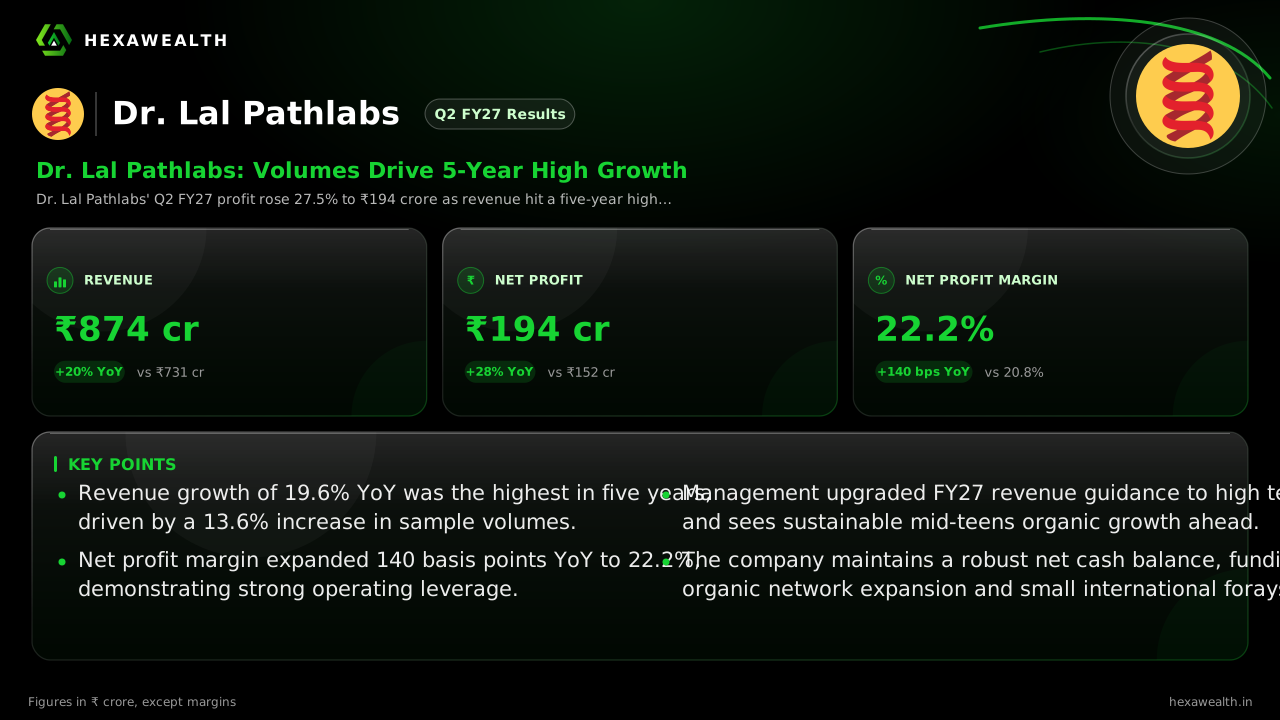
Dr. Lal Pathlabs' Q2 FY27 profit rose 27.5% to ₹194 crore as revenue hit a five-year high growth of 19.6%. The surge was powered by a 13.6% jump in sample volumes and improved operational leverage.
For India's largest diagnostic chain, growth is measured in millions of samples and patients walking through its doors. Dr. Lal Pathlabs' September quarter delivered on both, with revenue climbing 19.6% year-on-year to ₹874 crore. This marked the company's strongest quarterly growth in five years, as profit grew even faster at 27.5% to ₹194 crore.
The numbers show a business hitting its stride. Revenue per patient rose 9.7% to ₹976, while the net profit margin expanded to 22.2%. The quarter continued a steady climb from the softer performance seen a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 874.0YoY +20% | 797.7 | 730.6 |
| Profit (₹ Cr) | 194.0YoY +27% | 170.5 | 152.2 |
| Net Profit Margin | 22.2%YoY +6.7% | 21.4% | 20.8% |
The Volume Engine Fires on All Cylinders
Growth was anchored in operational metrics, not just pricing. According to the company's investor presentation, sample volumes surged 13.6% to 28.8 million while patient volumes grew 9% to 9 million. CEO Shankha Banerjee, quoted by Business Standard, noted this was driven by growing demand for specialised testing.
Management attributed the strength to a 2-3% benefit from a CGHS price revision, which will last one more quarter. The rest came from broad-based geographic growth and a richer test mix, including wellness packages. This volume leverage allowed profit to outpace revenue despite a 45.8% rise in interest expense on higher working capital.
How Long Can This Pace Last?
The company now expects full-year FY27 revenue growth in the high teens, slightly ahead of its earlier mid-teens guidance. The long-term outlook remains for sustainable mid-teens organic growth. This assumes patient volume growth of 6-7% annually, supplemented by price and mix benefits.
With a net cash position of ₹1,746 crore, the company is actively investing. Its capex plan of ₹140-150 crore for the year funds 15-18 new labs. It is also making small international acquisitions in markets like Ghana and Uzbekistan, though these are long-term projects.
Key Points
- Revenue growth of 19.6% YoY was the highest in five years, driven by a 13.6% increase in sample volumes.
- Net profit margin expanded 140 basis points YoY to 22.2%, demonstrating strong operating leverage.
- Management upgraded FY27 revenue guidance to high teens and sees sustainable mid-teens organic growth ahead.
- The company maintains a robust net cash balance, funding organic network expansion and small international forays.
Hexa Perspective
The quarter confirms Dr. Lal Pathlabs is successfully converting its massive scale into operating leverage. The margin expansion, even with rising costs, shows the power of its volume-led model in a stable pricing environment.
The key question is sustainability beyond the one-off CGHS benefit. Management's confidence in mid-teens growth hinges on continued market share gains from the unorganized sector and penetration into tier 3 towns, which already contribute 39% of revenue. The current valuation, at a discount to the industry PE, suggests the market is weighing this execution against sector-wide competitive risks.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.