Jayant (JAYAGROGN) Q2 FY27 Agro Profit Soars 135% as Margins Expand
Jayant Agro-Organics delivered a 135% surge in Q2 profit, outpacing strong revenue growth, as operating leverage and a better product mix lifted margins.
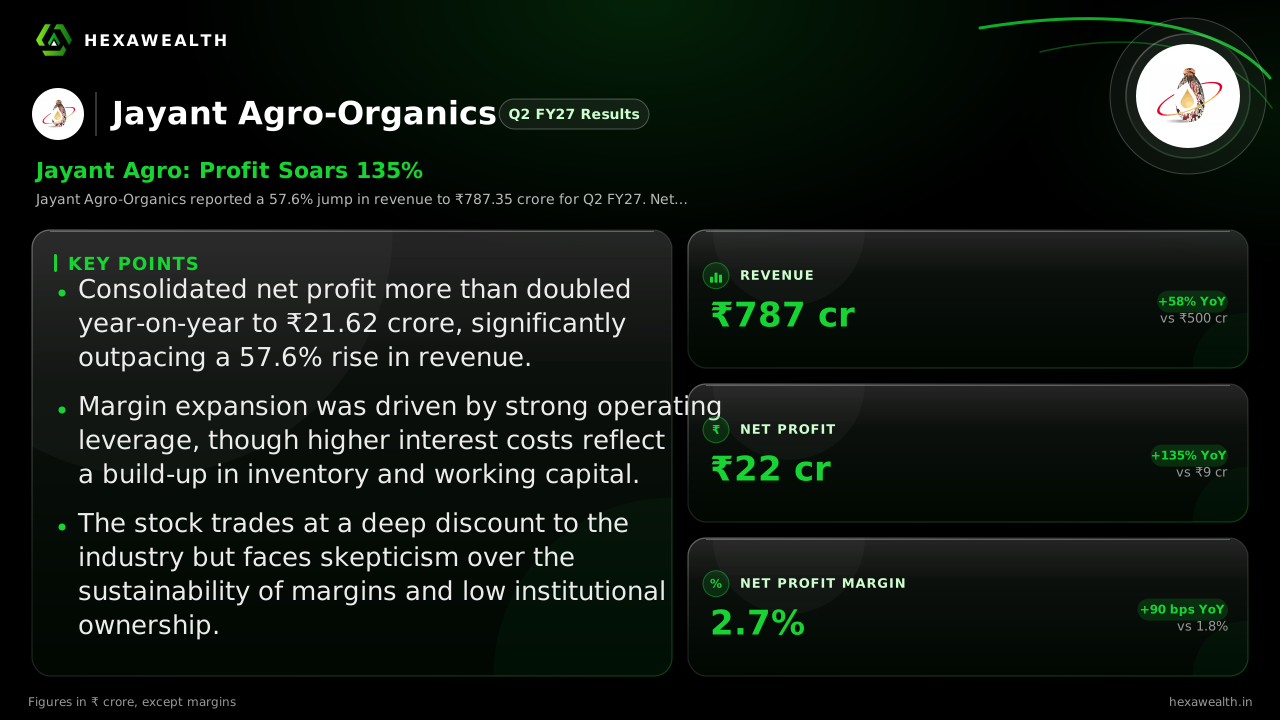
Jayant Agro-Organics reported a 57.6% jump in revenue to ₹787.35 crore for Q2 FY27. Net profit surged 134.7% to ₹21.62 crore, with margins expanding due to stronger operating performance.
For a global castor oil specialist, the quarter is won on the spread between raw seed costs and the price of refined derivatives. Jayant Agro-Organics won that spread decisively in the September quarter, turning a major revenue jump into a far larger profit surge.
Revenue rose 57.6% year-on-year to ₹787.35 crore, while net profit leapt 134.7% to ₹21.62 crore. The net profit margin expanded 90 basis points to 2.7%. Profit also grew 4.8% sequentially, even as revenue softened by 1.2% from a record Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep '25): 499.60
- Revenue (₹ Cr), Q3 FY26 (Dec '25): 587.30
- Revenue (₹ Cr), Q4 FY26 (Mar '26): 646.66
- Revenue (₹ Cr), Q1 FY27 (Jun '26): 796.61
- Revenue (₹ Cr), Q2 FY27 (Sep '26): 787.35
- Profit (₹ Cr), Q2 FY26 (Sep '25): 9.21
- Profit (₹ Cr), Q3 FY26 (Dec '25): 6.33
- Profit (₹ Cr), Q4 FY26 (Mar '26): 18.27
- Profit (₹ Cr), Q1 FY27 (Jun '26): 20.63
- Profit (₹ Cr), Q2 FY27 (Sep '26): 21.62
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep '25): 499.60
- Revenue (₹ Cr), Q3 FY26 (Dec '25): 587.30
- Revenue (₹ Cr), Q4 FY26 (Mar '26): 646.66
- Revenue (₹ Cr), Q1 FY27 (Jun '26): 796.61
- Revenue (₹ Cr), Q2 FY27 (Sep '26): 787.35
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep '25): 9.21
- Profit (₹ Cr), Q3 FY26 (Dec '25): 6.33
- Profit (₹ Cr), Q4 FY26 (Mar '26): 18.27
- Profit (₹ Cr), Q1 FY27 (Jun '26): 20.63
- Profit (₹ Cr), Q2 FY27 (Sep '26): 21.62
Net Profit Margin
- Net Profit Margin, Q2 FY26 (Sep '25): 1.8%
- Net Profit Margin, Q3 FY26 (Dec '25): 1.1%
- Net Profit Margin, Q4 FY26 (Mar '26): 2.8%
- Net Profit Margin, Q1 FY27 (Jun '26): 2.6%
- Net Profit Margin, Q2 FY27 (Sep '26): 2.7%
| Metric | CurrentQ2 FY27 (Sep '26) | PreviousQ1 FY27 (Jun '26) |
|---|---|---|
| Revenue (₹ Cr) | 787.35 | 796.61 |
| Profit (₹ Cr) | 21.62 | 20.63 |
| Net Profit Margin | 2.7% | 2.6% |
Why profit grew faster than sales
Operating profit rose 93.8% year-on-year, according to reports from Univest and Multibagg.ai, indicating strong operating leverage. The company’s focus on value-added derivatives likely supported this margin expansion. A sharp swing in other income, from a ₹1.53 crore gain last quarter to a ₹0.05 crore loss, did not derail the bottom-line momentum.
The cost of funding growth
Financing that growth came at a price. Interest expense jumped 74.2% year-on-year and 15.8% sequentially to ₹8 crore. Reports from ScanX suggest this reflects aggressive working capital deployment, with consolidated inventories surging by nearly ₹270 crore in the half-year. The company is stocking up, likely anticipating seasonal demand or favorable price moves.
How the market read the print
Despite the stellar profit growth, the stock retreated 2.5% following the results, notes MarketsMojo. This muted reaction points to investor caution over sustainability. The brokerage maintains a 'Hold' rating, citing the stock's attractive valuation—a P/E of 9.0, a 73% discount to the industry—but flags concerns over return on equity and volatile quarterly earnings.
Live Chart
· JAYAGROGN
(BSE)
ISIN: INE785A01026
Institutional interest remains negligible, with FIIs holding just 0.07%. The promoter stake is steady at 67.2%, providing stability but highlighting the stock's micro-cap and low-liquidity profile.
Key Points
- Consolidated net profit more than doubled year-on-year to ₹21.62 crore, significantly outpacing a 57.6% rise in revenue.
- Margin expansion was driven by strong operating leverage, though higher interest costs reflect a build-up in inventory and working capital.
- The stock trades at a deep discount to the industry but faces skepticism over the sustainability of margins and low institutional ownership.
Hexa Perspective
The quarter shows Jayant Agro executing well on a favorable spread in the castor oil chain. The real test is whether this margin improvement is structural or cyclical. The sharp rise in inventory and debt-funded working capital suggests the company is betting on near-term demand. If global castor oil prices, which corrected in Q2 according to Expert Market Research, stabilize or rise, that bet could pay off. If demand softens, the high inventory could pressure cash flows and margins. The deep valuation discount reflects these binary outcomes—strong operational performance weighed against execution and commodity risks.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.