Happy Forgings (HAPPYFORGE) Q2 FY27 Profit Growth Slows as Costs Catch Up
The auto parts maker posted strong revenue growth but saw its quarterly profit margin compress, with rising expenses and a major new capital expenditure plan on the horizon.
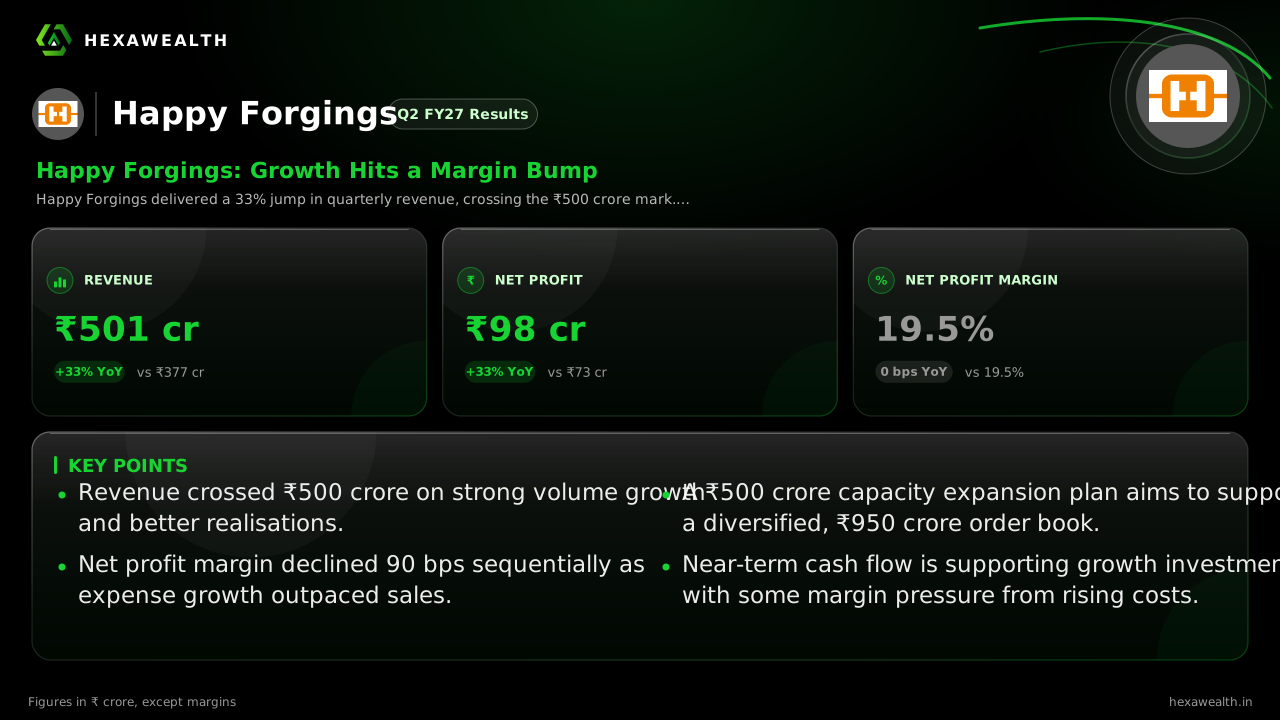
Happy Forgings delivered a 33% jump in quarterly revenue, crossing the ₹500 crore mark. However, profit growth lagged behind, and the net margin slipped sequentially as costs rose faster than sales.
Happy Forgings’ latest quarter shows a business running hot on demand but starting to feel the heat on costs. Revenue surged past ₹500 crore, yet profit growth trailed and margins narrowed, a sign that the robust top-line expansion is no longer translating fully to the bottom line.
The numbers tell a story of powerful growth meeting rising expenses. Revenue grew 33% year-on-year to ₹500.75 crore, while profit rose a similar 33% to ₹97.5 crore. Sequentially, the gap was wider: revenue grew 11.4% but profit only 6.6%, pushing the net profit margin down 90 basis points.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 500.75YoY +33% | 449.42 | 377.39 |
| Profit (₹ Cr) | 97.5YoY +33% | 91.46 | 73.44 |
| Net Profit Margin (%) | 19.5YoY 0% | 20.4 | 19.5 |
Why Profit Growth Lagged Behind
The sequential margin squeeze came from costs rising faster than sales. Total expenses jumped 12% quarter-on-quarter, outpacing the 11.4% revenue growth. Management, in its earnings call on AlphaStreet, pointed to higher raw material prices and a near-doubling of ocean freight costs for exports last quarter. While 80% of these cost increases are being passed through to customers, the lag and the residual 20% absorption are pressuring margins.
Building for a Diversified Future
Undeterred by near-term cost pressures, the company is betting heavily on future growth. Its board approved an additional ₹500 crore capital expenditure, as reported by Autocar Professional. This will add 24,000 tonnes of forging and 14,000 tonnes of machining capacity, phased over FY28 and FY29. It follows a separate ₹650 crore project for ultra-heavy components, for which management says it has already secured ₹300 crore in orders.
This aggressive expansion is backed by a healthy ₹950 crore order book, noted in a Motilal Oswal report. About half of this pipeline is for exports, and the mix is shifting towards higher-value industrial and passenger vehicle segments. With machining capacity utilisation already near 80% and expected to hit 90% by year-end, the new investment addresses an imminent bottleneck.
The Cash Flow Trade-Off
Funding this growth is drawing cash away from immediate profitability. Operating cash flow for the first half was ₹124 crore, a temporary dip as per the AlphaStreet transcript, due to working capital investments tied to the sales surge. The new ₹500 crore capex will be funded through a mix of internal accruals and about ₹300 crore in debt, according to management.
Key Points
- Revenue crossed ₹500 crore on strong volume growth and better realisations.
- Net profit margin declined 90 bps sequentially as expense growth outpaced sales.
- A ₹500 crore capacity expansion plan aims to support a diversified, ₹950 crore order book.
- Near-term cash flow is supporting growth investments, with some margin pressure from rising costs.
Hexa Perspective
The quarter underscores a transition from pure volume-led growth to a more complex phase of managing input costs and funding expansion. The margin compression is a watch point, though management’s confidence in passing through most costs provides a buffer. The real test will be executing the large capex plan without further straining profitability, especially if global freight and material costs remain volatile. The stock’s rich valuation, at a P/E of 36.2, already prices in strong future execution, leaving little room for missteps.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.