Gujarat Energy (GUJENERGY) Q2 FY27 Profit Plunges 51% as Margins Crumble
The city gas giant saw revenue hold steady but profit collapse sequentially, as volatile LNG costs and a sharp drop in industrial demand squeezed margins.
Gujarat Energy's Q2 FY27 profit fell by more than half from the previous quarter despite flat revenue. The collapse was driven by a severe margin squeeze across its gas trading and city gas distribution businesses.
For Gujarat Energy, the September quarter was a story of two halves. Surging sales from its integrated gas businesses met a sudden, severe squeeze on profitability, leaving net profit less than half of what it was just three months prior.
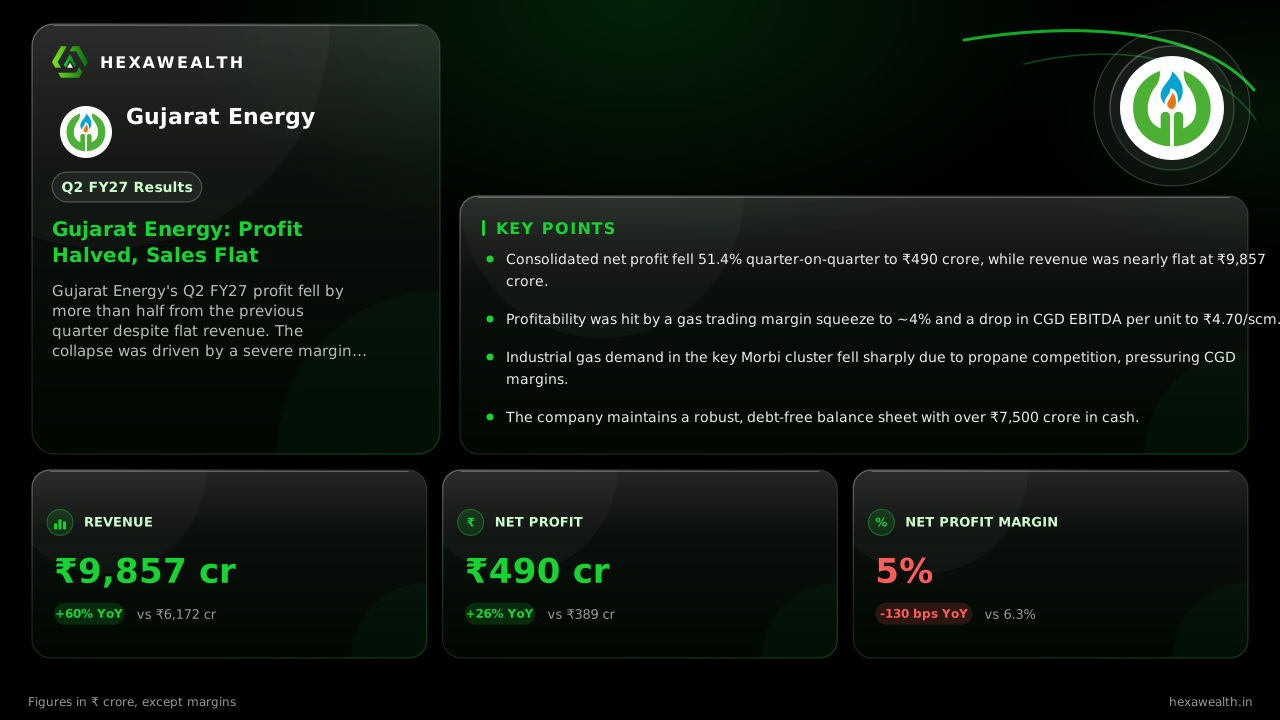
The numbers show the tension clearly. Revenue was nearly flat, inching up 0.9% sequentially to ₹9,857 crore. Profit, however, plunged 51.4% to ₹490 crore. The net profit margin fell 530 basis points to just 5%, a stark drop from 10.3% in the June quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 9,857 | 9,771 |
| Profit (₹ Cr) | 490 | 1,007 |
| Net Profit Margin (%) | 5.0 | 10.3 |
The twin margin squeeze
Two core segments saw profitability erode. According to the company's investor presentation, the gas trading margin fell to about 4% in Q2. Management, cited by GuruFocus, said force majeure disruptions to long-term Qatar volumes forced costly spot purchases, creating volatility.
In the City Gas Distribution (CGD) business, volume grew 24% year-on-year. Yet the EBITDA per unit fell to ₹4.70 per standard cubic metre from ₹5.95 a year ago. The company has revised its full-year CGD margin guidance down to ₹5-6 per scm.
A sudden drop in industrial demand
The volume story also has a crack. While overall CGD volumes grew, a key industrial cluster faltered. Management said Morbi ceramic volumes, which were around 8 MMSCMD in Q1, moderated to about 3.8 MMSCMD in Q2 and have since fallen further.
Improved propane availability and pricing created stiff competition. This sharp decline in a high-volume segment directly pressured the CGD business's overall margin performance.
A strong balance sheet for the volatility
One bright spot is the company's financial strength. The investor presentation notes a debt-free balance sheet with cash reserves exceeding ₹7,500 crore. This fortress provides stability as it navigates gas market volatility and executes a ₹1,000 crore annual capex plan.
A new government incentive scheme for domestic PNG connections, effective September 2026, could also help. It provides additional allocations of cheaper domestic gas for new connections, potentially lowering sourcing costs over time.
Key Points
- Consolidated net profit fell 51.4% quarter-on-quarter to ₹490 crore, while revenue was nearly flat at ₹9,857 crore.
- Profitability was hit by a gas trading margin squeeze to ~4% and a drop in CGD EBITDA per unit to ₹4.70/scm.
- Industrial gas demand in the key Morbi cluster fell sharply due to propane competition, pressuring CGD margins.
- The company maintains a robust, debt-free balance sheet with over ₹7,500 crore in cash.
Hexa Perspective
The quarter reveals the vulnerability of an integrated model to spot market shocks. While the long-term volume story in city gas is intact, near-term earnings are hostage to LNG price volatility and fuel competition.
The revised, lower margin guidance suggests management sees these pressures persisting. The cash pile offers patience, but the investment case now hinges on securing cost-competitive long-term gas and reigniting industrial volume growth to lift margins back toward guidance.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.