Gujarat Cotex (GUJCOTEX) Q2 FY27 Profit Surges 47% Despite Revenue Halving
The textiles trader's net profit margin more than doubled year-on-year to 5.9% in Q2 FY27, even as revenue fell 48% from a high base.
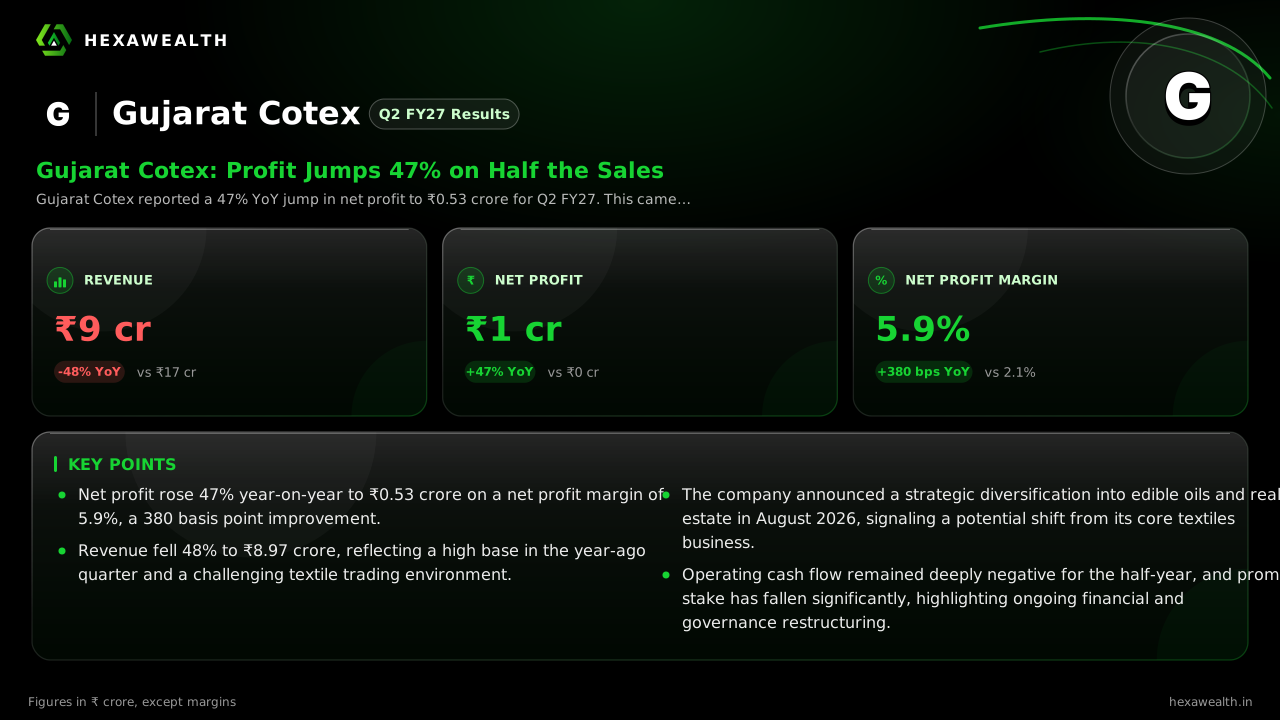
Gujarat Cotex reported a 47% YoY jump in net profit to ₹0.53 crore for Q2 FY27. This came despite revenue nearly halving to ₹8.97 crore, as the company sharply improved its net profit margin to 5.9%.
For Gujarat Cotex, a textiles trader with a history of volatile performance, the September quarter delivered a stark split. Revenue fell by nearly half compared to last year, but profit jumped 47% as the company finally turned a higher margin on a smaller sales base.
The numbers show a business in transition. Revenue was ₹8.97 crore, down 48% from the same quarter last year but up 40% from the weak June quarter. Net profit reached ₹0.53 crore, a 47% year-on-year rise and a 231% sequential surge.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Period | Sep 2026 | Jun 2026 | Sep 2025 |
| Revenue (₹ Cr) | 8.97YoY -48% | 6.39 | 17.36 |
| Profit (₹ Cr) | 0.53YoY +47% | 0.16 | 0.36 |
| Net Profit Margin (%) | 5.9YoY +181% | 2.6 | 2.1 |
The High-Base Revenue Drop
The steep revenue decline is partly a base effect. According to a StockFin.ai analysis, the company had an unusually high revenue quarter a year ago at ₹17.36 crore. The current quarter’s sales are more in line with its recent, lower run-rate, though still below the ₹9-10 crore levels seen earlier in FY26.
Where the Margin Came From
The real story is the margin expansion. The net profit margin more than doubled year-on-year to 5.9%. This was driven by a sharp reduction in total expenditure, which fell to ₹8.44 crore from ₹17.0 crore a year ago, as reported by Investywise. The company managed to protect profitability on a much-reduced scale of operations.
A Pivot Away from Textiles?
The core textiles trading business faces a tough environment. Industry reports note cotton yarn prices surged nearly 60% earlier this year, squeezing margins for traders. This pressure may be pushing a strategic shift. In August 2026, the company announced plans to diversify into edible oils and real estate through new divisions named Prabhat Oils and Prabhat Infratech.
Cash and Capital Concerns
Despite the quarterly profit, the financial structure is under strain. For the half-year ended September 2026, the cash flow statement shows net cash used in operating activities was -₹1,931.84 lakhs, as per Investywise. This was offset by financing activities, likely related to a rights issue. Promoter holding also dropped sharply to 1.7% in Q1 FY27, notes StockFin.ai, raising questions about long-term commitment.
Key Points
- Net profit rose 47% year-on-year to ₹0.53 crore on a net profit margin of 5.9%, a 380 basis point improvement.
- Revenue fell 48% to ₹8.97 crore, reflecting a high base in the year-ago quarter and a challenging textile trading environment.
- The company announced a strategic diversification into edible oils and real estate in August 2026, signaling a potential shift from its core textiles business.
- Operating cash flow remained deeply negative for the half-year, and promoter stake has fallen significantly, highlighting ongoing financial and governance restructuring.
Hexa Perspective
This quarter's profit jump is a function of severe cost control on shrunken revenue, not a sign of operational strength. The planned diversification into edible oils and infrastructure is a clear admission that the traditional textile trading model is under duress from volatile input costs. The path ahead hinges on executing this pivot while managing a weak balance sheet and low promoter alignment. Until the new divisions generate revenue, the company remains reliant on a textiles business where sustainable margin expansion looks difficult.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.