Groarc Industries (GROARC) Q2 FY27 Revenue Plunges 63% as Business Model Shows Extreme Volatility
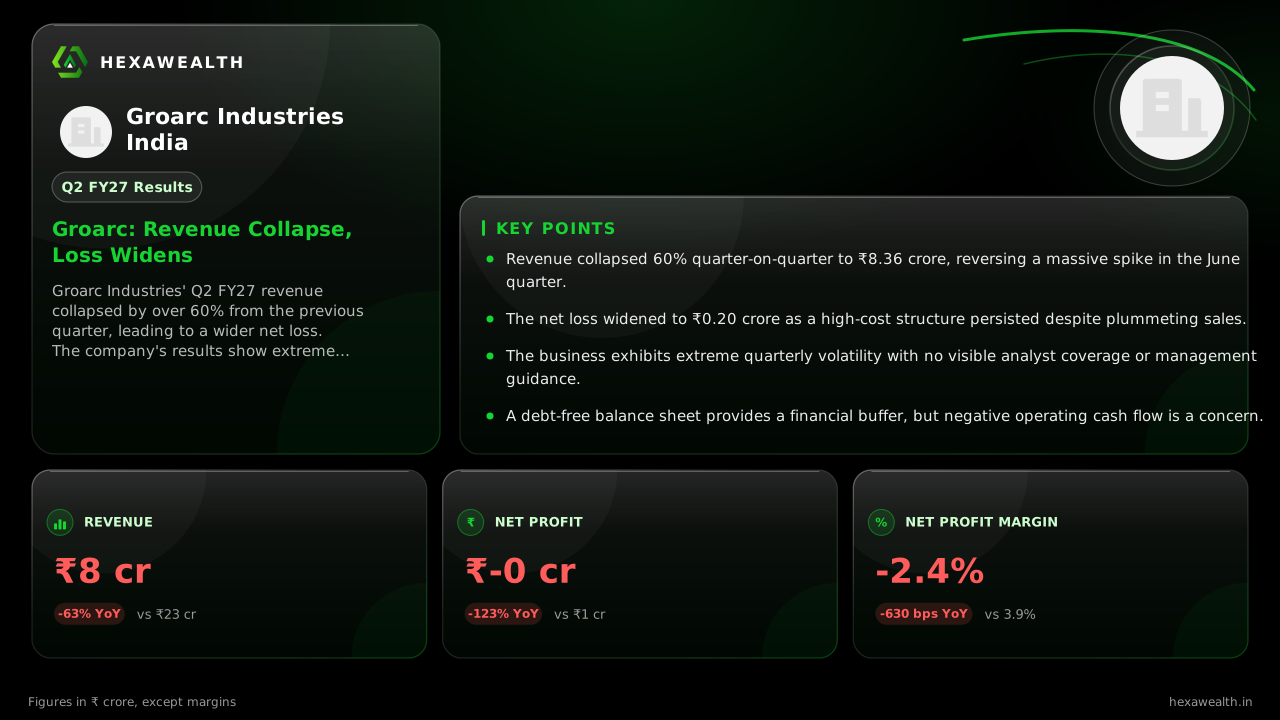
Groarc Industries reported a 63% year-on-year revenue drop to ₹8.36 crore in Q2 FY27, with a net loss of ₹0.20 crore, highlighting the severe volatility in its operations.
Groarc Industries' Q2 FY27 revenue collapsed by over 60% from the previous quarter, leading to a wider net loss. The company's results show extreme volatility, raising questions about the sustainability of its business model and its path forward.
For Groarc Industries, the story is one of extreme volatility, not steady decline. The food processor's September quarter saw revenue collapse from its June peak, turning a small loss into a larger one and leaving investors questioning what business it is actually running.
The numbers show a company struggling to find its footing. Revenue fell 63% from a year ago and 60% from the prior quarter to ₹8.36 crore. The net loss widened to ₹0.20 crore, pushing the PAT margin to -2.4%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Period | Sep 2026 | Jun 2026 | Sep 2025 |
| Revenue (₹ Cr) | 8.36YoY -63% | 21.05 | 22.54 |
| Profit (₹ Cr) | -0.20YoY -123% | -0.06 | 0.87 |
| Net Profit Margin (%) | -2.4YoY -162% | -0.3 | 3.9 |
From a Surge to a Collapse
The June quarter's revenue of ₹21.05 crore, as reported by Whalesbook, was driven by a massive 1,250% sequential jump. That surge now looks like an isolated spike, not a new normal. The subsequent 60% drop suggests the business lacks recurring contracts or stable demand, operating in bursts of activity followed by quiet periods.
The Costs That Won't Bend
Despite the revenue plunge, the net loss only widened modestly from ₹0.06 crore. This points to a high fixed-cost structure that does not scale down with sales. The company's operating margin was already negative in the June quarter, according to The Annexure, indicating underlying profitability challenges regardless of top-line volatility.
A Business in Search of a Model
Research shows no analyst coverage or management guidance for the quarter, a silence that speaks volumes. The stock has fallen 43% over the past year, trading at a steep 90% discount to its industry's average P/E. Investors are clearly pricing in the operational uncertainty and lack of a clear strategic narrative.
The company maintains a strong balance sheet with zero debt and a high current ratio, providing a cushion. However, cash flow from operations was deeply negative in the last full year, per Sharpely data, meaning it is burning through its reserves to sustain these volatile operations.
Key Points
- Revenue collapsed 60% quarter-on-quarter to ₹8.36 crore, reversing a massive spike in the June quarter.
- The net loss widened to ₹0.20 crore as a high-cost structure persisted despite plummeting sales.
- The business exhibits extreme quarterly volatility with no visible analyst coverage or management guidance.
- A debt-free balance sheet provides a financial buffer, but negative operating cash flow is a concern.
Hexa Perspective
The quarter confirms Groarc Industries is a story of unpredictable revenue pulses, not managed growth. The absence of a steady operational rhythm makes forecasting impossible and raises fundamental questions about its customer base and business model.
Investors are left weighing a pristine balance sheet against an unviable-looking income statement. For the stock to re-rate, the company must demonstrate it can generate revenue consistently at a level that covers its apparently rigid cost base. Until then, the deep valuation discount is likely to persist.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.